
Founder & Chairman of Glorious Sun Enterprises Chun Kam Yeung Buys More Stock
Glorious Sun Enterprises Limited (HKG:393) shareholders (or potential shareholders) will be happy to see that the Founder & Chairman, Chun Kam Yeung, recently bought a whopping HK$1.3b worth of stock, at a price of HK$36,000. There's no denying a buy of that magnitude suggests conviction in a brighter future, although we do note that proportionally it only increased their holding by 0.05%.
Glorious Sun Enterprises Insider Transactions Over The Last Year
In fact, the recent purchase by Chun Kam Yeung was the biggest purchase of Glorious Sun Enterprises shares made by an insider individual in the last twelve months, according to our records. That means that an insider was happy to buy shares at above the current price of HK$1.33. Their view may have changed since then, but at least it shows they felt optimistic at the time. In our view, the price an insider pays for shares is very important. Generally speaking, it catches our eye when insiders have purchased shares at above current prices, as it suggests they believed the shares were worth buying, even at a higher price.
Glorious Sun Enterprises insiders may have bought shares in the last year, but they didn't sell any. The average buy price was around HK$164. These transactions suggest that insiders have considered the current price attractive. You can see the insider transactions (by companies and individuals) over the last year depicted in the chart below. By clicking on the graph below, you can see the precise details of each insider transaction!
See our latest analysis for Glorious Sun Enterprises
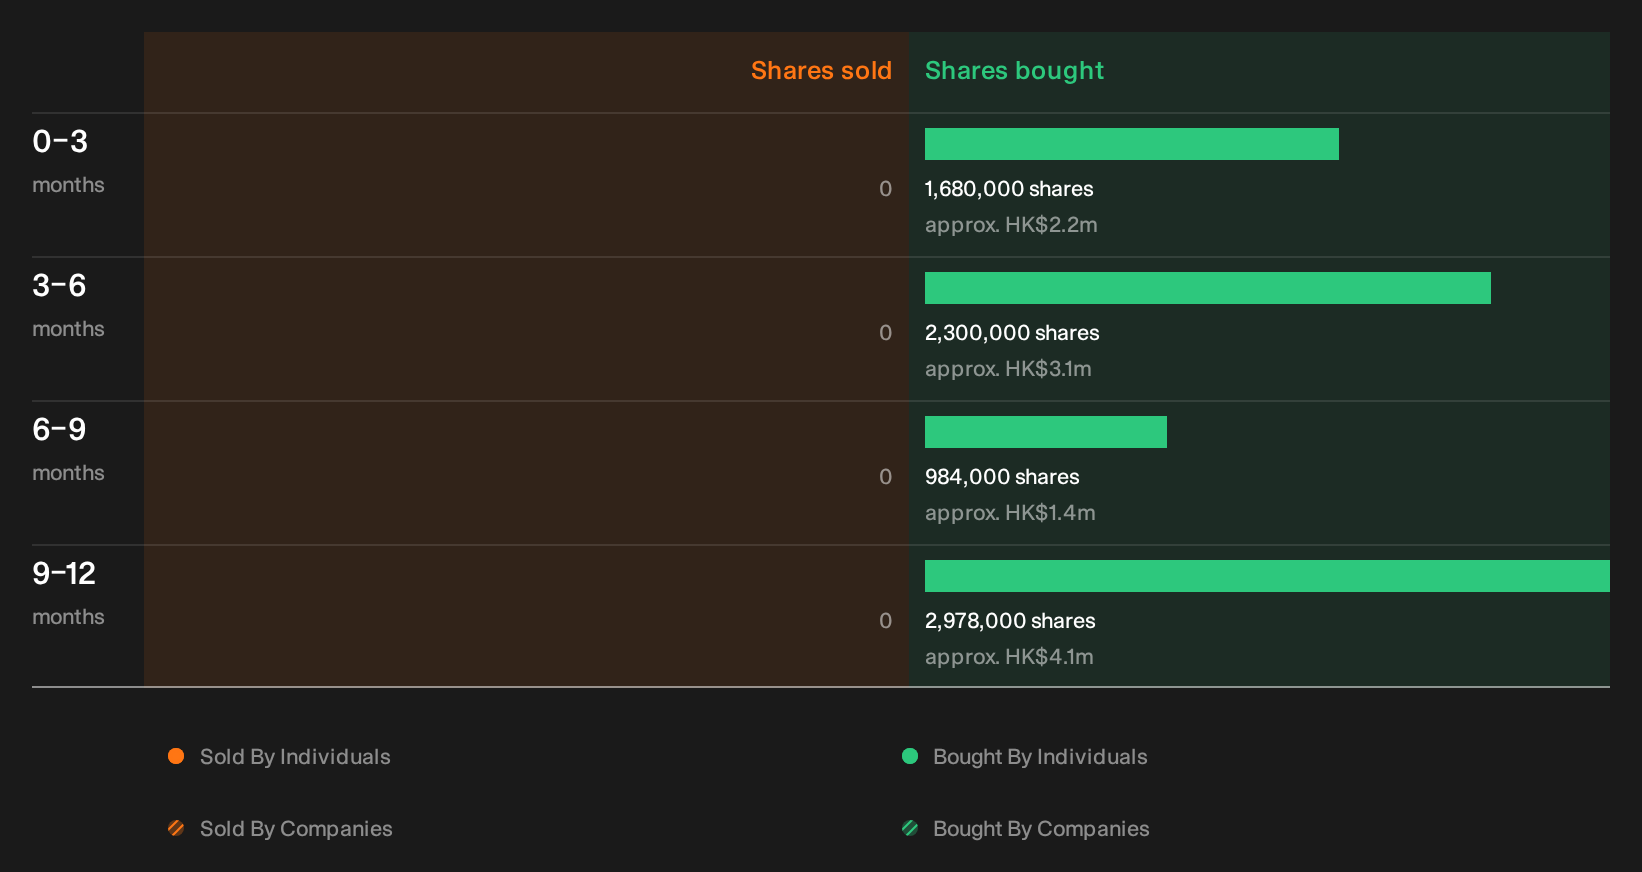
There are always plenty of stocks that insiders are buying. If investing in lesser known companies is your style, you could take a look at this free list of companies. (Hint: insiders have been buying them).
Does Glorious Sun Enterprises Boast High Insider Ownership?
Another way to test the alignment between the leaders of a company and other shareholders is to look at how many shares they own. A high insider ownership often makes company leadership more mindful of shareholder interests. It appears that Glorious Sun Enterprises insiders own 15% of the company, worth about HK$300m. This level of insider ownership is good but just short of being particularly stand-out. It certainly does suggest a reasonable degree of alignment.
So What Does This Data Suggest About Glorious Sun Enterprises Insiders?
The recent insider purchase is heartening. We also take confidence from the longer term picture of insider transactions. Once you factor in the high insider ownership, it certainly seems like insiders are positive about Glorious Sun Enterprises. One for the watchlist, at least! So these insider transactions can help us build a thesis about the stock, but it's also worthwhile knowing the risks facing this company. While conducting our analysis, we found that Glorious Sun Enterprises has 1 warning sign and it would be unwise to ignore it.
Of course Glorious Sun Enterprises may not be the best stock to buy. So you may wish to see this free collection of high quality companies.
For the purposes of this article, insiders are those individuals who report their transactions to the relevant regulatory body. We currently account for open market transactions and private dispositions of direct interests only, but not derivative transactions or indirect interests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.