
Is Sodexo (ENXTPA:SW) Fully Valued After Its Q3 Growth Beat And Guidance Raise?
Sodexo stock: why Q3 guidance and a new marketing lead matter now
Sodexo (ENXTPA:SW) drew fresh attention after third quarter fiscal 2026 organic growth came in ahead of expectations and management lifted full year organic revenue guidance to a range of 1.2% to 1.5%.
The group also highlighted stronger commercial momentum, underpinned by Sodexo Live! in North America. A separate leadership move saw Sarabjeet Ghadiok join as Head of Marketing to support growth initiatives.
At a share price of €55.15, Sodexo has logged a 7-day share price return of 2.04% and a 90-day share price return of 4.65%. The 1-year total shareholder return of 9.19% and 5-year total shareholder return of 31.03% point to steady but not rapid compounding as investors weigh the upgraded guidance and leadership changes against the past three-year total shareholder return, which declined 6.74%, and more recent 30-day share price weakness of 2.22%.
Scan other services and outsourcing players showing similar momentum to Sodexo by checking our hand picked list of 225 resilient stocks with low risk scores gaining attention after recent guidance and leadership updates.
Sodexo has just raised its guidance, yet the share price only inched higher after a soft 30 day patch. Is this a moment to act now, or to wait for a sharper pullback before the valuation stacks up for you?
Most Popular Narrative: 1% Overvalued
Sodexo last closed at €55.15 against a narrative fair value of €54.63, which frames the stock as roughly in line with what detailed long term execution assumptions imply.
The current valuation implies the market already credits Sodexo with being fairly valued on successful delivery of its 2030 growth and margin goals, rather than pricing in a turnaround that is still unproven.
See why 12 investors see Sodexo as 1% overvalued.
Result: Fair Value of €54.63 (OVERVALUED)
Still, Sodexo’s €1b transformation spend and higher ongoing commercial costs could pressure cash generation if execution problems and cultural bottlenecks persist longer than analysts model.
Find out about the key risks to this Sodexo narrative.
Another View: Sodexo through the earnings lens
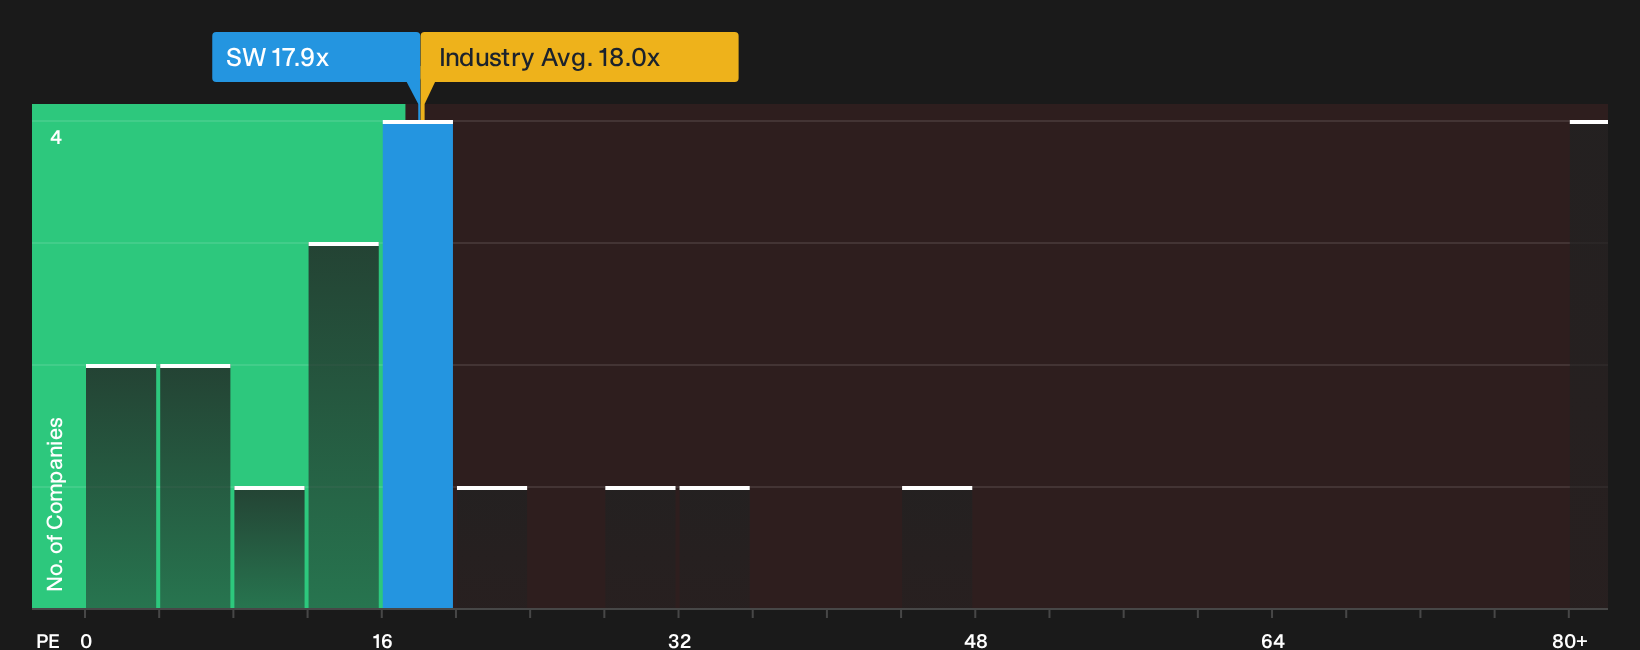
The first narrative frames Sodexo as roughly fairly priced against long term cash flow expectations. A different picture appears when you look at the simple P/E comparison. At 17.9x, the stock trades just under the European Hospitality group on 18.0x and well below peers on 62.1x.
The fair ratio for Sodexo sits at 23.7x, which is materially higher than the current multiple. That gap suggests the market is either discounting execution and balance sheet risks, or leaving room for sentiment to shift. Which side of that trade do you think you are on as the Shift & Grow 2030 plan unfolds?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sodexo is drawing mixed reactions, with upgraded guidance on one side and execution questions on the other. Move quickly to weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Sodexo?
If Sodexo has you thinking harder about price, quality, and risk, do not stop here. Broader comparisons can sharpen your next move and highlight blind spots.
- Target stronger value opportunities by checking companies on our 185 high quality undervalued stocks that combine quality fundamentals with prices the market might be overlooking.
- Prioritise resilience and sleep better at night by reviewing the list of solid balance sheet and fundamentals (204 results) that can help anchor your portfolio when conditions shift.
- Get in early on tomorrow’s potential leaders by scanning the 620 high quality undiscovered gems before crowd attention makes them harder to ignore.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com