
Shanghai Henlius Biotech (SEHK:2696) Could Be 73% Undervalued On Chairman Change
Shanghai Henlius Biotech (SEHK:2696) is back in focus after both Chairman Wenjie Zhang and independent director Yihao Zhang resigned on 30 September 2026, and long-time industry executive Dr. Xingli Wang stepped in as the new chair.
Shanghai Henlius Biotech’s share price has slipped over the past quarter, with a 30 day share price return of down 15.24% and a 90 day move of down 15.91%, while the 1 year total shareholder return of down 19.82% sits against a very large 3 year total shareholder return gain of about 4.9x. This suggests long term holders are still ahead even as near term momentum has faded around these boardroom changes.
Spot opportunities other investors might be missing by scanning our hand picked 620 high quality undiscovered gems, which feature fundamentals that echo parts of the Shanghai Henlius Biotech story.For Shanghai Henlius Biotech, the chart tells one story of past multibagger gains, while the fresh slide on board changes hints at another. Is most of the rerating already behind it, or does the valuation still leave room ahead?
Preferred P/E of 28.6x for Shanghai Henlius Biotech: Is it justified?
On traditional metrics, Shanghai Henlius Biotech trades on a P/E of 28.6x, which puts a clear price on the HK$53.4 last close and the earnings investors are paying for.
The P/E ratio links the HK$53.4 share price to the company’s current earnings per share, so it shows how many dollars of price the market is placing on each dollar of profit. For a research driven biotech business with marketed oncology and autoimmune products, that figure often reflects how confident investors feel about the durability of existing cash flows as well as the potential from the pipeline.
Against close peers tracked in the same valuation framework, that 28.6x P/E is described as good value compared with a peer average of 53.1x. At the same time, the stock is described as expensive versus the wider Hong Kong biotechs industry average of 16.7x, which implies the broader sector trades on a lower earnings multiple. Relative to an estimated fair P/E of 21.6x, the current level is also described as expensive, which indicates the market could move closer to that lower figure if enthusiasm cools or earnings do not keep pace.
Explore the SWS fair ratio for Shanghai Henlius Biotech.
Result: Price-to-earnings of 28.6x (OVERVALUED).
Still, the Shanghai Henlius Biotech story carries clear pressure points, including reliance on Mainland China revenue and execution risk across a broad, capital intensive biologics pipeline.
Find out about the key risks to this Shanghai Henlius Biotech narrative.
Another View: SWS DCF model points to deep undervaluation
The P/E picture presents Shanghai Henlius Biotech as expensive at 28.6x, yet the SWS DCF model suggests a different perspective. At HK$53.4, the shares are described as trading well below an estimated future cash flow value of HK$200.73. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
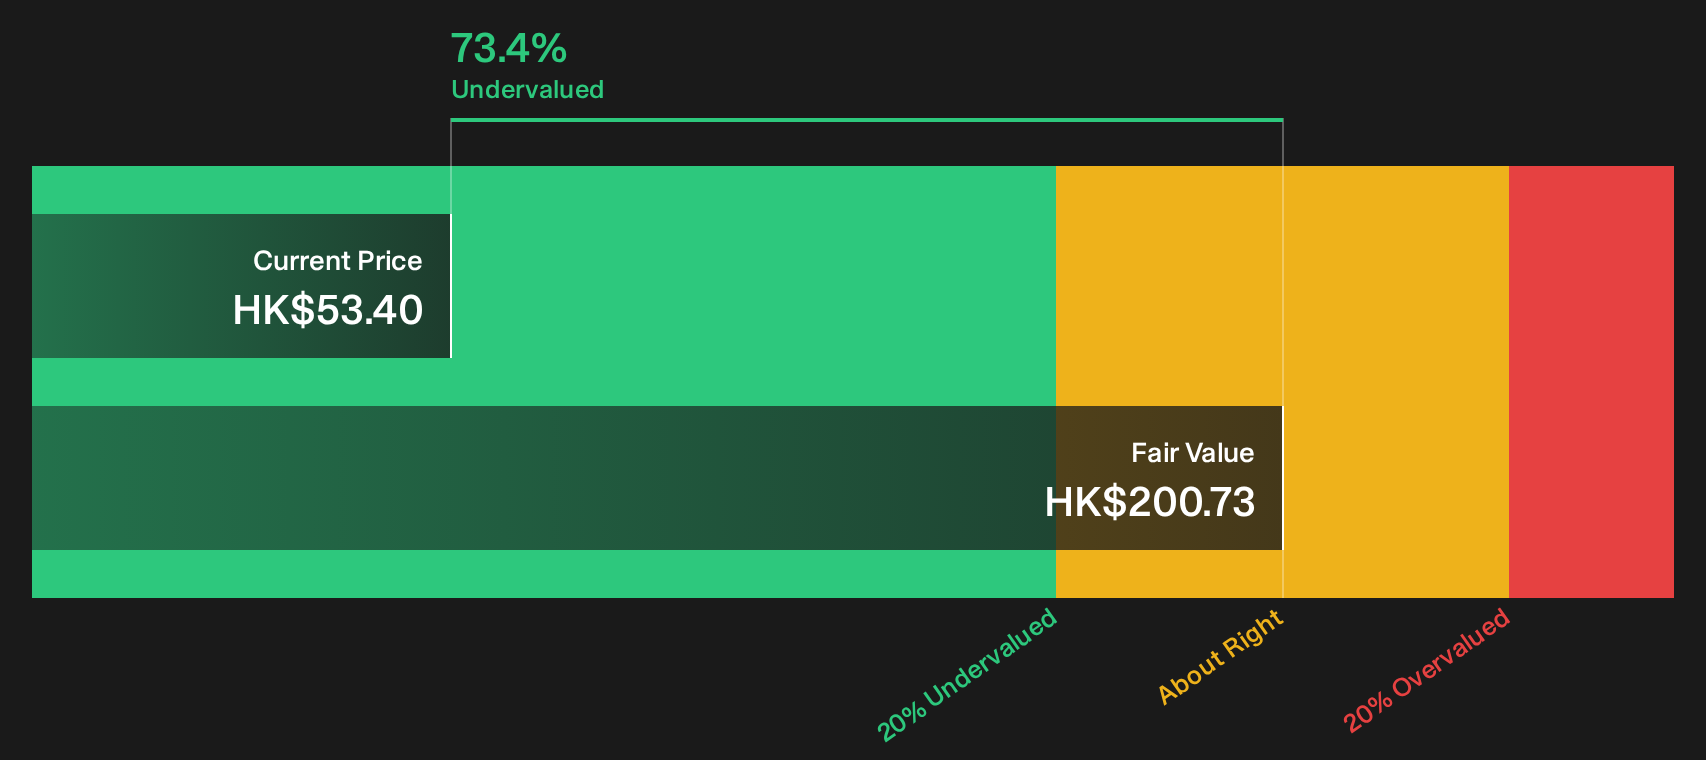
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Henlius Biotech for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Shanghai Henlius Biotech can feel confusing, especially when both pressure points and bright spots sit side by side in the data. Act before the next headline sets the tone for you, and review the balance of risks and potential upsides yourself by starting with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Shanghai Henlius Biotech?
Do not stop your research with one stock when a broader watchlist can reveal better fits for your goals and risk comfort level.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (204 results) that filters for financial strength first.
- Hunt for quality at a sensible price through a focused 185 high quality undervalued stocks that highlights companies where fundamentals and valuation line up more tightly.
- Prioritise capital protection and downside control by reviewing a 225 resilient stocks with low risk scores built to surface businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com