
Trevi Therapeutics (TRVI) Following GSK Exit Is Its Chronic Cough Valuation Back In Focus
Trevi Therapeutics (TRVI) drew fresh attention after GSK halted work on its chronic cough drug, leaving Trevi’s nalbuphine extended release program with new clinical data and a major conference spotlight under closer investor scrutiny.
Trevi Therapeutics has been back under pressure in the short term, with the share price down 22.7% over the past month and 32.3% over the past quarter, even though total shareholder return over the past year is 20.6% and extremely high over three and five years. This suggests long term holders have already seen a very strong payoff, while near term momentum has cooled as investors reassess the risk and potential of its chronic cough program.
Scan other chronic cough and respiratory players moving on trial results with our hand picked list of 33 healthcare AI stocks that are drawing fresh interest from research focused investors.
Trevi Therapeutics now trades at a sharp discount to published analyst targets after a steep pullback. Does that gap reflect mispricing, or a fair reset once the current trial risk is priced in?
Most Popular Narrative: 56% Undervalued
Against the last close of $12.29, the most followed Trevi Therapeutics narrative is anchored on a fair value of $28.18. This frames the recent pullback as a large gap between current pricing and what long term chronic cough potential might support.
Approximately US$188 million in cash, cash equivalents and marketable securities at year end 2025, with an indicated runway into 2028, funds top line data across key IPF, non IPF ILD and refractory chronic cough studies. This limits near term financing pressure and can support more controlled decision making around future capital structure, share count and potential earnings per share.
See why 1 investors see Trevi Therapeutics as 56% undervalued.
Result: Fair Value of $28.18 (UNDERVALUED)
Still, the entire Trevi Therapeutics story leans on Haduvio, so any trial stumble or tighter than expected label could quickly unwind that perceived valuation gap.
Find out about the key risks to this Trevi Therapeutics narrative.
Another View: Trevi Therapeutics On Book Value
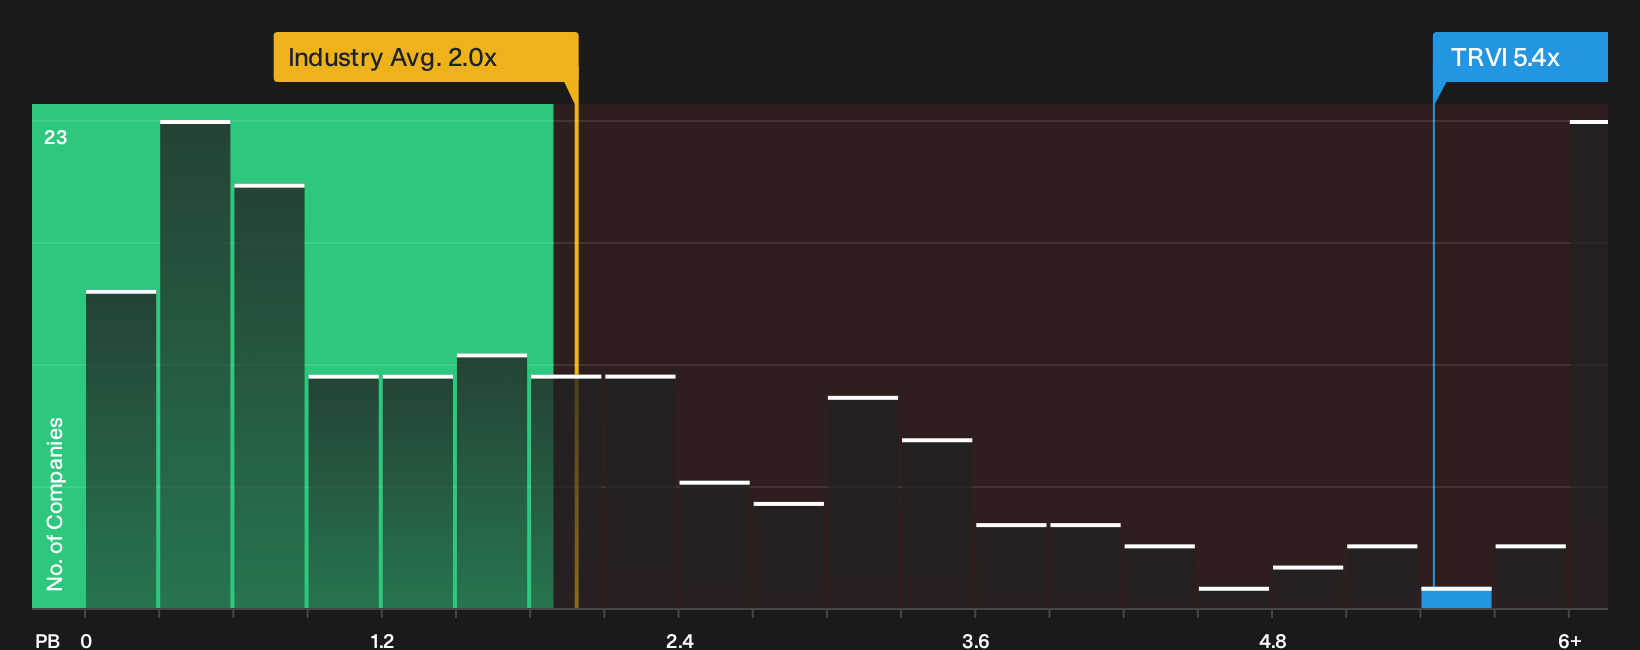
The analyst narrative frames Trevi Therapeutics as 56% undervalued, yet its current P/B of 5.4x is high compared with the US Pharmaceuticals average of 2x and a peer group average of 3.7x. A rich P/B like that can signal investors are already paying up for future success. How comfortable are you relying on long dated trial outcomes to support that premium?
See what the numbers say about this price, with our valuation breakdown providing added context through the See what the numbers say about this price — find out in our valuation breakdown..
To put that premium side by side with the sector, review the latest relative valuation snapshot in
Next Steps
Big valuation gaps like this often split opinion, so it makes sense to move quickly, review the data yourself, and weigh every red flag. Start by checking the 4 important warning signs.
Looking for more Trevi Therapeutics style ideas?
If you only stop at Trevi Therapeutics, you miss the chance to compare it against other compelling setups that could sharpen your entire portfolio playbook.
- Target resilient compounding potential by scanning companies flagged as 32 resilient stocks with low risk scores that may offer a calmer ride when volatility picks up.
- Hunt for quality at a discount by reviewing our curated pool of 20 high quality undiscovered gems that many investors are not watching closely yet.
- Strengthen your income stream by filtering for 8 dividend fortresses that pair high yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com