
3 Global Growth Stocks With Rising AI And Infrastructure Demand
Global growth now looks more concentrated, inflation risks run hotter and AI is taking a bigger share of the headlines, which together create a very different backdrop for large multinationals. That mix can reward certain globally exposed businesses while leaving others struggling with higher costs and tighter funding. This article unpacks what that might mean and highlights three stocks from our screener that appear most exposed to this new macro story.
The stocks featured below are just a starting sample from this theme, and the full screen surfaced 18 more large multinationals with equally compelling narratives that are not covered in the article. To identify and analyze the highest conviction global large-cap growth beneficiaries of concentrated GDP expansion, head straight to the Global Large-Cap Growth Beneficiaries of Concentrated GDP Expansion screener.
Arrow Electronics (ARW)
Arrow Electronics plugs directly into the screener theme through its role connecting global electronics manufacturers and enterprise IT projects to the capex cycles shaping growth in major economies. This is why its exposure to higher value workloads has drawn fresh attention.
Arrow Electronics is a global technology distributor with around US$25.4b of revenue from Global Components and about US$10.5b from Global ECS services and solutions, and a market value near US$11.5b.
Accelerating adoption of cloud, infrastructure software, cybersecurity and AI related workloads, reflected in ECS billings of more than US$6.4b in Q1 2026 and a backlog that was over 75% higher year over year by Q2 2026, increases Arrow Electronics exposure to higher margin software and services that can influence revenue mix and non GAAP margins.
What happens to Arrow Electronics earnings power if a single assumption about how that mix shift unfolds proves too optimistic or too cautious?
If that mix shift is central to your thesis on Arrow Electronics, read the full narrative for Arrow Electronics to see how accelerating workloads, capital intensity and execution risk really line up.

Tokyo Seimitsu (TSE:7729)
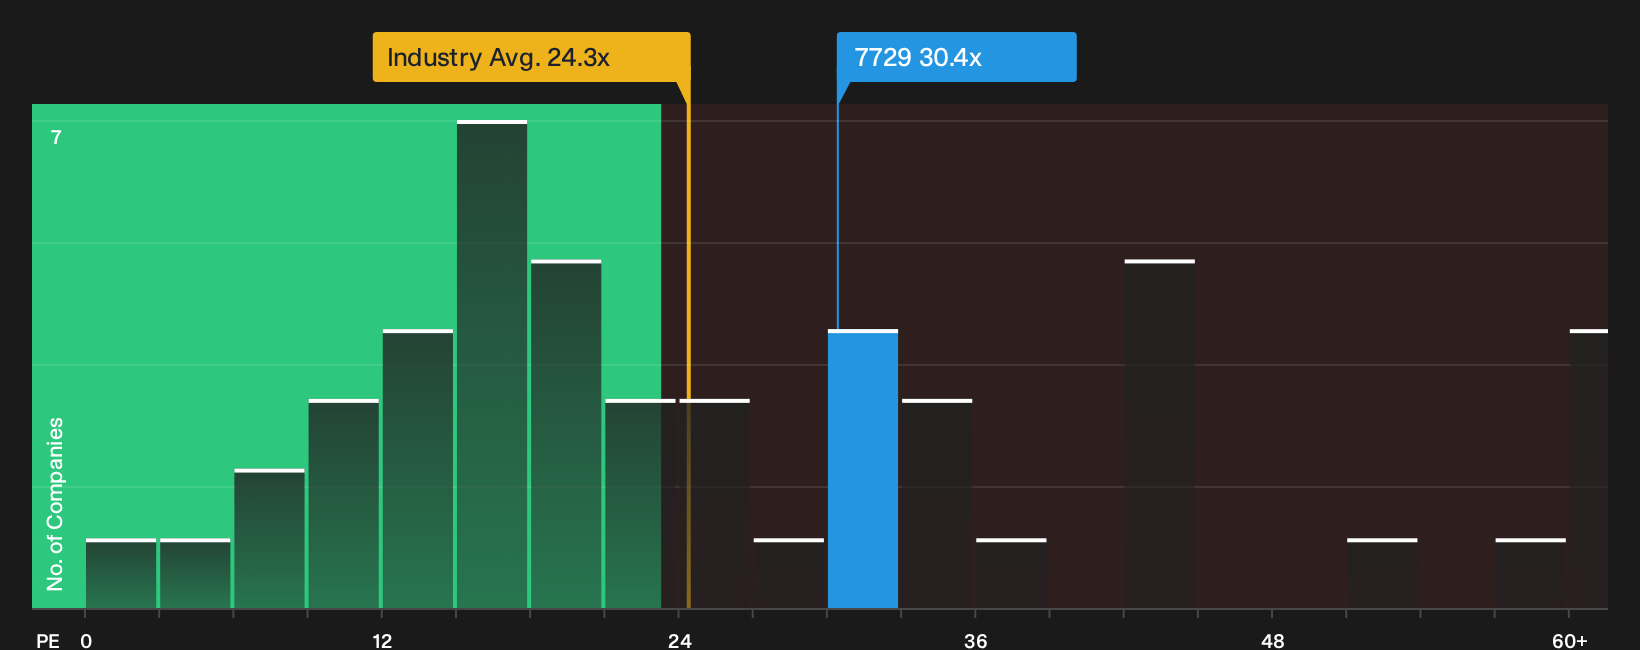
Tokyo Seimitsu supplies wafer dicing, probing and precision measuring gear across East Asia and worldwide, directly linking its ¥132.9b semiconductor production equipment and ¥39.8b measuring equipment operations to concentrated manufacturing and tech investment. With a roughly ¥794.7b market value, it fits the large cap, export oriented growth profile of this screener.
Tokyo Seimitsu plugs into the screener theme as a pure play way to gain exposure to concentrated GDP growth through semiconductor capex and precision metrology orders across leading Asian and global hubs. Earnings and revenue expectations point to double digit growth rates, yet a 30.4x P/E and full reliance on external borrowing leave much resting on how one unseen pressure shapes future cash flow.
That hidden pressure on future cash flow is exactly what the 2 key rewards and 1 important major warning sign examines so you can see how growth expectations compare with balance sheet strain.
Hitachi (TSE:6501)
Hitachi ties directly into the Global Large-Cap Growth Beneficiaries of Concentrated GDP Expansion theme through its mix of digital systems, green energy and mobility projects that link everyday infrastructure to global capex cycles across major economies.
Hitachi generates about ¥3,464.3b from Energy, ¥3,352.3b from Connective Industries and ¥3,012.3b from Digital Systems & Services, with smaller contributions from Mobility and Others, and carries a market value near ¥25.8t.
Persistent, robust demand for power grid upgrades and renewable energy integration, notably in Europe and North America, is contributing to growth in Hitachi's Energy sector. Continued investment in electrification and grid modernization is expected to play an important role in shaping future revenue and margin outcomes.
What happens to Hitachi’s margin potential if just one assumption about how quickly that backlog converts into profitable projects proves too optimistic or too slow?
If that timing question is front of mind, read the full narrative for Hitachi to see how accelerating grid demand, execution risk and valuation expectations really intersect.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Breakout stories can gain momentum while data is still under the radar. Avoid falling behind the crowd. Consider acting early.
- Target steadier compounding potential by reviewing a 8 dividend fortresses that screens for durability and yield strength before everyone else starts focusing on the same payouts.
- Explore possible next-wave infrastructure momentum through a curated 43 power grid technology and infrastructure stocks while these grid and electrification plays may still reflect earlier demand expectations.
- Explore future-focused industrial themes by scanning a handpicked 91 robotics and automation stocks before automation leaders receive broader market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com