
CG Oncology (CGON) Names New Commercial Chief As Valuation Turns Back To Cretostimogene
CG Oncology (CGON) has appointed Isabel Kalofonos as Chief Commercial Officer, placing a seasoned commercial leader in charge as the business prepares for a potential launch of cretostimogene grenadenorepvec.
Recent trading tells a mixed story for CG Oncology. The share price has fallen around 14% over the past three months and about 14% over the last 30 days, yet year to date the share price return is up 49.32% and the 1 year total shareholder return is 45.62%. This points to longer term momentum cooling after a strong run into the current US$62.40 level, as investors weigh execution risks around cretostimogene grenadenorepvec against the potential benefits of moves like the Kalofonos appointment.
Scan beyond CG Oncology and line up other late-stage biopharma players with fresh catalysts using our curated list of 20 high quality undiscovered gems.
CG Oncology now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after this pullback. Is that a cautious read on launch and execution risk, or a mispricing that the numbers do not support?
Most Popular Narrative: 32% Undervalued
CG Oncology’s most followed valuation story pegs fair value around $91.08 per share, well above the recent $62.40 close. This puts the focus squarely on how much of cretostimogene’s potential is already in the price.
Planned expansion of cretostimogene into intermediate risk and BCG exposed NMIBC, supported by the fully enrolled 364 patient PIVOT-006 trial and the planned randomized Phase 3 in roughly 50,000 BCG exposed patients, could materially widen CG Oncology’s treated population and influence future revenue scale.
See why 2 investors see CG Oncology as 31% undervalued.
Result: Fair Value of $91.08 (UNDERVALUED)
Still, the CG Oncology story can break if regulators squeeze cretostimogene pricing, or if operating costs stay heavy enough to delay any path to profitability.
Find out about the key risks to this CG Oncology narrative.
Another View On CG Oncology’s Valuation
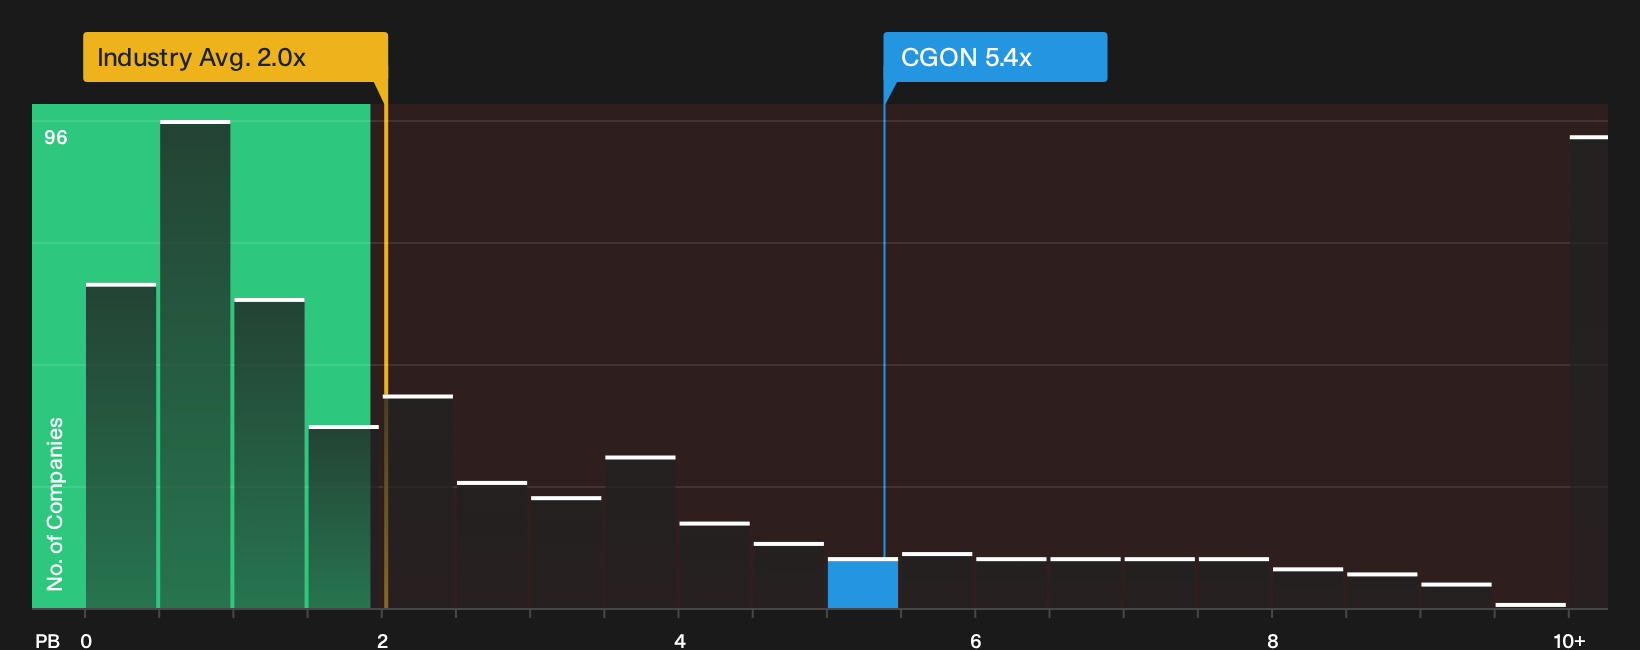
On one hand, analysts see CG Oncology as undervalued against a fair value of $91.08 per share. On the other, the stock trades on a P/B of 5.4x compared with 2x for the wider US Biotechs group and 8.6x across peers, which signals both quality expectations and real valuation risk if sentiment cools.
For investors weighing those signals side by side, the key question is whether that richer P/B multiple reflects durable potential around cretostimogene, or whether expectations have already moved ahead of what the balance sheet and current losses can justify over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can be useful, especially when a story like CG Oncology splits opinion between risk and upside. Move quickly, review the underlying numbers, and then weigh the 3 key rewards and 1 important warning sign
Looking for more CG Oncology investment ideas?
If CG Oncology has your attention, do not stop here. Broaden your watchlist with focused stock ideas filtered by quality, risk, and value so you do not miss the next opportunity.
- Target resilient businesses that prioritise capital strength by scanning a list of solid balance sheet and fundamentals (25 results) that is designed to highlight sturdier balance sheets and fundamentals.
- Hunt for quality at a reasonable price by running through a curated pool of 32 high quality undervalued stocks that align with disciplined valuation checks.
- Reduce unpleasant surprises by filtering for companies that clear higher safety bars using a focused set of 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com