
Mercamander (09615) made it through “one step away”. Are there any movies?
On September 1, Mercamander (09615) landed on the Hong Kong Stock Exchange as “the first stock with smart eyes and intelligence”. Oversubscribing by 3,835 times set a new Hong Kong stock robot IPO record. 250,000 investors flocked to the market, and there was no shortage of scenery for a while.
At the beginning of the listing, the market was very interested in its two main storylines — one was an “eye and brain” full-stack self-developed intelligent story; the other was an imaginary space where incremental capital from the mainland was relayed into the market after being incorporated into the Hong Kong Stock Connect.
However, the carnival soon subsided. On the first day of listing, Mercamand's stock price broke and fell to HK$99.8, down 1.87% from the issue price. More than a month later, its stock price fell to HK$80 (as of the close of trading on October 13), with a total market value of about HK$10 billion, a discount of about 21% from the issue price (HK$101.7). It's just a little short of the Hong Kong Stock Connect threshold.
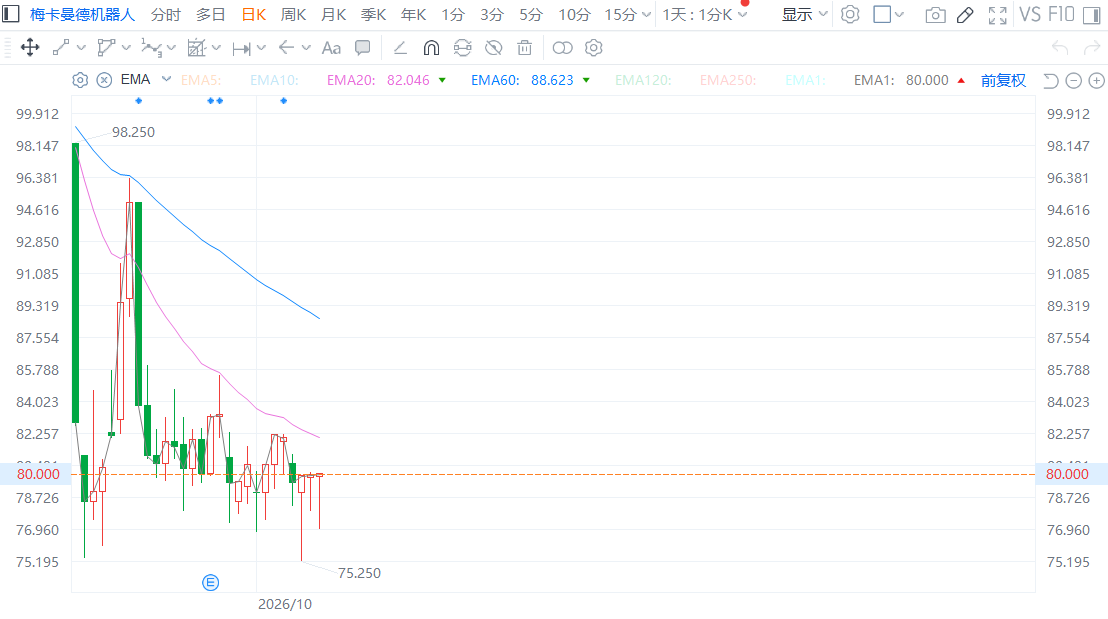
(Market source: Futu)
Access: Xiyin is on the fast track, while Mecamand is on the slow lane
In fact, on the surface, the Mercamander case is a question of whether the market capitalization is sufficient; in fact, it is an accurate calculation question of caliber and time.
According to big data estimates such as LiveReport, as of June 30, 2026, the market capitalization threshold for non-A+H Hong Kong stock listed companies to enter the Hang Seng Composite Index and Hong Kong Stock Connect is about HK$10.156 billion, and the current total market value of Mercamander is about HK$10 billion. According to this caliber, the gap is about 1.5%. The corresponding share price needs to rise from HK$80 to HK$81.2, an increase of about 1.5%.
However, the total market value is a figure under the “full circulation assumption.” What really needs to be considered is the market value of the Mercamander Hong Kong stock market (market value corresponding to Hong Kong stock capital) — currently about HK$9.48 billion, about HK$1.1 billion from the HK$10.156 billion gap. The corresponding share price needs to rise to about HK$89.8, an increase of about 12.2%.
What's more important is the time dimension. The Hong Kong Stock Connect assessment is the average month-end market value for the 12 months before the inspection date, not the market value at a single point in time. Mercamander was only listed in September. As of the base date of December 31, only 4 full months can be counted, and the market value for the first 8 months was zero. Even if the stock price reached HK$90, the rolling 12-month average market value was still far below the threshold.
But why did Xiyin, which went public on the same day as Mecamand, get through early?
According to reports, the Hang Seng Composite Index has a quick inclusion rule: if the closing market value on the first day of the IPO is in the top 10% of the Hang Seng Composite Index constituent stocks, it can be directly included in the index on the 10th trading day.
Xiyin, which was listed on the same day on September 1, closed with a market value of about HK$205 billion on the first day of listing. The rapid inclusion mechanism was triggered on the second day of listing, which officially took effect on September 15. However, the market value of Mercamand on the first day of listing was about HK$12.5 billion, more than one order of magnitude below the top 10% threshold. Fast Track is closed, and we can only wait for the semi-annual adjustment window. The next reference date is December 31. Results will be announced in February 2027 and effective in March.
This also means that when the gong was knocked on the same day, Xiyin took the fast track, while Mecamand took the slow lane.
It is worth noting that even if the market capitalization is up to standard and the time is satisfied, there is still a higher wall in front of Mecamand.
According to Zhitong Finance, Mecamand is listed as an 18C special technology company and uses a structure with the same shares and different rights. According to the Hong Kong Stock Connect rules, for the first time, such companies must meet three additional conditions: 6 months of listing plus 20 trading days, an average daily market value of not less than HK$20 billion on the 183 day before the inspection date, and a total turnover of not less than HK$6 billion during the same period. Meanwhile, HK$20 billion is double the current market value of Mercamand.
The front door has a $10.156 billion threshold, and the back door has a 20 billion dollar wall — it's easy to see that getting through for Mecamand was a two-door test.
30x PS valuation interrogation: the narrative is ahead of revenue
If credit cards are concerned with the system and liquidity, then the deeper wander is hidden in a more essential question: Why is the market actually priced?
Mercamander's IPO price corresponds to about 30 times PS, which is the pricing for embodying smart forward space. However, looking back at the 2026 interim report, the company achieved revenue of 240 million yuan, a year-on-year increase of 54.7%; gross profit of 154 million yuan, increasing gross margin from 61.4% to 65.0%; signing new orders of 335 million yuan, up 75.3% year on year; and overseas revenue of 100 million yuan, up 68.3% year on year. The repurchase rate is 93.9%, and customers cover more than 100 Fortune 500 companies. This data is sufficient proof that commercialization capacity is speeding up.
However, the concerns are also clearly visible: the company is still in a state of loss, and with intense R&D investment, it is still far from the break-even point. According to the interim report data, in the first half of the year, Mecamand's operating losses increased to 774.54 million yuan, and R&D investment of 80.1 million yuan, an increase of 72.9% over the previous year. R&D expenses accounted for 33.8% of total revenue.
In terms of revenue structure, MECH-GPT and MECH-Hand, the two highly anticipated products, are expected to be launched on a large scale at the end of 2026 according to the prospectus plan, and commercial-scale revenue will only be generated in the second half of 2027. Currently, more than 99% of the company's revenue comes from the industrial 3D camera and robot guidance business — this is an “eye” business, a mature business that customers repurchase, and can clearly calculate accounts.
The so-called intelligent storytelling is more of a long-term story oriented to the future, and has not yet been fully realized in revenue statements. This also means that buying a 30x PS is about the future of “hands and brains,” but what is written on the ledger is still the present “eye.”
And this also explains in depth why Mercamand's stock price is stagnating — the market is willing to pay a premium for an intelligent narrative, but the interim report data is not enough to convince investors that the premium can be converted into profit.
Summarize
So, Mercamander is one step away. Is there any drama?
If Mecamand's stock price continues to run above HK$80 until the December 31 reference date, and the trading volume increases effectively, the rolling average market value is expected to gradually approach the threshold, and it is obvious that it will break through.
But this requires two prerequisites to be established at the same time: first, the short-term stock price rose from the current HK$80 to over HK$90 and stabilized, corresponding to an increase of about 12%; second, the average daily turnover increased by at least one order of magnitude from the current level of HK$80 million.
As of the close of trading on October 13, Mercamand's full-day turnover was HK$14.182 million, and October 9 and October 12 also had 11.6059 million and HK$14.182 million respectively. The basis for 10 million level of liquidity is already in place. If the stock price rises from HK$80 to HK$90 and stabilizes until the base date of December 31, while trading continues to expand, the rolling average market value is expected to approach the HK$10.156 billion threshold, and entry will go from being a step away. Conversely, if the stock price is trading at HK$80 for a long time and the transaction returns to the level of several million HKD, the December reference date will still be stuck outside the door. We will only have to wait for the next window and continue to face the 20 billion dollar high market value wall of 18C's shares without equal rights.
The real game breaker is still performance: if Mech-GPT and Mech-Hand can launch and form orders as scheduled at the end of 2026, and revenue moves from “eye” to “eye hand”, and losses narrow with scale, southbound capital will have a reason to stay for a long time; if new products skip tickets and revenue still rely on 3D cameras on one leg, it will be difficult to obtain continuous incremental funding even if they are struggling to get through.
As a result, Mecamander has made it through, but the drama is about volume and price, and even more on performance. It first stabilizes at HK$90, increases volume, and then allows orders and profits to pick up.