
Cloudflare (NET) Stock May Be Overvalued After Strong Q2 Growth
Cloudflare has delivered very large 3 year gains for shareholders, and that kind of run naturally raises a blunt question for anyone looking at the stock today. Is the current price still grounded in what the business is generating through its sales, or has enthusiasm moved ahead of the underlying revenue base.
- The share price is up about 4.4x over 3 years, which puts real pressure on the question of how much sales the company needs to support that kind of re-rating.
- Recent revenue growth and rising non GAAP operating margin, helped by demand for Zero Trust security and developer workloads, can influence how much investors are willing to pay for each dollar of Cloudflare's sales.
- There is a second opinion on Cloudflare worth weighing. See what analysts think Cloudflare's shares could be worth.
For investors, the debate is whether Cloudflare's current market value is justified by its sales when judged against the Fair Ratio benchmark.
If you want more than one high growth internet stock on your radar, consider using a focused screen of 92 AI infrastructure stocks.
Is Cloudflare Getting Expensive on Sales?
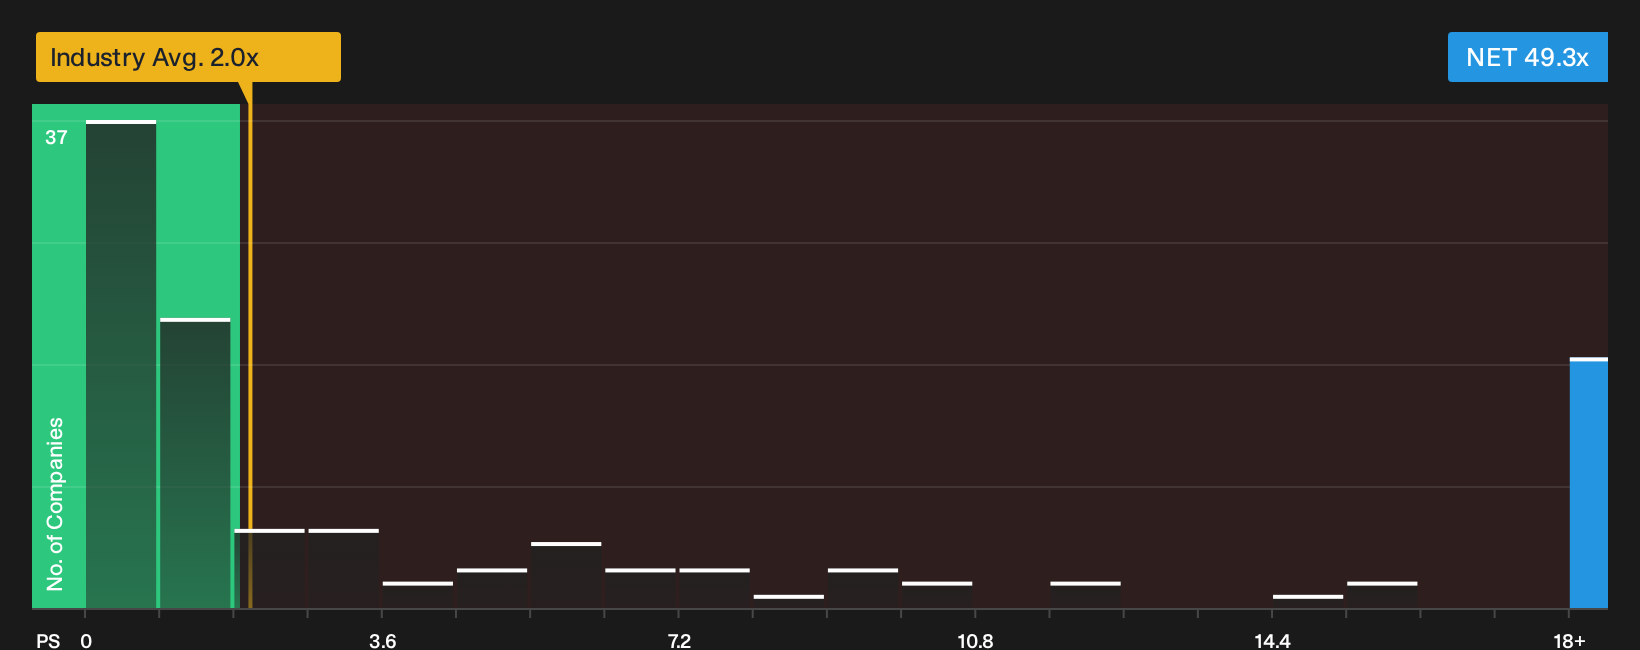
P/S is a cleaner lens for Cloudflare because the business is still priced more on its revenue potential than on current earnings power. On this measure, the stock trades on a P/S of about 49.3x, compared with an IT sector average of roughly 1.9x and a peer group closer to 15.2x. That spread suggests investors are paying a hefty premium for Cloudflare's growth profile and product reach instead of treating it as a typical software vendor.
The Fair Ratio model, which blends the company’s growth outlook, margins, sector, size and risk profile into a tailored benchmark, still flags Cloudflare as overvalued on sales. Because the gap between the present P/S and that framework is so wide, the figure appears more like a warning signal that the shares price in a lot of future execution rather than a precise target. Despite the strong Q2 revenue print and margin progress, the valuation already embeds high expectations, so investors need to decide whether that revenue trajectory and business quality justify paying such a rich multiple. Explore the numbers behind Cloudflare's P/S valuation.
The Cloudflare Narrative: What Would Justify Today's Price?
Cloudflare's valuation debate only really comes into focus once you spell out what kind of future the market is implicitly paying for. Simply Wall St Narratives sit between that puzzle and the current share price, since they lay out which paths for growth, margins and earnings would need to unfold for the stock to be worth materially more or less than today. Each one ties a fair value to a clear story about Cloudflare's potential catalysts and its key risks so you can see over time which scenario is actually taking shape on the Community page.
Cloudflare splits opinion, with one group arguing the current multiple still leaves upside while another views the stock as richly priced on optimistic assumptions.
Bull case: 16% undervalued
"Acceleration of Zero Trust and SASE consolidation, as enterprises replace legacy VPNs and point solutions with Cloudflare’s unified platform, supports premium pricing..."
Discover why this Narrative puts Cloudflare at 16% undervalued.
Bear case: 108% overvalued
"Cloudflare may be one of the cleaner infrastructure names in the Q-Day conversation, but the stock already prices in a lot of quality..."
Explore why this Narrative puts Cloudflare at 108% overvalued.
One more angle on Cloudflare that investors often miss
There is a final piece worth checking before you move on, which is how professional forecasters currently map out Cloudflare's revenue and earnings a few years from now compared with today's valuation. Explore where analysts expect Cloudflare to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com