
How Record Sales Will Impact Urban Outfitters Stock
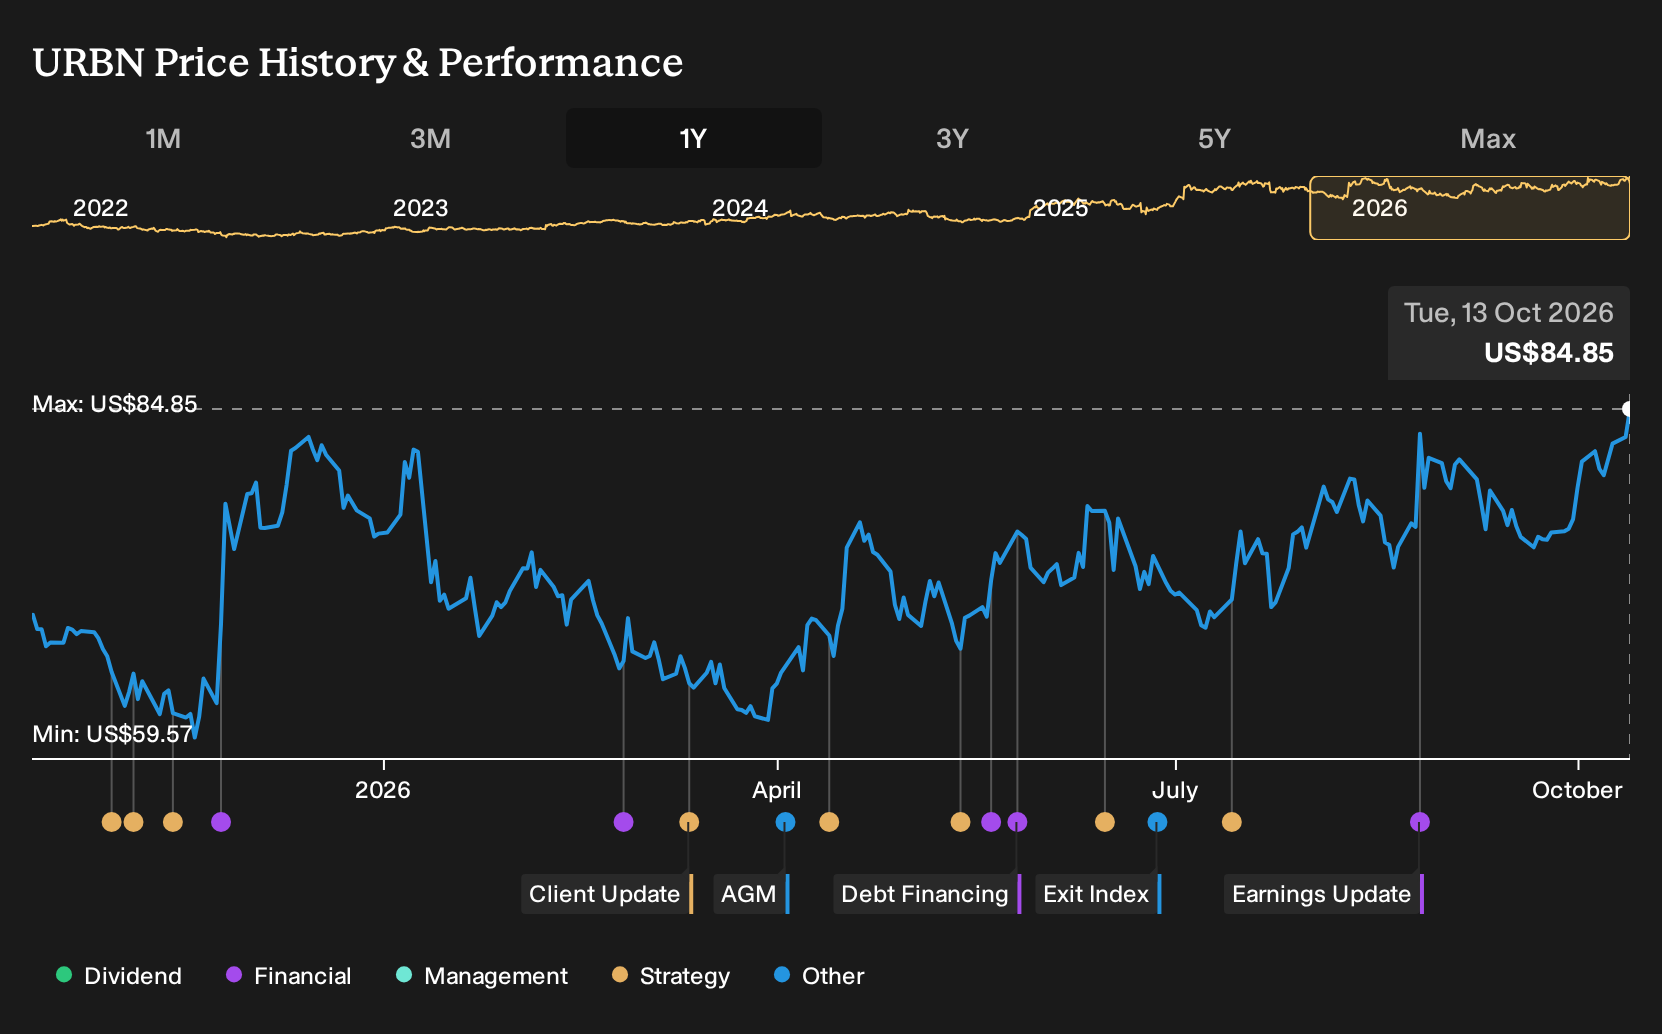
- Urban Outfitters reported its eighth consecutive quarter of record sales and profits, with Q2 fiscal 2027 adjusted earnings of US$1.72 per share on US$1.66b in revenue.
- The streak of record quarters highlights consistent demand across the retailer’s multi brand portfolio and rental offering Nuuly, indicating that its mix of concepts and channels is resonating with customers.
- This article examines how Urban Outfitters’ record streak of quarterly sales and profits relates to the company’s broader investment narrative.
Scan beyond Urban Outfitters’ record-setting run to see which other retailers show similar momentum in our curated list of 32 high quality undervalued stocks.
Urban Outfitters Investment Narrative Recap
Urban Outfitters appeals most if you believe its multi brand model, Nuuly subscription arm, and Free People ecosystem can keep pulling in consistent demand while cost headwinds stay manageable. The recent run of record quarters and the Q2 fiscal 2027 print support that broader thesis, so the latest results largely reinforce, rather than change, the near term story.
The key near term swing factor is whether sales hold up well enough to absorb higher marketing, store growth, and freight costs without squeezing margins. Pressure at Anthropologie and fuel related surcharges remain the biggest operational risks, since prolonged markdowns or sticky delivery expenses could cap profitability even if revenue stays healthy.
The most relevant fresh data point is Q2 fiscal 2027, where Urban Outfitters posted adjusted earnings of US$1.72 per share on US$1.66b in revenue and extended its streak to eight straight record quarters. That level of operational consistency provides more evidence that Nuuly, Free People and the broader five brand portfolio are resonating with customers across channels.
In terms of catalysts, the story still leans on Nuuly scaling into its newer logistics capacity, FP Movement store expansion, and AI driven merchandising that can help reduce markdowns. Cost risks around fuel surcharges and heavy FY27 capital expenditure near US$475 million are the counterbalance, since any cooling demand would make it harder to keep SG&A and gross margin where investors might want them.
Urban Outfitters' narrative points to revenue of US$7.9b and earnings of US$587.0 million by 2029, based on analyst models that assume revenue expands by 7.1% per year and earnings rise by about US$17.9 million from US$569.1 million today.
Uncover how Urban Outfitters' fair value indicates a 5% potential upside to its current price before a closing gap pulls that discount tighter.
Exploring Other Perspectives
Some of the lowest Urban Outfitters forecasts lean hard into fuel surcharge risk. Those analysts were pencilling in revenue of about US$7.6b and earnings near US$564.2 million by 2029, which is a much more cautious script. With the latest record quarter and BMO’s new coverage, you can now test how those pre news assumptions might evolve.
Explore 2 other Urban Outfitters fair value estimates, including one that suggests as much as 34% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Urban Outfitters research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Urban Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Urban Outfitters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Urban Outfitters?
Once you understand where Urban Outfitters fits in your watchlist, it can help to contrast it with very different types of opportunities surfaced through the Simply Wall St Screener.
- If you want potential growth with a small starting market value, review 11 elite penny stocks with strong financials that already show stronger balance sheets and income statements than many peers.
- If resilience matters more than excitement, scan a 32 resilient stocks with low risk scores that filters for businesses with lower risk scores and more robust fundamentals.
- If you prefer companies that rarely show up on front pages but still have solid metrics, check out a curated pool of 20 high quality undiscovered gems that combine quality indicators with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com