
3 Stocks Riding The AI Infrastructure Spending Wave In 2026
Global growth forecasts inching up to 3.1% for 2026, powered partly by AI-related investment, have turned the spotlight onto companies plugged into this capex wave. Investors face a mix of excitement and risk as heavy spending on chips, data centers, and energy collides with stickier inflation and higher yields. This article walks through three stocks exposed to these AI-linked tailwinds and explains why their stories might deserve a closer look now.
The three stocks discussed below are just a sample from this theme, and the full screen surfaced 53 more companies with equally compelling stories that are not covered here.
Head straight into the AI Infrastructure and Semiconductor Capex Beneficiaries screener to identify, compare, and analyze the AI infrastructure and semiconductor capex plays that best fit your own checklist.
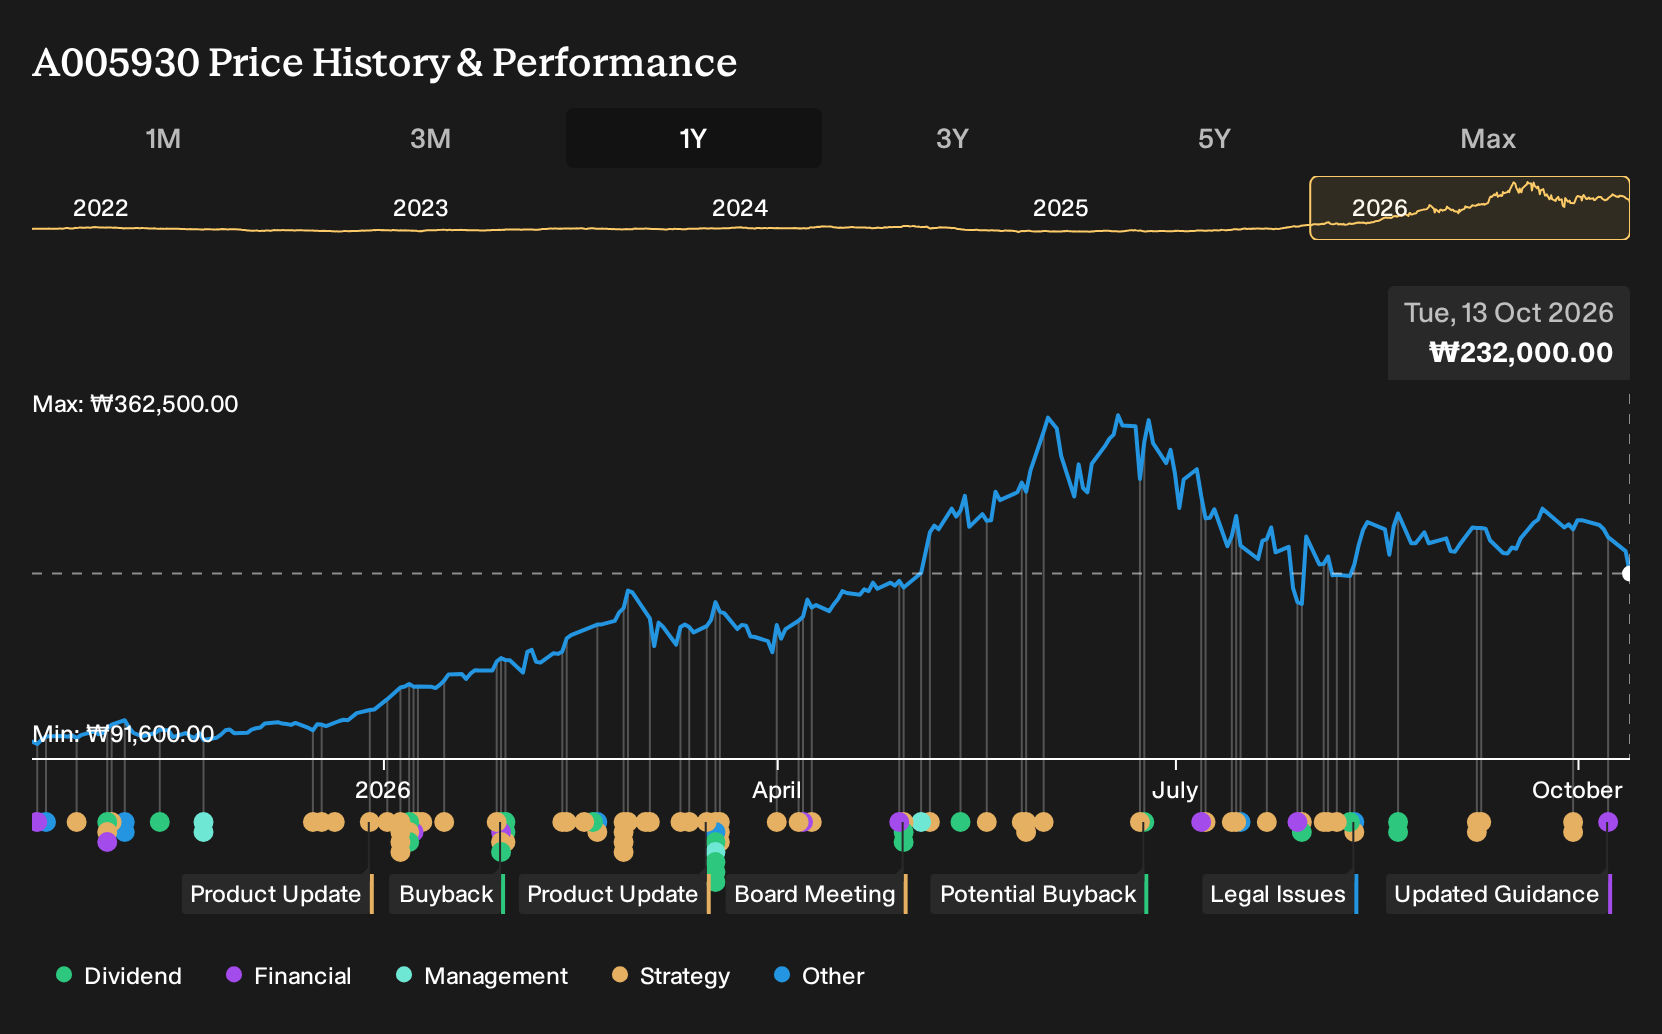
Samsung Electronics (KOSE:A005930)
Samsung Electronics is one of the clearest AI infrastructure stories in this screen, tying its huge chip operations directly to rising spend on advanced data centers, servers, and AI-enabled devices worldwide.
Samsung Electronics runs a broad hardware and components empire, yet its AI-linked Device Solutions segment is the revenue engine at about ₩286,354b, ahead of Device Experience on roughly ₩193,357b, with a market value near ₩1,477,397b anchoring its role in global semiconductor capex.
"However, due to recurring margin calls and KRW instability, the stock price fell by about 32% from its peak."
What really matters over the next phase of this AI capex cycle is how one subtle shift in demand mix ripples through memory pricing and profitability.
That pricing shift is exactly what the full narrative for Samsung Electronics unpacks, separating short term volatility from longer term AI capex potential and the risks that could still stall it.
STMicroelectronics (ENXTPA:STMPA)
STMicroelectronics ties directly into the AI infrastructure theme by supplying the power chips, sensors, and connectivity that keep data centers and edge devices running, which makes its progress on electrified transport and industrial customers particularly important right now.
STMicroelectronics generates most of its turnover from Analog, MEMS & Sensors at about $5.6b, Embedded Processing on roughly $4.1b, and Power and Discrete products near $1.7b, with RF and Optical Communications adding about $1.6b, underpinned by a market value around €39.1b.
"The accelerating adoption of electric vehicles and hybrid cars, especially STMicroelectronics' leadership in silicon carbide (SiC) and smart power solutions, is driving design wins and high-volume programs, positioning the company for significant future revenue growth and margin expansion as EV adoption rates recover and competition stabilizes."
What really moves the story from here is how one less visible shift in AI related hardware demand filters through pricing power and profitability.
That pricing power question is exactly where the full narrative for STMicroelectronics picks up. It lays out how AI demand, EV programs, and execution risks are really interacting under the surface.

Phison Electronics (TPEX:8299)
Phison Electronics plugs directly into the AI infrastructure theme through its flash controllers for SSDs and storage systems, which are essential for data center and high performance computing workloads. It currently generates about NT$149.8b from flash memory control chip design on a market cap near NT$435.6b.
Phison Electronics provides exposure to the AI build out through the storage layer, where controller know-how, relationships with NAND makers, and a growing enterprise footprint all matter more than headline chip capacity.
"Expansion into enterprise and automotive storage, both areas benefitting from the proliferation of AI/IoT, new design wins, and higher-value product shipments, are likely to gradually shift the revenue mix toward higher-margin categories, positively impacting net margins and long-term earnings potential."
What potentially changes the story is how one unresolved pressure on funding and balance sheet flexibility feeds through if AI capex cools faster than expected.
If that funding pressure is what worries you, the full narrative for Phison Electronics explains how Phison Electronics’ storage opportunity could still accelerate or stall from here.

Seeking Fresh Alternatives Before They Fly
Some themes are already in full breakout while others are just building momentum under the radar for now. Consider these fresh ideas before the window tightens and decide whether they fit your strategy.
- Target dependable income streams by scanning the 223 dividend fortresses that could keep paying while prices swing and sentiment keeps dropping.
- Spot early movers in automation by tracking the 91 robotics and automation stocks that may gain momentum as factories and warehouses race to upgrade.
- Review the 16 nuclear energy infrastructure stocks to explore opportunities related to the energy transition and changing power demand and supply dynamics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com