
What Hongkong Land Bulls Got Right
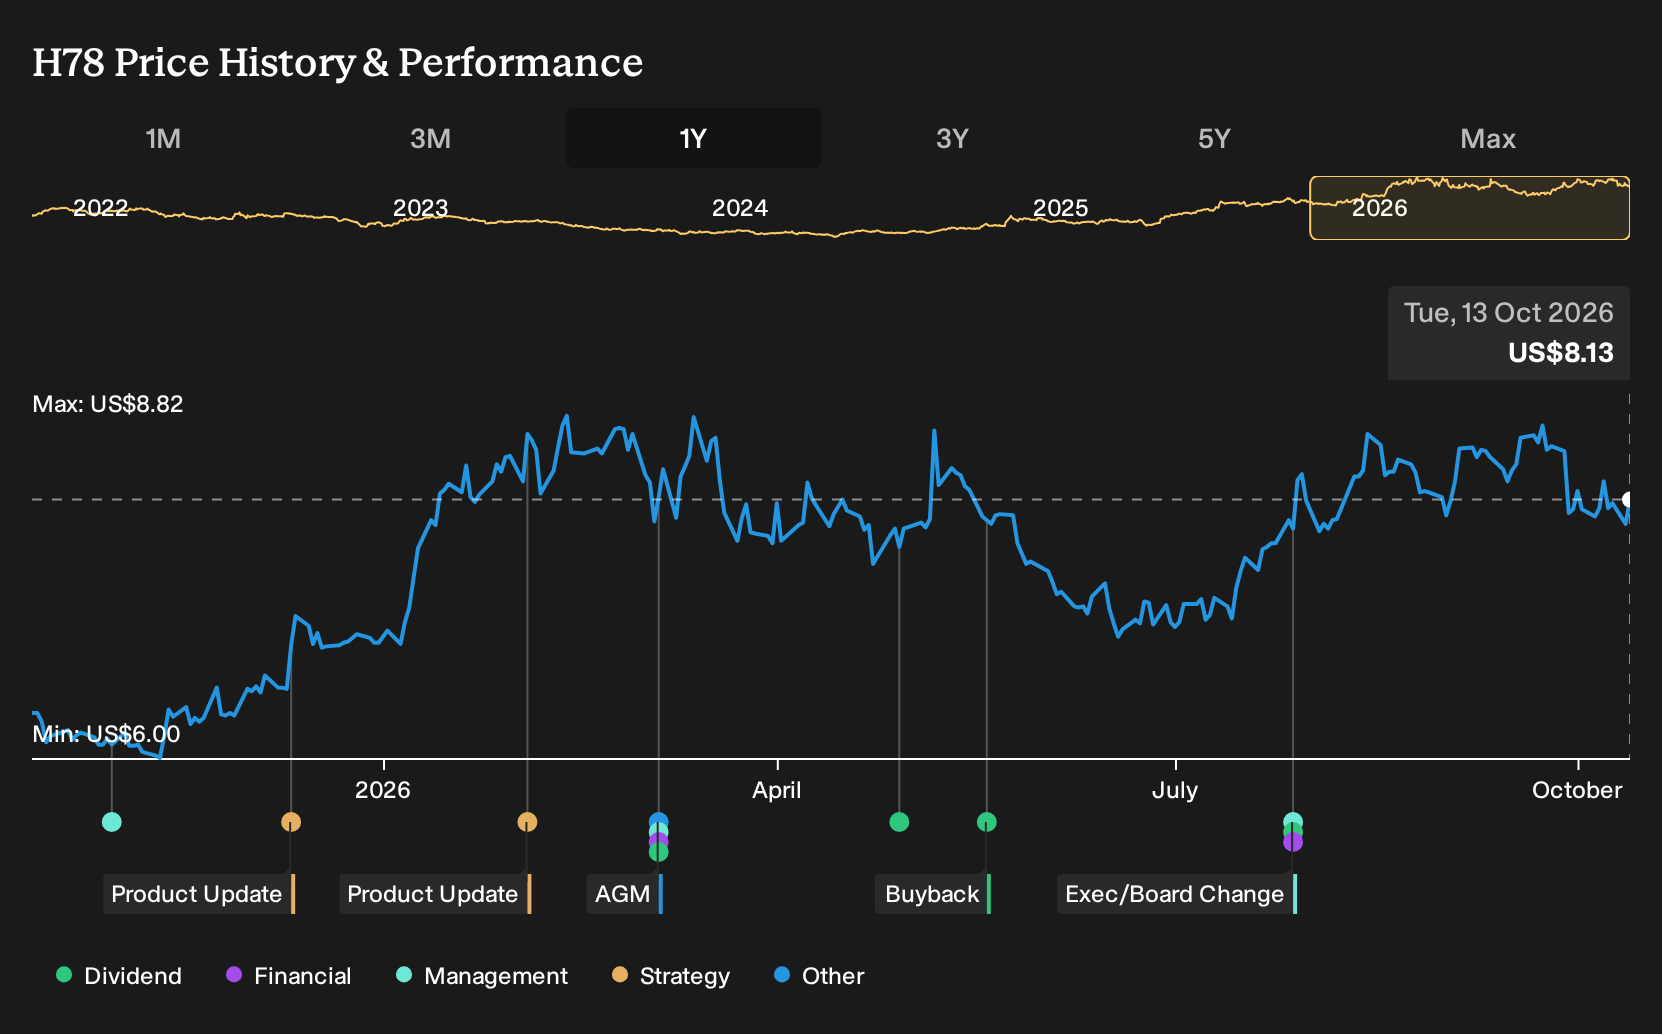
If Hongkong Land was on your watchlist rather than in your portfolio, the return may sting. Investors who held Hongkong Land over the past year are up 31.8%, including dividends. That result landed during a year when Jardine Matheson’s updated 2026 earnings guidance and Hongkong Land’s capital recycling plans were already public. The question now is whether disciplined buybacks and marquee asset repositioning were the key signals that its balance sheet and fund platform could support this kind of payoff.
If the move has made Hongkong Land harder to judge, start where the gap is still open and scan 185 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Hongkong Land
The shares cost US$6.37 at the start of the period, and anyone looking at Hongkong Land then had to decide which story felt more convincing.
The optimistic Narrative pointed to a Fair Value of US$6.86, a notional price based on expectations that revenue would grow 2.5% with profit margins near 47.9%. That view leaned on marquee projects like Tomorrow's CENTRAL and an expanding Asian footprint to support earnings and asset values.
The pessimistic Narrative instead used a Fair Value of US$4.88, built on assumptions that revenue would decline 12.3% even if margins reached 73.0%. This case focused on lasting shifts toward remote work, weaker premium office demand in Central, and pressure on long term rental yields.
What The Results Changed For Hongkong Land
The clearest data point came from Hongkong Land’s H1 2026 report, where revenue fell to US$632.7 million while net income excluding extra items rose to US$1,259.5 million. Multiple mid 2026 buybacks and immediate cancellations gave the optimistic case fresh support around capital management, although weaker top line trends kept the overall evidence mixed rather than decisive.
The useful takeaway is simple. When a property group leans on capital recycling and funds, track three things separately: the revenue line, the recurring profit, and how aggressively the board is shrinking the share count.
What Hongkong Land's Price Now Assumes
With Hongkong Land at US$8.13 today, the selected Narrative still places its Fair Value above the current quote rather than fully aligned with it. That view leans on disciplined capital recycling, marquee project repositioning, and the build out of a fee based fund platform.
On that reading, a buyer at today’s price is effectively assuming sustained execution on asset sales, share count reduction, and income growth from high quality Asian developments that the market has not yet fully credited.
"Ongoing capital recycling, including high-profile sales like the HKEX Exchange Square transaction at book value, combined with an active share buyback program and targeted debt reduction, is likely to boost EPS and net asset value per share over the medium term, supporting long-term value creation and earnings growth."
The price and this Narrative do not agree. → Uncover what this Narrative says Hongkong Land is actually worth
Hongkong Land And Data Hunger
Hongkong Land lives in bricks and leases. Your watchlist probably does too.
Behind that physical world sits a different kind of infrastructure. Real estate players increasingly lean on detailed data and online marketplaces to decide where to deploy capital.
One business focuses on that digital plumbing. It gathers property information, tracks leasing and sales activity, and runs portals where buildings and land are marketed.
Those tools let owners, lenders and brokers benchmark performance, manage risk and reach buyers more efficiently.
As more decisions shift into software, power in real estate does not just sit with landlords. It also sits with whoever runs the datasets and marketplaces they rely on.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 24% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com