
3 Value Stocks for a Higher Bond Yield World
Higher for longer bond yields have turned into the market’s main plot twist, not just background noise. Rising government borrowing costs are reshaping what investors are willing to pay for future profits, which can punish some shares and quietly reward others. This article walks through that shift and reveals 3 value stocks exposed to this new rate reality, helping you decide which stories deserve a closer look.
The three stocks covered in this piece are a small sample of what higher-for-longer yields can mean for value opportunities, and the same screen surfaced 48 more companies with similarly solid stories that are not included here.
If you want to move quickly from idea to watchlist and sort through those extra candidates by sector, yield and valuation, head straight to the Value stocks in developed markets benefiting from higher-for-longer bond yields screener.
Siemens (XTRA:SIE)
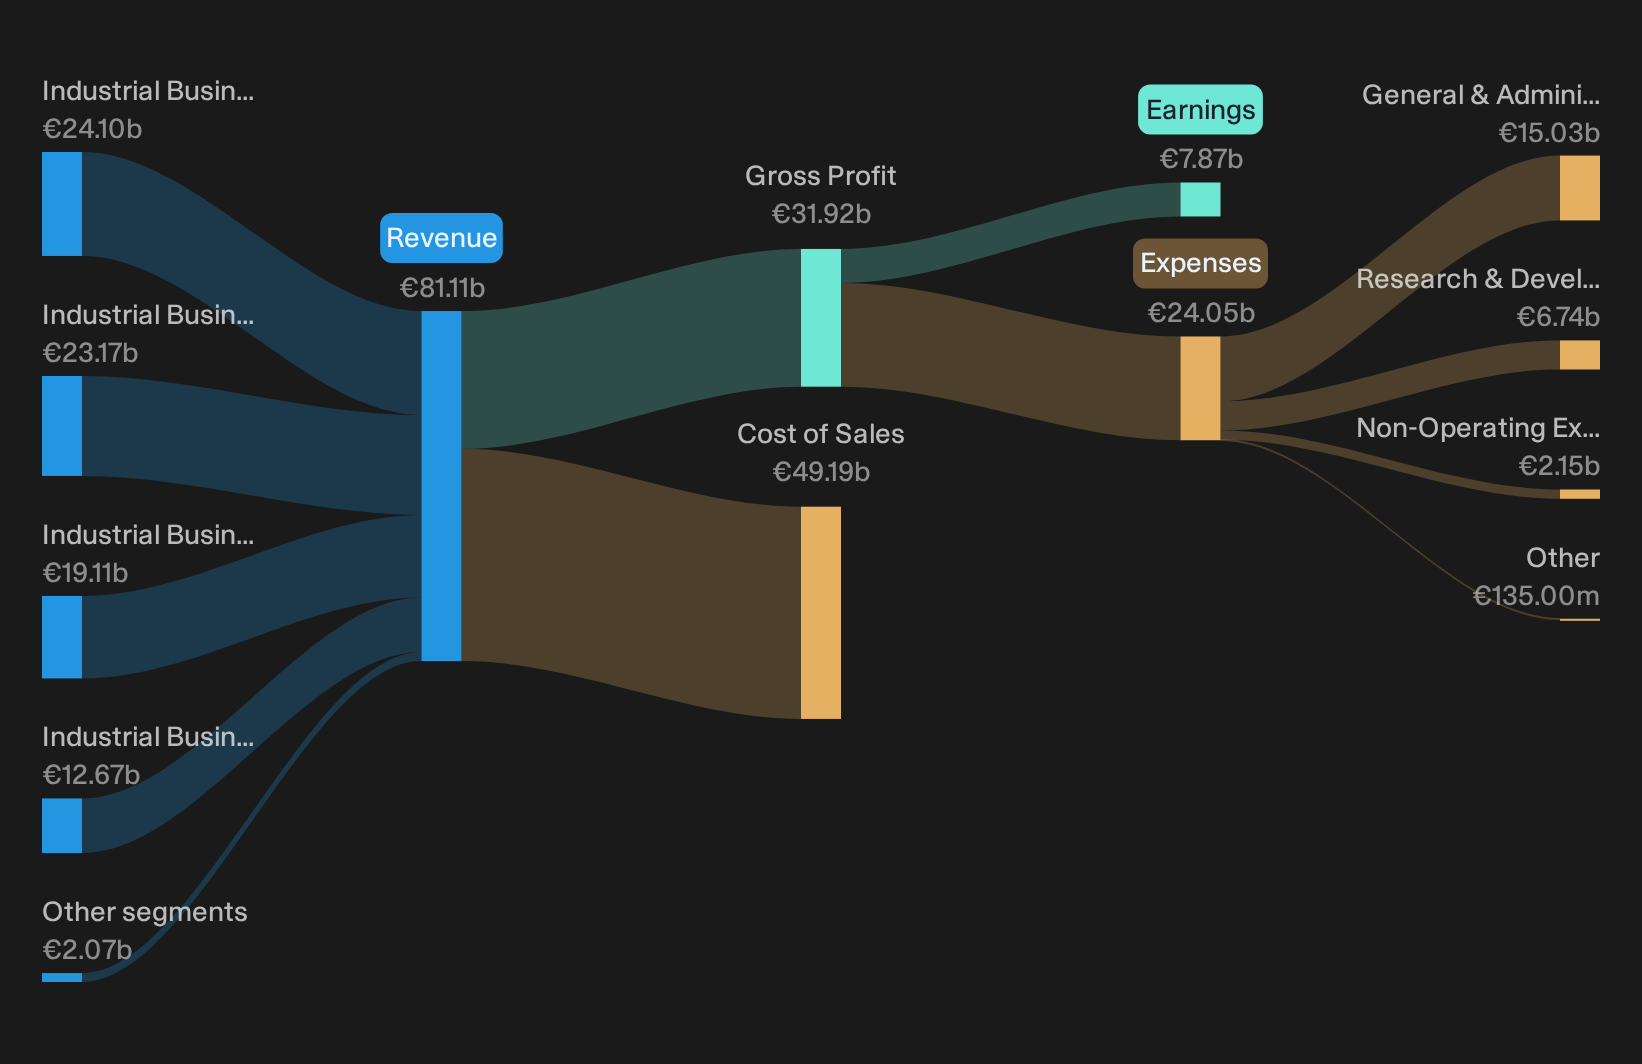
Siemens is a €210.7b industrial and automation heavyweight in the value-tilted bucket of this screener, with earnings linked to global capital spending rather than long-duration growth stories.
Its largest revenue engines are Smart Infrastructure at €24.1b, Siemens Healthineers at €23.2b, Digital Industries at €19.1b and Mobility at €12.7b, supported by smaller contributions from Siemens Financial Services.
"Siemens today does not merely sell machines; it sells decision-making capability through digital twins, simulation, and AI-driven optimization."
What really matters for Siemens now is how one quiet shift in its mix could ripple through future margins and cash generation.
To see how that mix shift could accelerate or stall Siemens cash generation, read the full narrative for Siemens to see what the headline numbers may be masking.
Glencore (LSE:GLEN)
Glencore brings a different flavour of value to this higher-for-longer yield theme, tying cash-generative commodity production and trading to real-world demand for energy and metals rather than distant growth promises.
"A significant uplift in copper production volumes is expected in the second half of 2025 and beyond, with a clear pathway to 1 million tonnes of annual copper by 2028 and new low-capex, high-return projects in Argentina progressing, which is intended to support sustained, long-term revenue and EBITDA growth in alignment with continued global electrification and EV adoption."
What really matters now is how one quiet shift in Glencore’s capital return mix interacts with that growth path if higher yields persist.
That capital return mix is the real hinge for Glencore now, and the full narrative for Glencore maps how volumes, payouts and risk could be quietly decoupling.

Archer-Daniels-Midland (ADM)
Archer-Daniels-Midland links higher-for-longer yields to the real economy by turning crop flows, oilseeds and nutrition ingredients into cash-generative, asset-backed earnings that fit this value-tilted screener theme.
ADM generated about US$65.3b from Ag Services and Oilseeds, US$11.5b from Carbohydrate Solutions, US$7.5b from Nutrition and US$455 million from Other activities, with intersegment eliminations of US$2.6b, and the group is valued at roughly US$38.8b.
Policy clarity and government support for biofuels, including the 45Z production tax credit that Archer-Daniels-Midland now expects to contribute about US$250 million in 2026, together with favorable blending mandates and domestic feedstock incentives, are expected to support crush economics and contribute to revenue and earnings.
The key consideration for Archer-Daniels-Midland is how a gradual, mix-driven shift in its higher-margin nutrition and processing earnings may reshape future profitability.
That mix shift is the real tension point now, and the full narrative for Archer-Daniels-Midland shows how Archer-Daniels-Midland’s cash engine and valuation story could be quietly accelerating.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is flying, early entry points can be gone. Scan these under the radar for now opportunities while it matters and act now.
- Target reliable income streams before yields get caught dropping by checking out 223 dividend fortresses built for investors who want payouts backed by balance sheet strength.
- Spot early compounders with room to run by reviewing 185 high quality undervalued stocks curated for quality businesses where cash generation and fundamentals do the heavy lifting.
- Track secular demand for critical metals by screening 16 top copper producer stocks focused on producers tied to long-term infrastructure and electrification trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com