
Experian (LSE:EXPN) Could Be 27% Undervalued On Its Mortgage Tool Update
Experian (LSE:EXPN) is back in focus after updating its Power Profile Plus for Mortgage tool, which now gives lenders soft inquiry access to full credit files and unlimited follow up checks without additional Experian credit profile charges.
Those mortgage upgrades come after a busy few weeks for Experian, including the launch of its Cashflow Data Bureau and new partnerships around Agent Trust. However, the share price tells a cooler story, with a 7-day share price return of 8.99% but a year-to-date share price decline of 18.13% and a 1-year total shareholder return that is down 21.41%, suggesting recent momentum has not yet reversed the longer term drag.
Spot other credit and data leaders that could be setting up their next move by scanning our hand picked list of solid balance sheet and fundamentals (9 results).After that sharp 7 day rebound, the question now is whether Experian’s recent product work still leaves meaningful upside on the table, or if the easier gains are already in the rear view mirror as valuation comes under the microscope.
Most Popular Narrative: 27% Undervalued
Against Experian's last close at £27.28, the most followed narrative points to a fair value of £37.39, which implies a sizeable gap that hinges on execution, product uptake and the durability of its data and analytics edge.
The company is leveraging innovation and integrated platforms, notably the Ascend platform, to drive automation, client solutions, and efficiencies. This is likely supporting ongoing growth in revenue and improving net margins through enhanced service delivery. In Consumer Services, ongoing product ecosystem expansion and increased membership are driving strong revenue growth, particularly in high-margin areas like insurance and premium services, enhancing future earnings potential.
See why 32 investors see Experian as 27% undervalued.
According to this narrative, that £37.39 fair value is built on revenue growth assumptions of roughly 8% a year, profit margins rising from 17.8% to 19.3%, and a discount rate of 8.04%. It also leans on a view that Experian can sustain a high future P/E of 26.4x and keep improving returns on equity, while absorbing risks like softer Latin America B2B conditions and currency swings in Brazil.
Result: Fair Value of £37.39 (UNDERVALUED)
Still, the bullish Experian narrative quickly runs into trouble if Latin America B2B activity stays muted or if currency swings in Brazil keep chipping away at reported growth.
Find out about the key risks to this Experian narrative.
Another View: Experian Through The P/E Lens
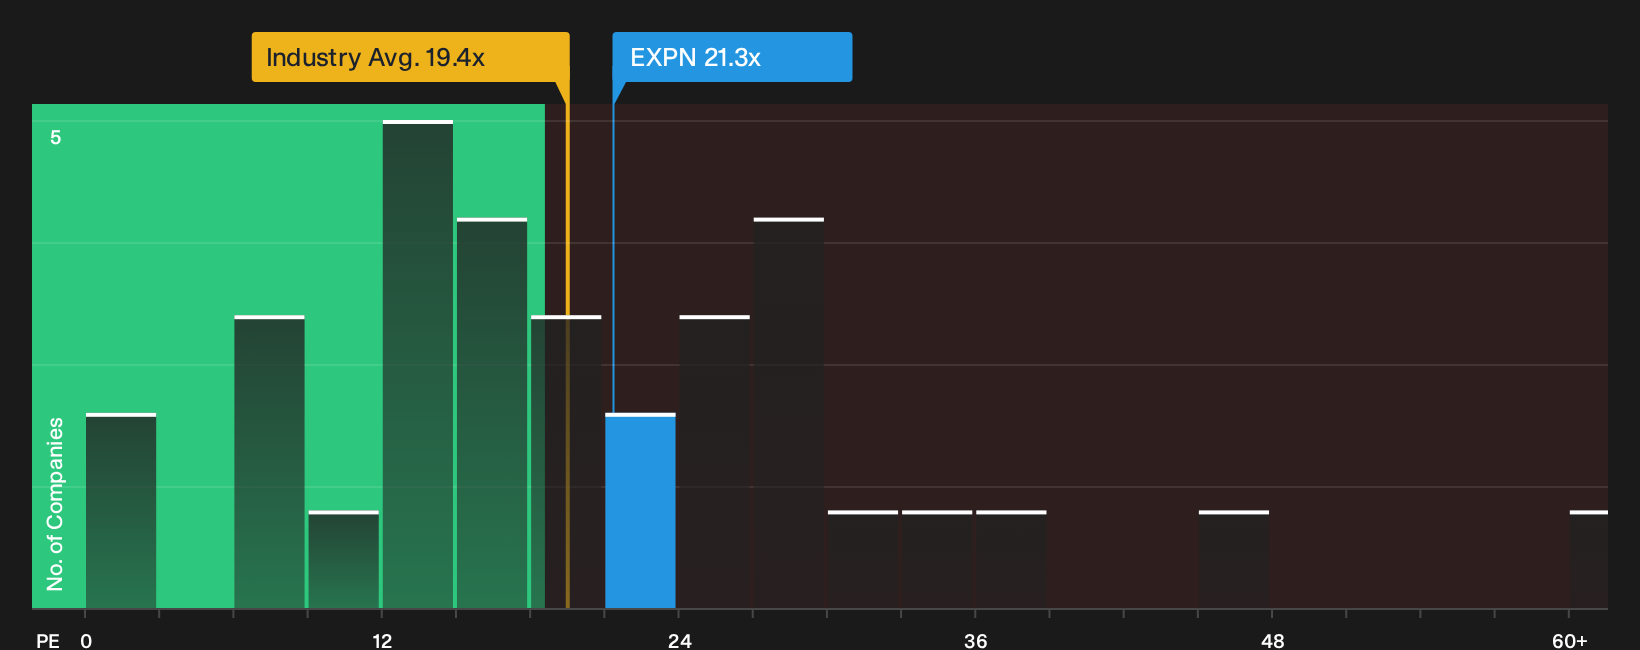
The discounted cash flow narrative points to Experian being cheap against a £37.39 fair value. The P/E story is less generous. At 21.3x earnings, the stock trades above both the UK Professional Services group on 19.4x and its peer average of 20.4x.
Yet that same 21.3x P/E remains well below an estimated fair ratio of 30.3x, which indicates the market could move toward a richer multiple if earnings continue to support the story. For anyone weighing these competing signals, the question is whether Experian is a value idea in disguise or simply a quality business at a full price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Experian story so far. If you want to move fast and reach your own verdict based on the underlying risk and reward balance, start by weighing the 4 key rewards and 1 important warning sign
Looking for more Experian sized opportunities?
If Experian has sharpened your focus on quality and pricing power, now is the moment to broaden your watchlist with fresh, data driven ideas.
- Target high quality companies that look mispriced on fundamentals by scanning our hand picked 8 high quality undervalued stocks.
- Review a shortlist of yield focused picks through the 2 dividend fortresses to explore potential income streams.
- Strengthen your downside protection by zeroing in on resilient businesses using the 4 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com