
Power Solutions International (PSIX) Could Be 24% Undervalued On Its New $220 Million Credit Facility
Power Solutions International (PSIX) has just reshaped its financing toolkit by securing a new revolving credit facility with up to $220 million of committed capacity and a longer maturity, while paying off its prior agreement.
Recent trading suggests investors are reassessing Power Solutions International. The stock has a 30 day share price return of 26.2% and a 90 day gain of 58.8%. However, the year to date share price return is still down 13.6% and the 1 year total shareholder return has declined 42.2%, while the very large 3 year and 5 year total shareholder returns point to a long run story that has already been powerful.
Scan how Power Solutions International compares with other balance sheet focused plays by reviewing our curated list of solid balance sheet and fundamentals (25 results) in the same financing sweet spot.
Bulls argue that Power Solutions International’s fresh credit headroom and profit growth metrics back up the share price jump. Bears see a volatile track record that still matters. Which side does the current valuation reward?
Most Popular Narrative: 24% Undervalued
Against the last close of $53.14, the most followed narrative around Power Solutions International points to a fair value of $70.37. This frames the recent share price rebound as only a partial catch up to that narrative view.
Vertical integration through the MTL acquisition, including welding, fabrication and UL certified components and fuel tanks, is aimed at shortening lead times and stabilizing supply for data center related products. This can support revenue conversion and gross margin resilience.
See why 9 investors see Power Solutions International as 24% undervalued.
Result: Fair Value of $70.37 (UNDERVALUED)
Still, any prolonged softness in higher margin oil and gas demand, or further delays on large power system orders, could quickly test that 24% undervalued narrative for Power Solutions International.
Find out about the key risks to this Power Solutions International narrative.
Another View: Cash Flows Point To A Different Fair Value
Price anchors for Power Solutions International do not all line up. While the popular narrative leans on a $70.37 fair value, Simply Wall St's DCF model points to a future cash flow value of $49.30, which is below the current $53.14 share price and implies PSIX screens as slightly overvalued on this lens.
That kind of gap between a DCF output and a narrative driven target price raises a practical question for investors: Which set of assumptions feels more realistic when you look at your own expectations for order timing, margins and reinvestment needs over the next few years.
Look into how the SWS DCF model arrives at its fair value.
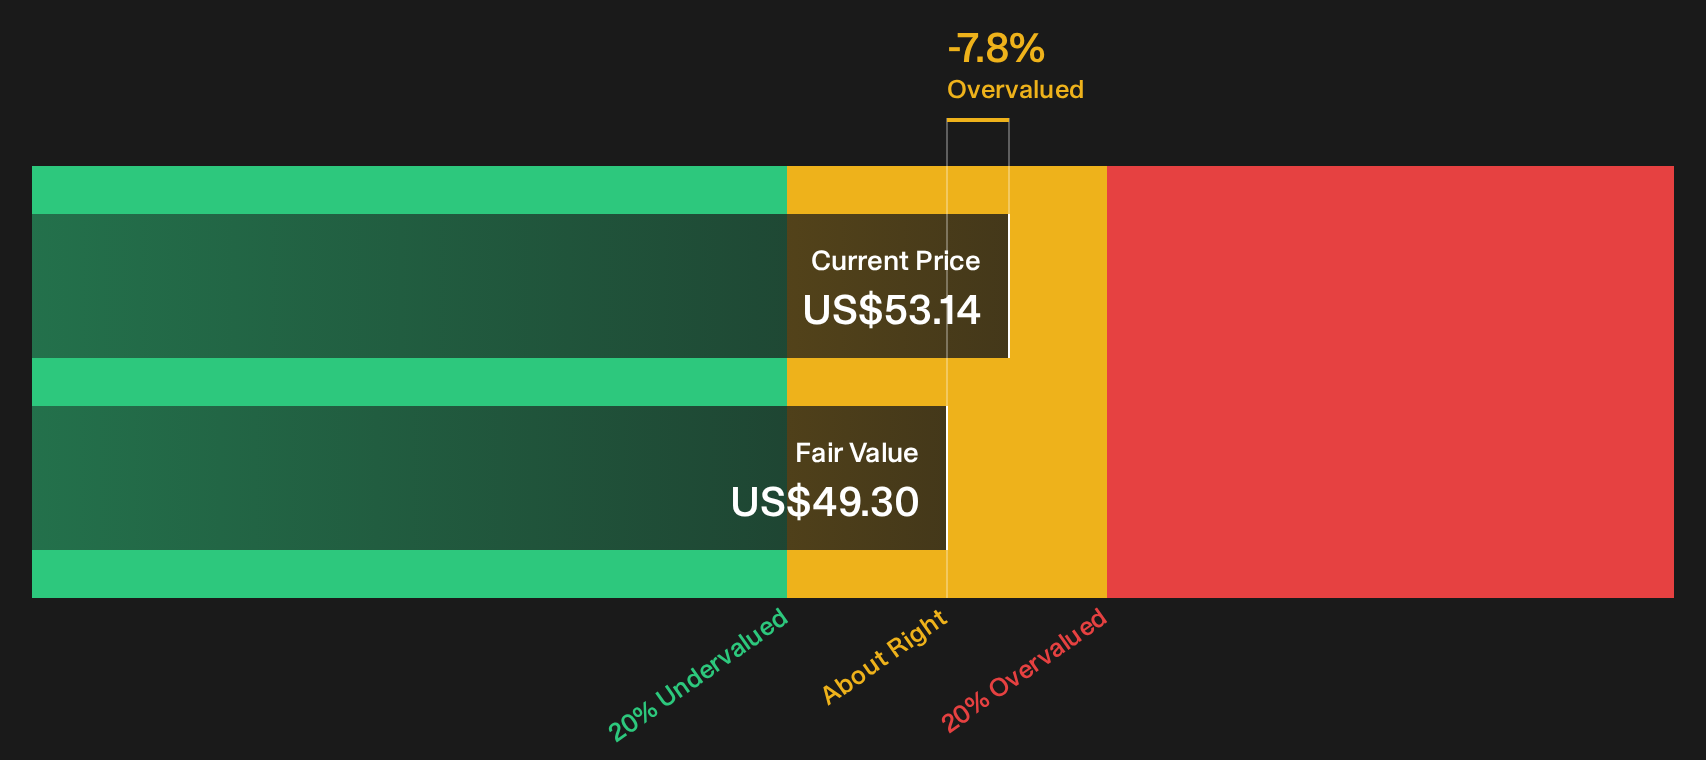
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Power Solutions International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Power Solutions International is clearly split, so treat that tension as a prompt to move fast. Review the full picture and decide where you stand using the 4 key rewards and 2 important warning signs.
Looking for more Power Solutions International sized ideas?
Do not stop with Power Solutions International. Use fresh screeners to spot other opportunities that fit your style before the crowd gets there first.
- Target potential mispricing by scanning a curated set of high quality opportunities through the 32 high quality undervalued stocks.
- Protect your downside first by sorting companies with resilient profiles using the 32 resilient stocks with low risk scores.
- Spot tomorrow's potential leaders early by working through a focused pool of overlooked prospects using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com