
Did Activist Stake Building Just Shift Unite Group's (LSE:UTG) Investment Narrative?
- Achilles Investment Company has built an 11.3% stake in Unite Group and is preparing a fresh activist campaign focused on capital recycling, cash flow timing, and perceived undervaluation in a student accommodation market that faces oversupply pockets and affordability strain.
- The activist interest is sharpening attention on Unite Group's underlying rental income, occupancy resilience, and how management allocates capital in a sector where some assets have recently faced revenue pressure and losses.
- The focus now turns to how Unite Group's investment narrative could be reshaped by Achilles' activist stake and its push on valuation.
Unite Group Investment Narrative Recap
To own Unite Group, you need to believe purpose built student accommodation remains supported by student demand and tight supply in key university cities, even as more UK students choose to live at home and commute. The real test in the next year is simple: can Unite keep beds filled at sensible rents where local oversupply and affordability pressure are already biting?
The fresh spotlight from Achilles does not change that core operational question. It mainly sharpens scrutiny on how quickly underperforming assets are recycled and how new projects are funded when debt and maintenance spending already weigh on cash generation. The biggest present risk is that higher leverage and interest cost squeeze flexibility just as regional markets soften.
The most relevant angle from recent coverage is Achilles highlighting Unite Group as undervalued and focused on capital recycling and future cash flows. That intersects directly with the key short term catalyst, which is whether rental income and occupancy can stabilise enough for management to execute refurbishments and developments without stretching the balance sheet further.
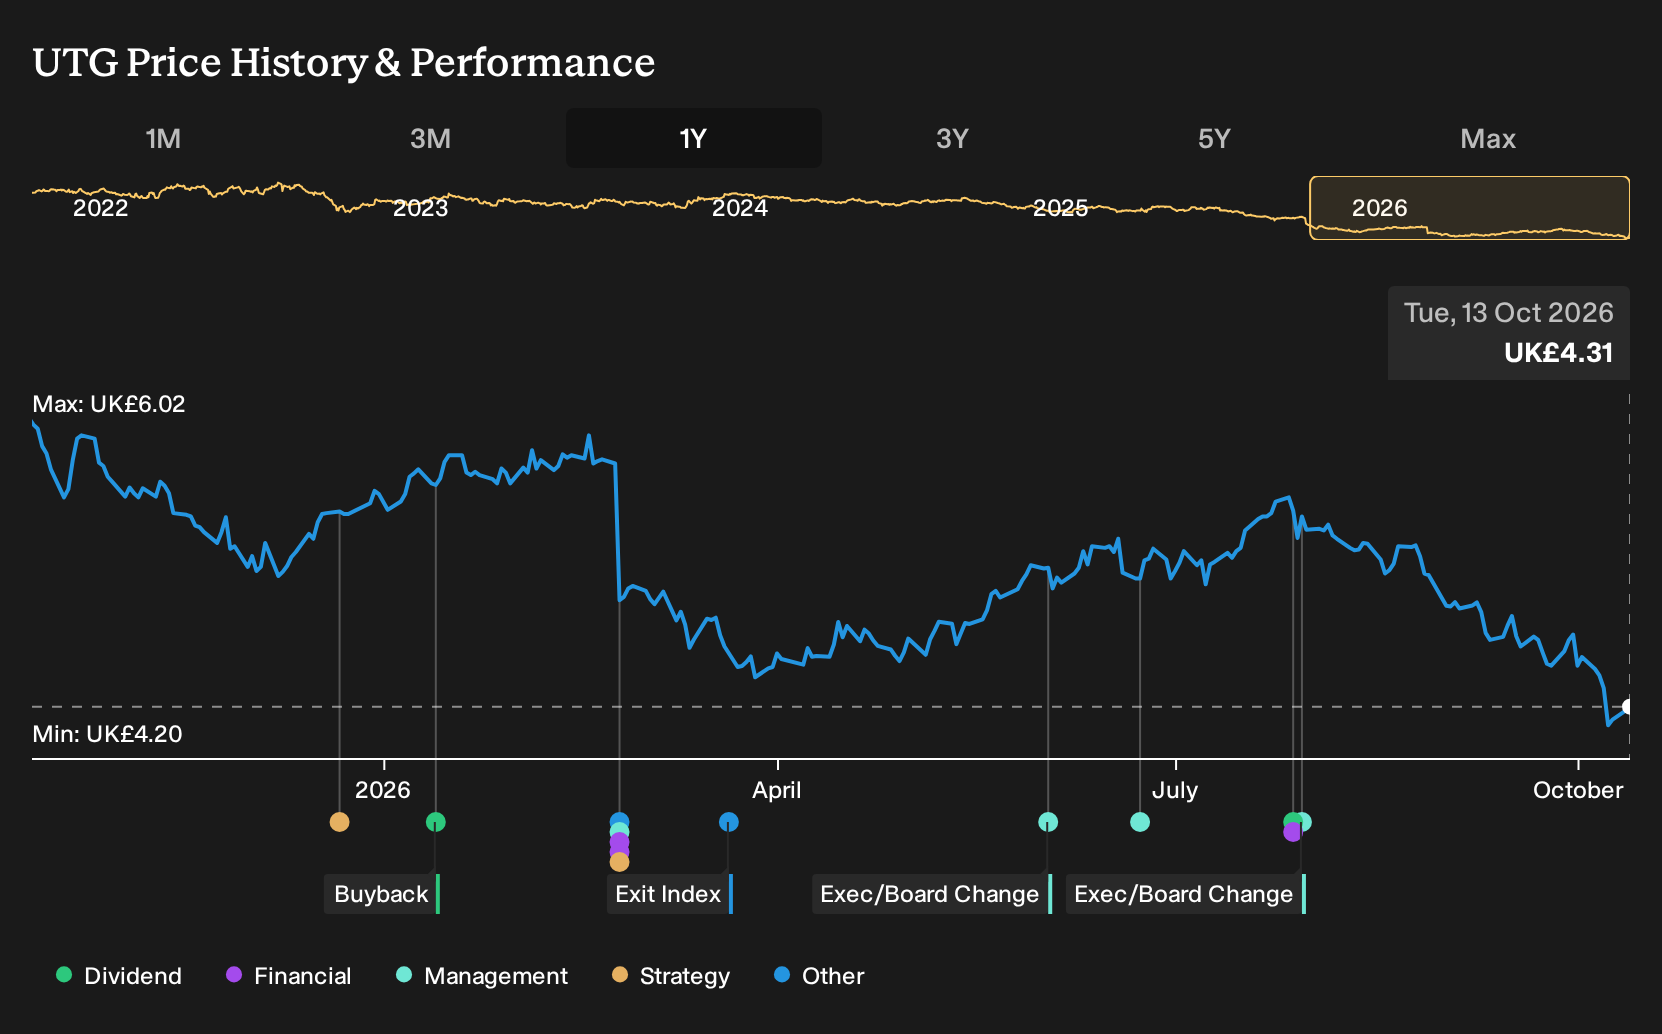
This activist attention lands after a difficult share price period and a reported revenue decline alongside a large loss of £506.2m. Analysts still expect earnings to grow and forecast profitability within three years, although revenue is expected to trend lower. For you, the operational question is whether Unite can convert any improvement in earnings into healthier cash coverage of debt and dividends.
Unite Group's current revenue outlook assumes 9.3% yearly revenue growth, with analysts expecting revenues of £463.8 million and earnings of £446.2 million by 2028. That implies earnings rising by about £99.9 million from £346.3 million today to the forecast consensus level.
Uncover why Unite Group's fair value indicates a 118% potential upside to its current price, a discount that could narrow quickly if expectations are met.
Exploring Other Perspectives
Simply Wall St Community members have only three fair value estimates for Unite Group so far, ranging from £5.54 to £9.40, so views are already wide even before Achilles' renewed activism and recent analyst optimism are factored in. Opinion could diverge further if student demand, local oversupply and debt costs change in unexpected ways, so consider multiple viewpoints before forming your own conviction.
Explore 2 other Unite Group fair value estimates, including one that suggests it could be worth just £5.54!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Unite Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Unite Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unite Group's overall financial health at a glance.
Looking for more investment ideas beyond Unite Group?
Once you have a view on Unite Group, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want growth potential without stretching quality, scan a curated set of stronger balance sheets and fundamentals with our list of solid balance sheet and fundamentals (9 results).
- If you care most about income resilience, weigh Unite Group against other companies offering higher yields and robust payout histories by checking the 2 dividend fortresses.
- Prefer stocks that the market may not be fully focused on yet, but where the financials already look compelling, filter for a 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com