
JOYY (JOYY) Just Gave Investors Something To Think About
BIGO Ads, under JOYY (NasdaqGS:JOYY), has rolled out its advertising SDK through Google AdMob mediation, giving app developers direct access to multiple ad formats and broader premium traffic for monetization.
Against this product backdrop, JOYY’s recent share price performance has been strong. The stock is at US$82.53 with a 30-day share price return of 6.82%, building on a 90-day gain of 16.37% and a 27.48% year-to-date move. The 1-year total shareholder return of 59.14% and 3-year total shareholder return of 134.48% point to momentum that has extended well beyond the latest BIGO Ads announcement.
Scan other ad driven growth stories on Simply Wall St by reviewing the hand picked 92 AI infrastructure stocks that, like JOYY, sit at the crossroads of user traffic and monetization technology.
JOYY has already rewarded holders with strong multi period returns at US$82.53. The real tension now is whether that recent strength still leaves enough upside for new buyers once valuation is taken into account.
Most Popular Narrative: 6% Undervalued
JOYY last closed at $82.53, while the most followed narrative pegs fair value at $88.01. This leaves a modest valuation gap that hinges on how its mix shift and capital return story play out.
Management is focusing on high-quality operations and disciplined cost control, leading to a significant improvement in non-GAAP operating income (+27.9% YoY) and net margins. Gross margin improvements are driven by higher-margin non-livestreaming revenues and steady cost discipline, which could support long-term earnings growth.
See why 5 investors see JOYY as 6% undervalued.
Result: Fair Value of $88.01 (UNDERVALUED)
Still, if JOYY underdelivers on expected user growth or faces higher compliance costs across key regions, that could quickly challenge the current valuation narrative.
Find out about the key risks to this JOYY narrative.
Another View: What JOYY’s Sales Multiple Is Telling You
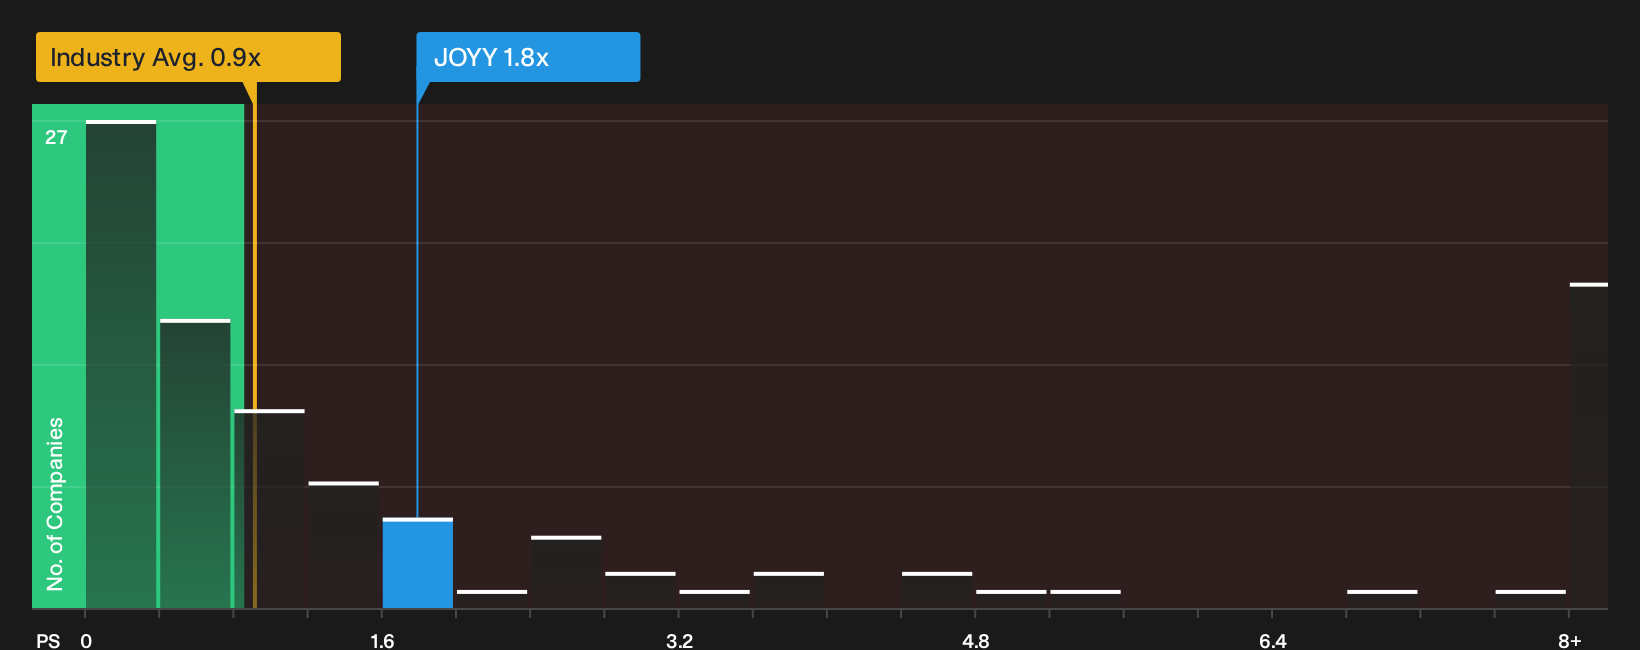
Analysts lean on a detailed earnings model to argue JOYY looks about 6% undervalued at a fair value of $88.01. The P/S ratio paints a different picture. At 1.8x sales, the stock trades above both the US Interactive Media and Services average of 0.9x and its own fair ratio of 1.3x, which suggests less room for error if growth or margins disappoint.
When one framework points to upside and another flags a richer P/S tag than the wider industry and the fair ratio, which signal should carry more weight in your process See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on JOYY’s value and risk profile can cut both ways, so move quickly, review the underlying data, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond JOYY?
If JOYY has your attention, do not stop there. Build a stronger watchlist by lining up other potential ideas before the next wave of earnings resets expectations.
- Target potential mispricing by scanning companies that screen as 32 high quality undervalued stocks based on cash flows and balance sheet quality.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and unexpected slowdowns.
- Go hunting for future leaders by checking out 20 high quality undiscovered gems before they attract wider market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com