
Why Did Skyworks Solutions (SWKS) Move Today?
Skyworks Solutions (SWKS) has just completed large exchange offers tied to Qorvo bonds, issuing new senior notes that reshape its debt profile. For shareholders, this refinancing move now sits alongside recent index removals.
Recent moves around Skyworks Solutions have been choppy. The share price closed at US$76.56 and has climbed 33.12% over the past 90 days, even though the 30-day share price return is down 13.34% and the 7-day return is down 7.53% as investors digest the index removals, Qorvo integration and fresh debt issuance. That leaves momentum improving in the short term, while the 1-year total shareholder return of 8.62% and 5-year total shareholder return, which declined 46.49%, indicate a recovery that is still rebuilding after a tough multi-year stretch.
Scan how other chipmakers with active refinancing and product launches are setting up for their next move by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) around Skyworks Solutions.
After a 90 day rebound in Skyworks Solutions followed by fresh selling on index cuts and new debt, the puzzle is simple: Does the current valuation still leave more upside than downside for new buyers?
Most Popular Narrative: 10% Overvalued
Skyworks Solutions last closed at $76.56 while the most followed narrative anchors fair value at $69.82, so the story hinges on whether merger execution and RF content gains can justify that premium.
The planned Qorvo merger is framed around creating a combined mobile business of roughly US$5.5b and a non mobile business of about US$2.5b to US$2.6b, together with at least US$500m of cost synergies over 24 to 36 months and a long term model of 50% to 55% gross margin and 30% to 35% operating margin. This could materially lift net margins and earnings power that current pricing may assume will be delivered in full.
See why 55 investors see Skyworks Solutions as 10% overvalued.
Result: Fair Value of $69.82 (OVERVALUED)
Still, two pressure points could quickly flip this Skyworks Solutions story. Execution setbacks on the Qorvo merger, or prolonged smartphone demand weakness, would challenge the upbeat synergy narrative.
Find out about the key risks to this Skyworks Solutions narrative.
Another Angle On Skyworks Solutions Valuation
The analyst narrative pins fair value for Skyworks Solutions at $69.82 and tags the stock as overvalued. A second lens tells a very different story. The SWS DCF model estimates future cash flows are worth $166.80 per share, which would frame the same $76.56 price as materially undervalued. Which signal do you trust more, a story built on earnings multiples or one anchored in long term cash flows?
For readers who want to see how that cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
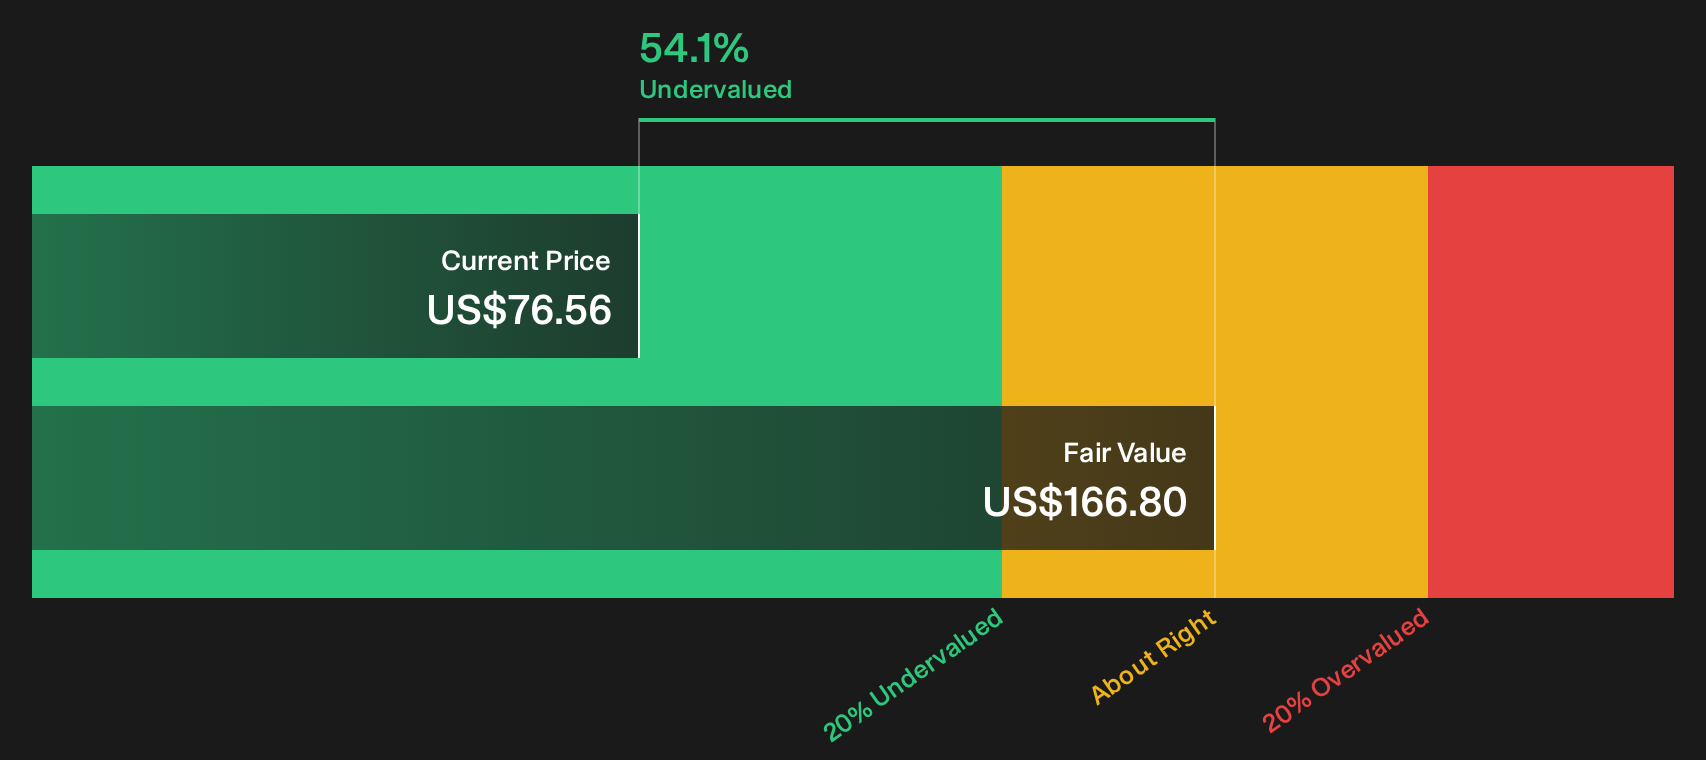
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Skyworks Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The tension between upside and risk around Skyworks Solutions is clear. Move quickly and test the numbers yourself against your own judgment. To see where investors currently flag both the bright spots and the pressure points, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Skyworks Solutions?
If the Skyworks Solutions story has you thinking harder about risk and reward, do not stop here. Broaden your watchlist now, or you risk missing opportunities.
- Target resilient performance by scanning a 32 resilient stocks with low risk scores that aims to keep volatility and downside pressures in better check.
- Hunt for strong cash generators using a 32 high quality undervalued stocks that blends quality fundamentals with pricing that still looks reasonable.
- Lock in potential income streams by reviewing a 8 dividend fortresses that focuses on higher yields backed by sturdier balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com