
Wells Fargo (WFC) Q3 Results Show Resilient Consumer Spending Holding Up
- Wells Fargo (NYSE:WFC) reported third quarter results that management said reflect resilient U.S. consumer spending and financial stability.
- CEO commentary highlighted rising deposits across key segments alongside what the bank described as healthy loan performance and low credit losses.
- The lender acknowledged revenue and net interest income misses for the quarter while pointing to stable consumer behavior as a key support.
- Wells Fargo's third quarter consumer resilience story, including stronger deposits and solid credit quality, only shows part of the picture. We have also spotted 1 warning sign worth knowing about at Wells Fargo.
This is far from the only large bank exposed to the theme of resilient consumers supporting earnings, so broaden your watchlist with 39 profitable AI stocks that aren't just burning cash.
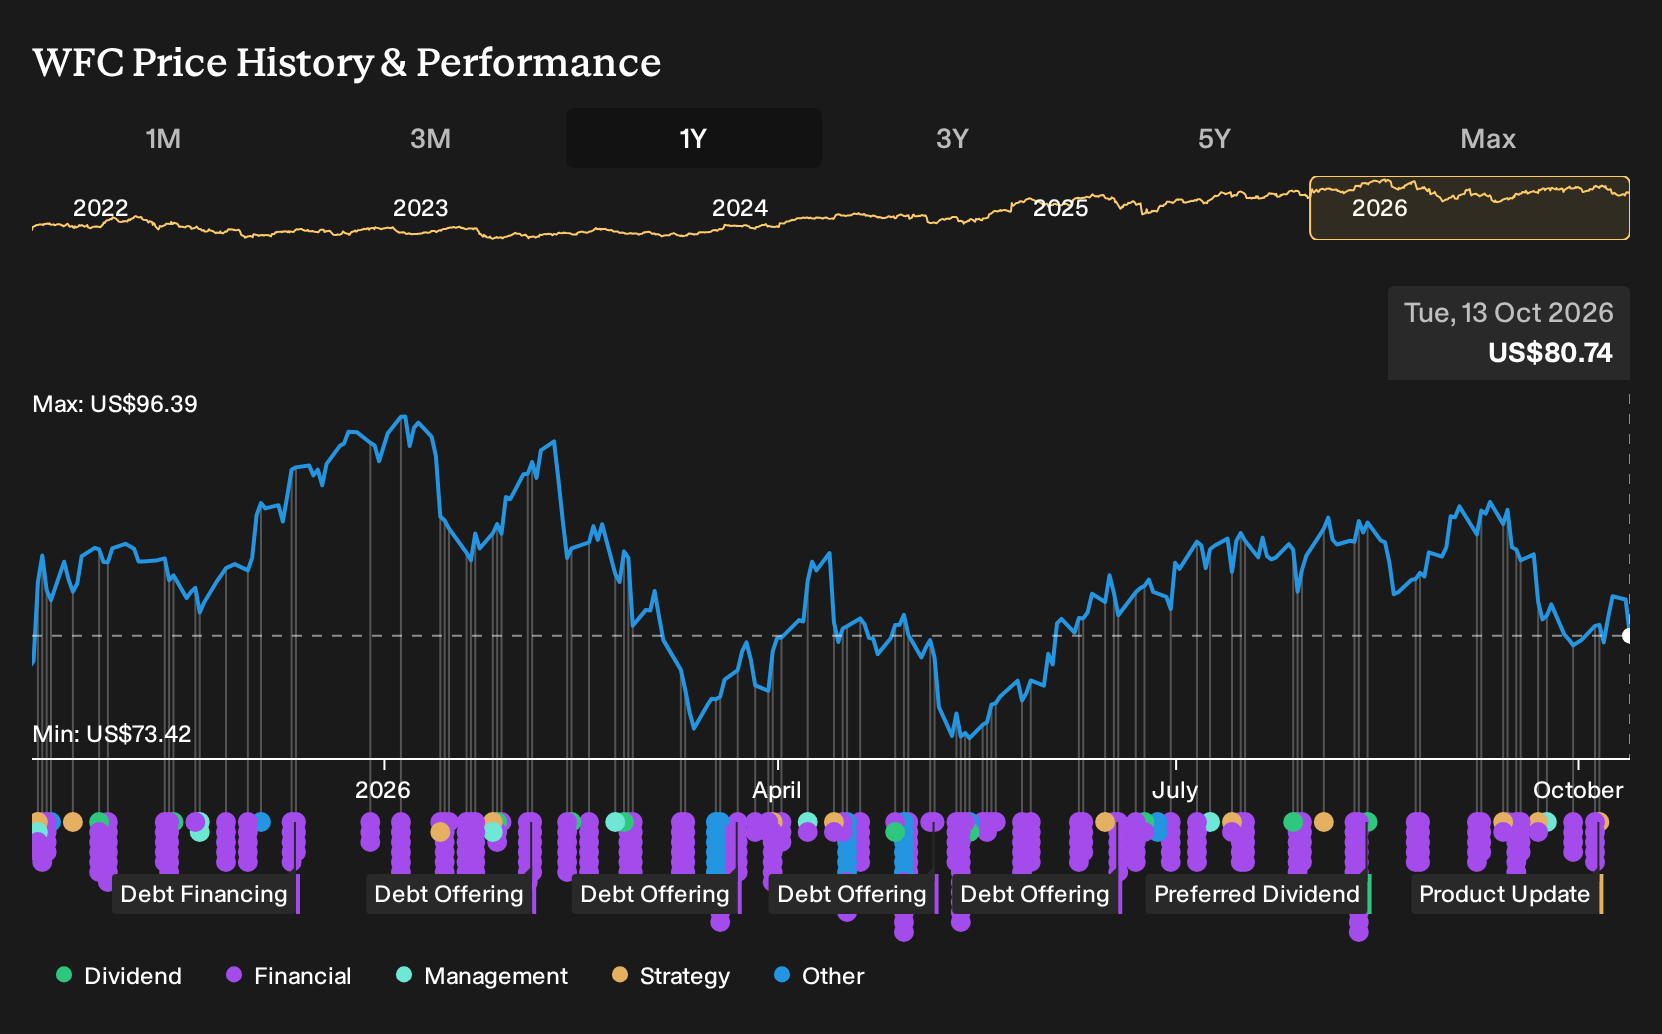
Wells Fargo is one of the largest US banks, with a US$252.0 billion market cap and a broad mix of consumer, mortgage, commercial and investment services. This ties its earnings closely to household spending patterns and business credit demand highlighted in this update.
See which insiders are buying and selling Wells Fargo following this latest news.
How Wells Fargo’s Q3 “resilient consumer” message fits its bigger story
The central bet in Wells Fargo’s Narrative is simple enough. The bank aims to use its larger post-asset-cap balance sheet and fee-heavy businesses to offset pressure on net interest margins, while keeping credit quality and risk controls tight.
"A key factor is that Wells Fargo continues to expand higher-fee and wealth businesses and achieves additional efficiency gains from technology and headcount reductions, without allowing credit quality or risk controls to deteriorate..."
See how the full story points towards a $100 fair value for Wells Fargo.
The latest quarter’s talk of “resilient” consumer spending, rising deposits and low credit losses supports the Narrative’s requirement that growth does not come at the expense of underwriting discipline. Stable charge-offs at under US$1.0b and what management describes as healthy loan performance line up with that, even as net loan charge-offs are slightly higher than a year ago. For investors comparing Wells Fargo with JPMorgan or Bank of America, this helps frame the consumer book as a support for the thesis rather than an obvious weak link.
The friction point is elsewhere. Revenue and net interest income misses sit squarely in the Narrative’s risk bucket that highlights margin compression and lower spread Markets balances as a threat to earnings power. Reaffirmed guidance of roughly US$13b in Q4 NII and about US$50b for 2026 suggests management is holding the line for now. It also shows why analysts focus so heavily on funding costs and asset mix when deciding whether the loan growth story still outweighs the squeeze on spreads.
News like this only becomes useful for you when it is weighed against a clear Narrative, because that is what turns scattered quarterly data into a coherent investment case you can actually judge.
One more question Wells Fargo investors should be asking
Quarterly headlines only tell you what Wells Fargo looks like today. The analyst models sketch a very different destination over the next few years, and that gap is where your real decision lives. See where analysts expect Wells Fargo to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com