
How China Memory Risks Have Changed The Case For Seagate Stock
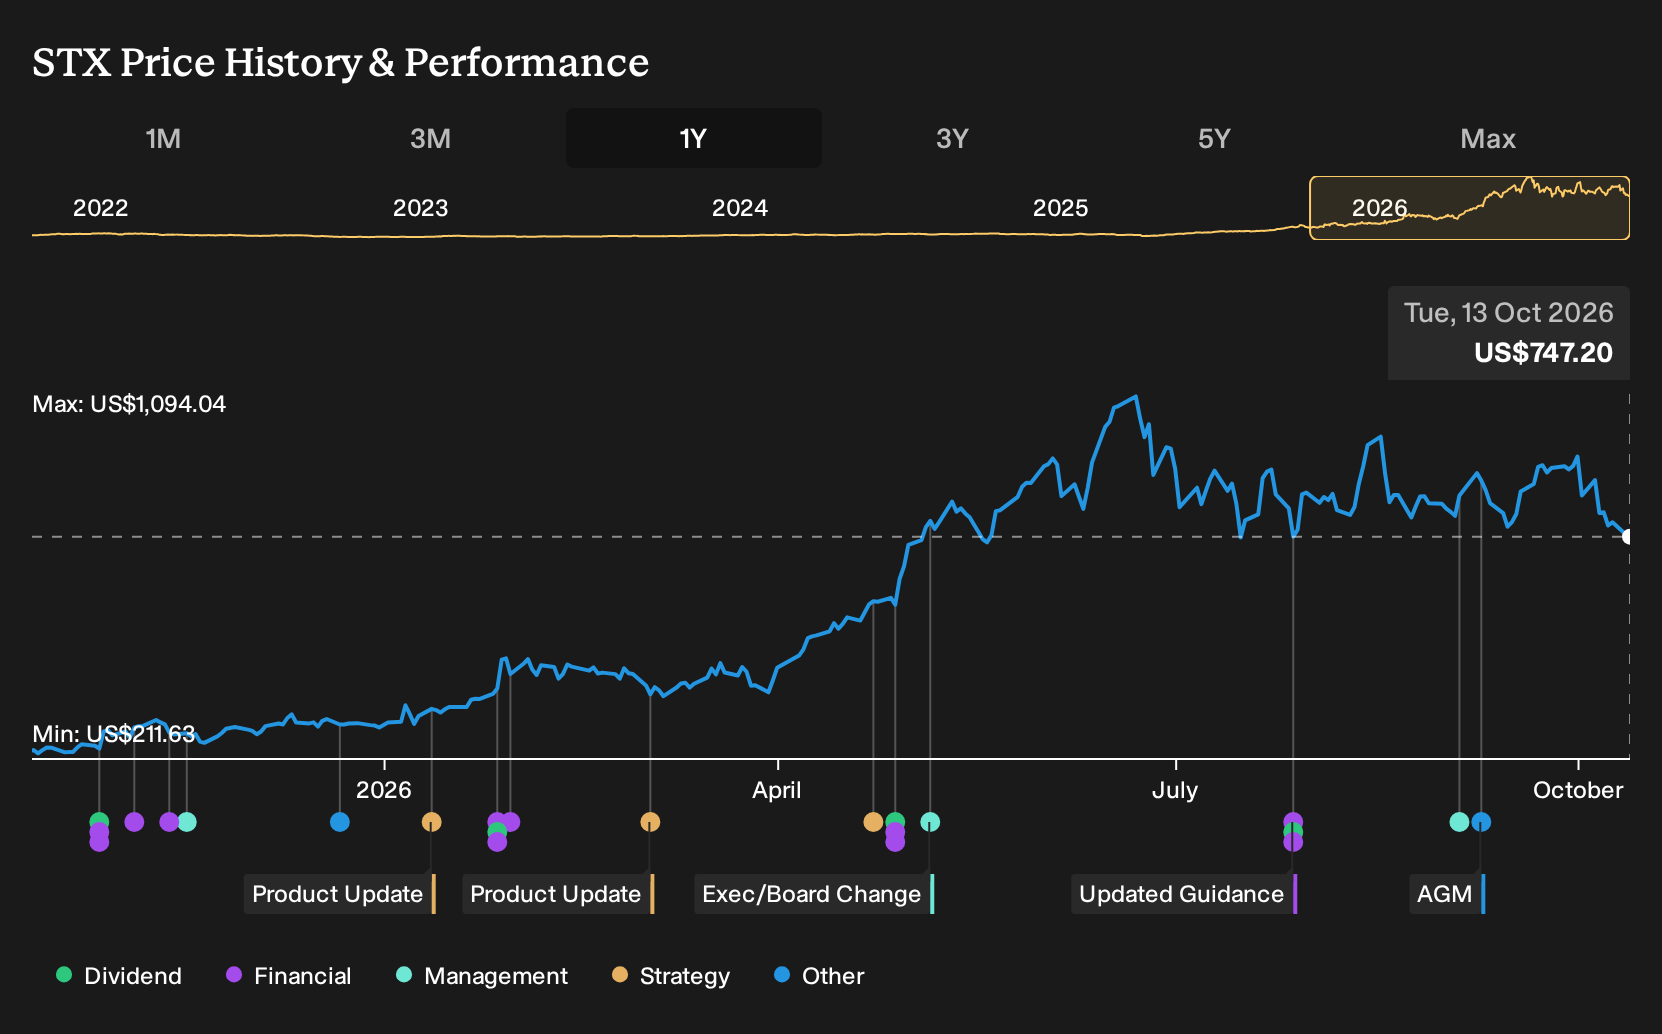
- Recent reports linked Seagate Technology Holdings to sector wide selling in memory related semiconductors, as investors reacted to Chinese progress in DRAM technology and potential labor disruptions in Taiwan that could affect global chip supply chains.
- The episode highlights how Seagate’s fundamentals, including its focus on data center storage and long term capacity plans, remain exposed to external technology competition and manufacturing concentration risks along the broader semiconductor value chain.
- This raises questions about how Seagate’s investment narrative will be perceived in light of rising Chinese memory competition discussed in recent news flow.
Seagate Technology Holdings Investment Narrative Recap
To be a shareholder in Seagate Technology Holdings, you need to buy into a thesis that long term AI and cloud data growth keep pulling more exabytes into nearline hard drives, and that the Mozaic HAMR roadmap holds its lead in capacity and pricing. The key near term swing factor is execution on those high capacity drives and keeping long term build to order commitments on track.
The latest sector wide selling tied to Chinese memory headlines looks more sentiment driven than directly tied to Seagate’s immediate operations. The bigger operational risk right now is any disruption to global manufacturing or to supply discipline that could pressure pricing and margins after a very strong run.
The upcoming fiscal first quarter 2027 earnings release on 27 October 2026 is the announcement that matters most in this context. Management has talked about healthy AI led storage demand, Mozaic driven margin strength and build to order coverage out to 2028 and 2029. This update is where those claims meet hard numbers.
For you, the read through is simple. Watch whether exabyte shipments, price per exabyte and HAMR mix hold close to what Seagate has previously outlined, and whether any commentary on Chinese DRAM progress or Taiwan labor risk filters into storage customer behavior. Any shift here feeds directly into the near term catalyst and the main risk case.
Seagate Technology Holdings' narrative projects US$31.1b revenue and US$16.1b earnings by 2029. This aligns with analyst assumptions for 36.6% yearly revenue growth and implies earnings would need to increase by about US$12.9b from US$3.2b today.
Uncover why Seagate Technology Holdings' fair value indicates a 51% potential upside to its current price and how that discount could compress if sentiment shifts.
Exploring Other Perspectives
Another angle to watch is revenue sensitivity if AI storage spending cools. The most pessimistic analysts were already pencilling in 34.3% yearly top line growth to about US$29.5b and earnings of roughly US$15.0b by 2029. After the latest China and Taiwan headlines, those pre news assumptions may shift further.
Explore 5 other Seagate Technology Holdings fair value estimates, including one that suggests up to 6% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Seagate Technology Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Seagate Technology Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seagate Technology Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Seagate Technology Holdings?
If the Seagate Technology Holdings story has sharpened your thinking about AI infrastructure and data growth, you can use that same lens across the wider market. The Simply Wall St Screener can help you quickly surface other opportunities that fit your risk profile and income goals.
- For investors hunting for resilient businesses with steadier profiles, check out 32 resilient stocks with low risk scores which may better match a capital preservation mindset.
- If your priority is compounding through quality at a sensible entry point, scan our curated set of 20 high quality undiscovered gems which combine robust fundamentals with lighter market attention.
- Income focused readers who care about consistency from cash returns can review a hand picked universe of 8 dividend fortresses which put regular shareholder payouts front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com