
Ross Stores (ROST) Stock Looks Above Fair Value After Its 119% Run
Ross Stores has delivered a powerful multi year share price run, and with the stock now around US$225, the key issue for investors is whether that performance is fully backed by its earnings power.
- Over the past 5 years, Ross Stores has returned about 119.4%, which puts real pressure on the question of whether current earnings can shoulder that kind of share price appreciation.
- The company has recently completed its fiscal 2026 store expansion plan with 115 new locations, a step that may support future earnings if the larger footprint converts into sustained profit per store rather than just higher operating costs.
- There is a second opinion on Ross Stores worth weighing. See what analysts think Ross Stores's shares could be worth.
The stock's next move may depend on whether Ross Stores' present earnings justify the valuation investors are now being asked to pay.
If you are weighing whether Ross Stores' recent 119.4% five year return is fully supported by its earnings, it can help to compare that question across 32 high quality undervalued stocks
Has Ross Stores Run Too Far on Earnings?
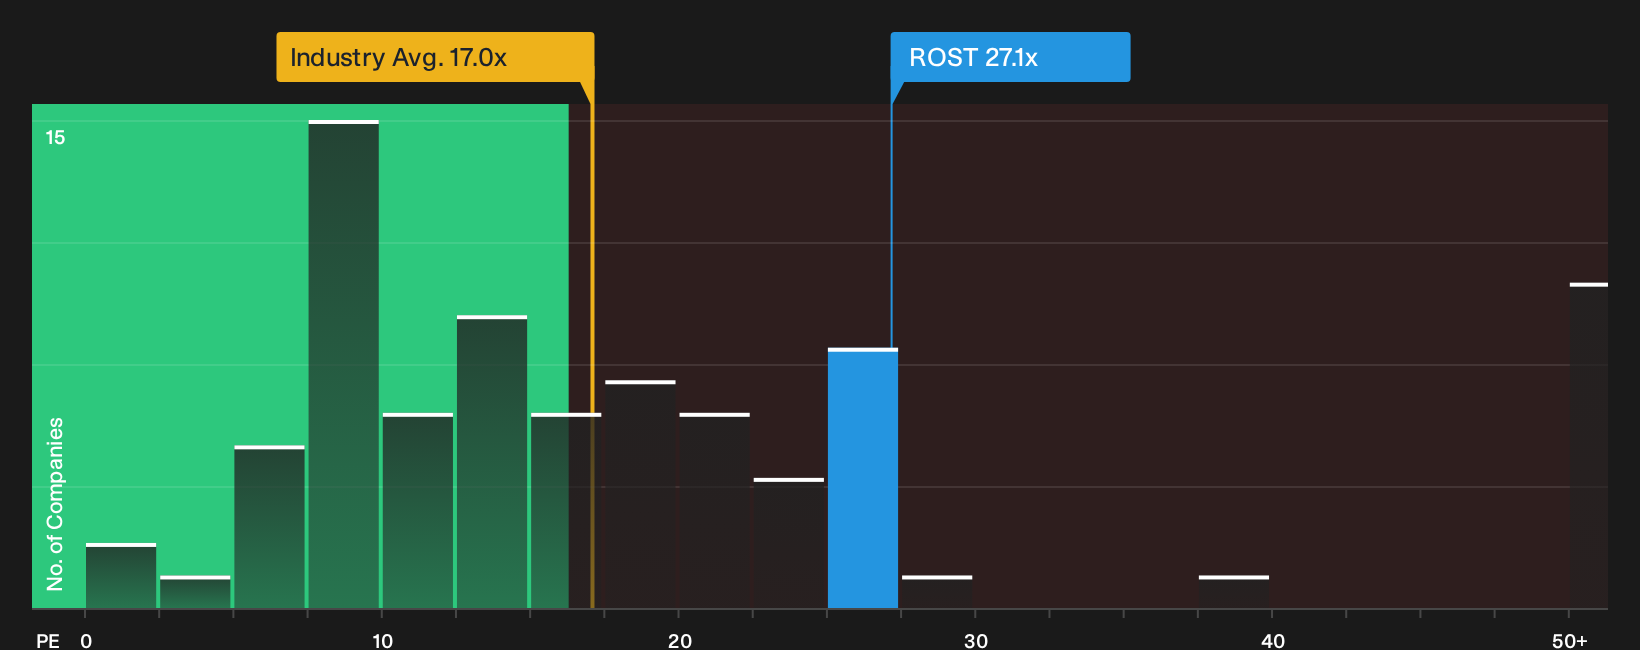
The P/E ratio works well for Ross Stores because earnings remain the main yardstick investors are using to justify the share price. At roughly 27.1x, the stock trades at a clear premium to the Specialty Retail sector, which is around 17.0x, and also above the peer group average near 17.0x. A tailored fair multiple for Ross Stores that factors in its specific growth profile, profitability and risk sits below the current level, which points to the shares looking overvalued on this measure.
Because Ross Stores has just completed its fiscal 2026 expansion plan with 115 new stores, the current premium P/E also reflects investor confidence that this larger footprint will be converted into durable earnings rather than just extra overhead. For anyone assessing the stock today, the key question is whether that optimism is already fully captured in a multiple that runs well ahead of sector norms, or whether there is still room for the business to grow into it. Explore the numbers behind Ross Stores's P/E valuation.
The Ross Stores Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Ross Stores valuation question leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to end up meaningfully above or below today's price. Each narrative links a specific fair value estimate to a distinct storyline about Ross Stores' potential catalysts and key risks so you can track over time which version of events is actually unfolding in the real business.
Ross Stores splits opinion, with one group arguing the market is still underestimating the story while another thinks investors are paying too much for a solid but limited compounding machine.
Bull case: 17% undervalued
"Continued broad-based customer growth, with double digit increases in shopper counts across income levels, age groups and ethnicities and higher transaction counts driving recent comparable sales, could extend Ross Stores revenue and earnings…"
Discover why this Narrative puts Ross Stores at 17% undervalued.
Bear case: 202% overvalued
"The reason not to overpay for it is that Ross is the structurally smaller player in a business where buying scale is the moat itself, and it has been losing relative scale to TJX for a decade…"
Explore why this Narrative puts Ross Stores at 202% overvalued.
One more Ross Stores question investors should not skip
All of this still leaves one missing piece, because Simply Wall St's broader checks have flagged specific concerns about Ross Stores that sit outside the earnings and valuation story and deserve a closer look. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com