
J. Front Retailing (TSE:3086) Stock Premium Meets Shrinking Profit Margins
Investors walked into this J. Front Retailing print already paying up for the story, with the stock on a rich 23.6x trailing P/E and trading well above one widely watched discounted cash flow estimate. The headline from the quarter is not about sales, which were steady in the ¥100 billion range. The real pressure point is profitability, with trailing net profit margin now at 6.2% compared with 6.8% a year earlier, leaving anyone buying the premium multiple to ask how much earnings power is being squeezed inside those department stores.
Love the J. Front Retailing brand strength but worried about paying a premium P/E while margins are under pressure? Benchmark that concern against our 22 resilient stocks with low risk scores.
Q2 2027 J. Front Retailing Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥107,386 million vs. ¥109,123 million (a slight decline in quarterly top line)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥7,682 million vs. ¥7,871 million (modest earnings softness)
- Basic EPS (Q2 2027 vs Q2 2026): ¥31.38 per share vs. ¥31.48 per share (an effectively flat per share result)
- Trailing 12M Net Income (Excl. Extra Items, to Q2 2027 vs to Q2 2026): ¥27,307 million vs. ¥30,684 million (pressure on profitability over the last year)
Prefer crisp visual charts instead of another wall of earnings tables and ratio math? See J. Front Retailing’s full financial picture, with a clear view of its valuation in our company report for J. Front Retailing.
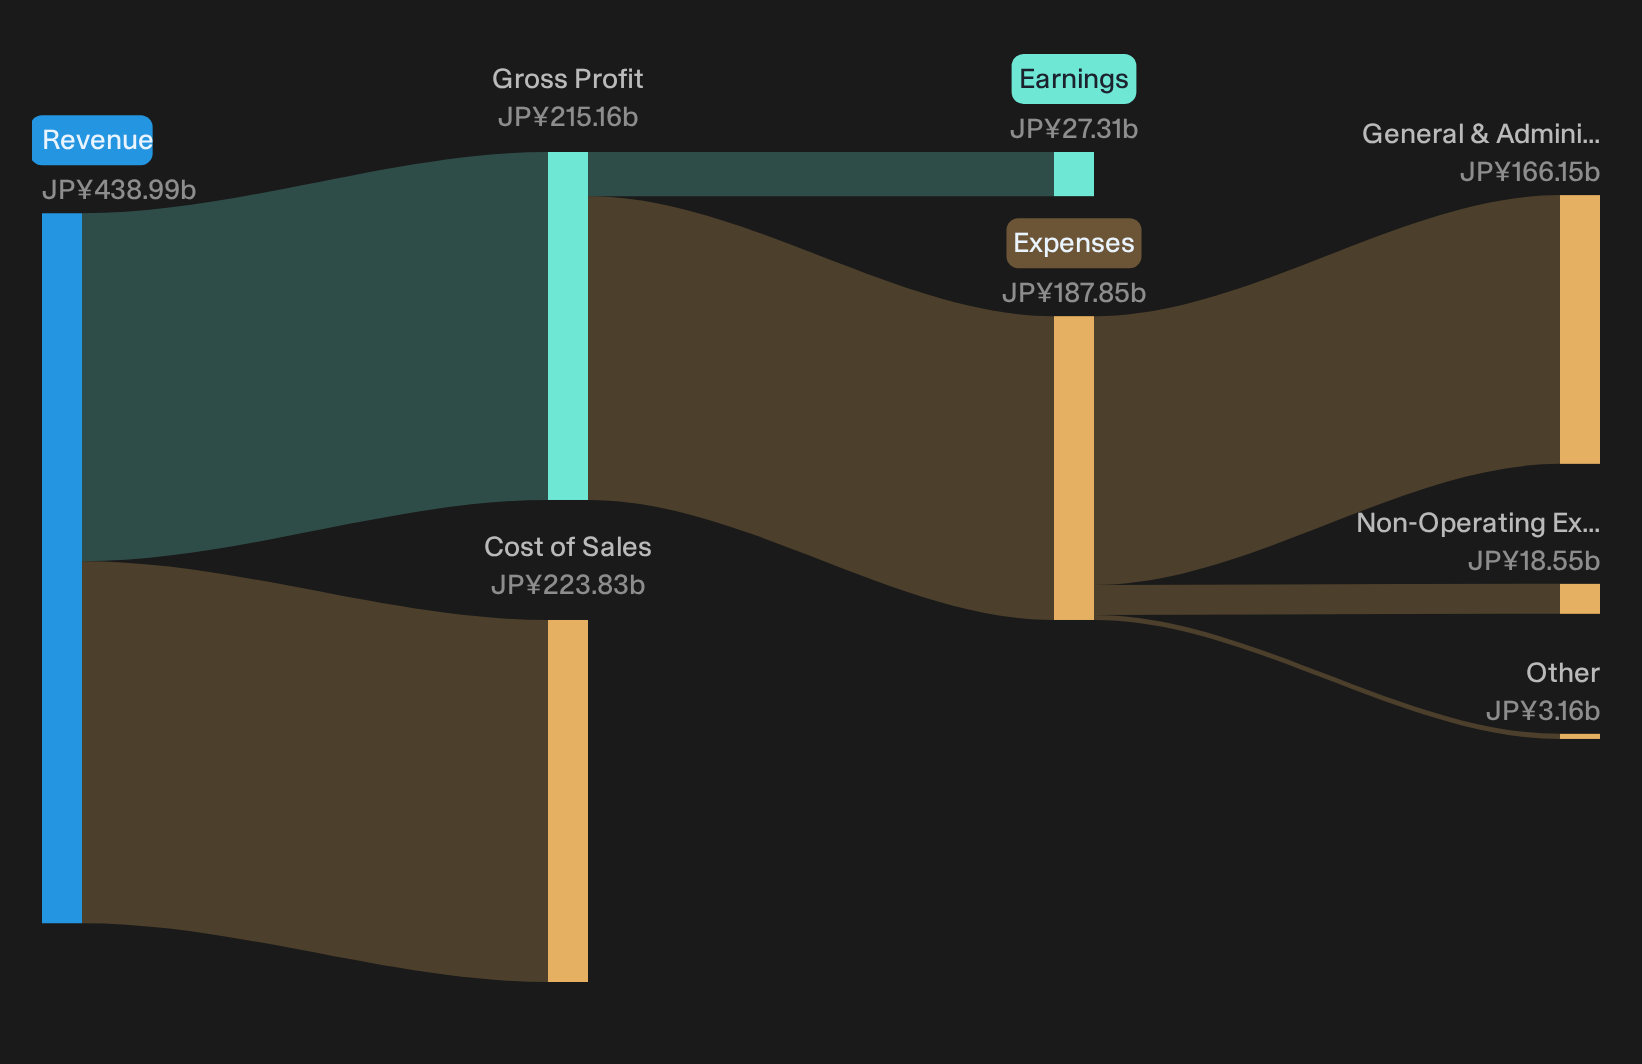
Evaluating J. Front Retailing’s Recovery Milestones
Bulls argue J. Front Retailing is in a controlled recovery, using refurbishments, new content and customer programs to lift quality of earnings. The latest quarter only partly supports that script. Department store and PARCO focused initiatives aimed at a richer sales mix show up as relatively steady quarterly revenue around ¥107,386 million, which helps the story that traffic and spend have not fallen away sharply. Profit tells a different tale. Trailing 12 month net income of ¥27,307 million versus ¥30,684 million signals that higher margin content, reuse ventures and design or construction consolidation are not yet offsetting cost pressure.
Customer monetization efforts and the growing payments or finance ecosystem are meant to add resilience. The near flat basic EPS of ¥31.38 against ¥31.48 suggests these engines are at least cushioning earnings, but they are not yet delivering the uplift that bullish investors are looking for.
Reveal where the surface looks calm but the models start to diverge by checking what the street is quietly baking in for J. Front Retailing’s revenue, margin and EPS glidepath in the analyst estimates for J. Front Retailing.J. Front Retailing Bears See Profit Milestones Slip
Bears argue J. Front Retailing faces squeezed profitability while heavy renovation, construction and new business spend chew through earnings. This quarter leans their way. Trailing 12 month net income of ¥27,307 million versus ¥30,684 million shows the investment phase is still biting into profit, even as quarterly revenue holds around ¥107,386 million.
Critics also worry that payment and finance rollouts, content, and reuse projects will leave fixed costs high without enough payoff. Near flat basic EPS at ¥31.38 against ¥31.48 suggests cushioning, not acceleration. That misses the milestone of visible margin rebuild. Developer and construction risk is another bearish plank. The softer earnings run rate implies those higher return projects are not yet offsetting redevelopment drag. With the share price down roughly 20% over 90 days, the market reaction lines up more with these caution flags than with a clean recovery story.
After renovation costs, softer earnings and an unstable dividend record, you may be missing structural weak spots. Review our full risk analysis for J. Front Retailing which shows 1 important warning sign.Stay Ahead With Simply Wall St
J. Front Retailing’s rich P/E and softer margins make it a stock you may want to watch closely rather than react to headline moves. Register for free with Simply Wall St and add it to your Watchlist so you can track price against fair value and wait for conditions that fit your own entry rules. Once you hold it, keep the story straight with our Portfolio Command Center that cuts through noise and surfaces only the most important fundamental changes. Round out your view by tapping into crowd insight through the Community, so you can spot potential catalysts or new risk flags early and stay a step ahead of the wider market.
Seeking Alternatives Beyond J. Front Retailing?
Fresh ideas move first. While the next breakout stories are still under the radar for now, momentum shifts fast and late arrivals get caught chasing. Act now.
- Spot resilient cash generators before momentum heats up by scanning companies in the list of solid balance sheet and fundamentals stocks (21 results) that can better handle shocks while others are still scrambling.
- Hunt for income opportunities with staying power by reviewing the 27 dividend fortresses that aims to surface payout heavyweights before yields start dropping.
- Track early leadership in digital assets by reviewing the 19 cryptocurrency and blockchain stocks where listed businesses tie into real blockchain and cryptocurrency use cases while it still matters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com