
Pediatric Valve Approval Could Be A Game Changer For Edwards Lifesciences (EW)
- Edwards Lifesciences received FDA approval for the AUTUS Size-Adjustable Valve, a surgical pulmonary valve for children with congenital heart disease that can be expanded through a transcatheter procedure as they grow, with pivotal trial data showing no device related complications at 30 days and no valve reinterventions through one year of available follow up.
- The AUTUS valve targets a structurally underserved pediatric segment where pulmonary valve replacements often require multiple open heart surgeries. A size adjustable design may lower long term procedural burden and reshape how Edwards Lifesciences invests in congenital therapies within its structural heart portfolio.
- We will now examine how Edwards Lifesciences’ investment narrative around structural heart expansion could shift with the AUTUS pediatric valve approval.
Scan pediatric and structural heart opportunities such as Edwards Lifesciences by reviewing our hand picked list of 32 high quality undervalued stocks that combine strong fundamentals with potential for re rating.
Edwards Lifesciences Investment Narrative Recap
To own Edwards Lifesciences, you need to believe in its long term plan around structural heart therapies, including TAVR and transcatheter mitral and tricuspid treatment, and in its ability to gradually expand margins despite recent compression. The AUTUS approval helps the story at the edges, but the near term spotlight still sits on execution in core transcatheter franchises and upcoming Q3 2026 results.
The biggest operational risk today sits in profitability and cost pressure. Margins have already moved lower, tariffs and legal constraints around M&A add friction, and earnings had a large one off loss in the last twelve months. AUTUS does not remove those issues. It simply adds another, more pediatric focused, lever inside an already complex portfolio.
The AUTUS Size Adjustable Valve approval is the clearest link between this news and Edwards Lifesciences current catalysts. Management has talked about structural heart expansion, and Medicare coverage changes for TAVR already support more procedure volume. AUTUS plugs into that broader thesis by widening the pool of structural patients the group can serve.
For you as a shareholder, the operational question is not whether AUTUS alone moves the needle. The focus is how well Edwards Lifesciences layers this pediatric product into existing commercial channels while still chasing TMTT revenue milestones, margin expansion targets, and tighter control of legal, tariff, and funding related risks that sit around the wider business.
Edwards Lifesciences' current analyst narrative points to revenues of US$8.5b and earnings of US$2.2b by 2029, implying forecast revenue growth of 9.3% per year and an earnings increase of about US$1.2b from earnings today of US$979.9m.
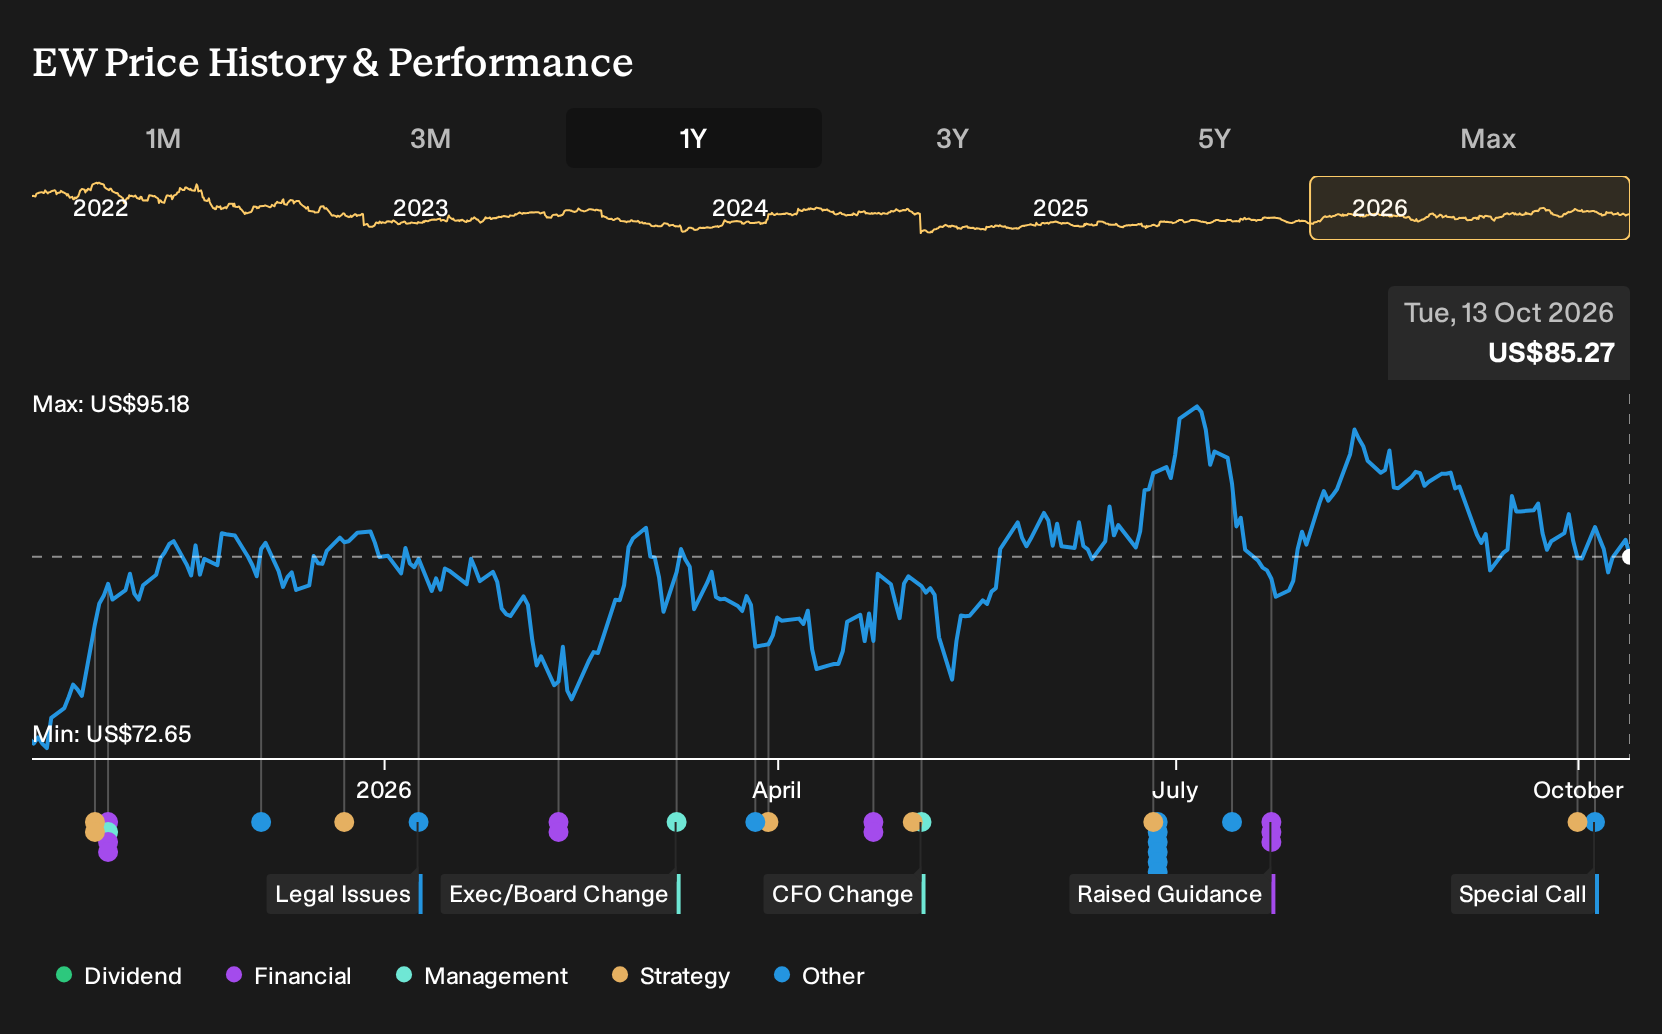
Uncover why Edwards Lifesciences' fair value indicates an 18% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$90.5 and US$101 per share, yet they still show how sharply opinions on Edwards Lifesciences can split once assumptions change. Set those against live risks around tariffs, M&A constraints, and governance questions, and you are looking at a company where it is particularly important to compare several viewpoints before deciding what the AUTUS approval and TAVR trajectory could mean for long term performance.
Explore another Edwards Lifesciences fair value estimate, including one that suggests it could be worth just $90.51.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Edwards Lifesciences research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Edwards Lifesciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edwards Lifesciences' overall financial health at a glance.
Looking for more Edwards Lifesciences sized opportunities?
If Edwards Lifesciences has sharpened your appetite for focused, fundamentals driven ideas, it makes sense to widen your search with structured stock lists rather than scrolling tickers at random.
- For investors who want stability first and potential upside second, start with a 32 resilient stocks with low risk scores that already screen well on resilience and downside protection.
- If balance sheet strength is non negotiable for you, filter for companies with solid finances and dependable metrics through our list of solid balance sheet and fundamentals (25 results).
- If you prefer to hunt for future leaders before they are widely followed, then spend time in our 20 high quality undiscovered gems that pair quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com