
Amkor Technology (AMKR) Stock Still Looks Undervalued Despite Its 127% Run
Amkor Technology has produced strong multi year gains for shareholders, yet the recent pullback raises a sharper question about whether the current share price lines up with the earnings that underpin it. For investors watching a stock that has moved a long way over several years, the issue now is how much of the business's profit power is already reflected in the valuation.
- Over the past 5 years, Amkor Technology has delivered a 126.9% total return, which puts real weight on whether today's valuation can be backed up by the company's earnings base.
- The business depends on capital intensive packaging and test facilities, so the level and timing of profit generation from those assets can heavily influence how investors judge its earnings multiple.
- The analysts covering Amkor Technology have run their own numbers. See what analysts think Amkor Technology's shares could be worth.
The stock's next move may depend on whether Amkor Technology's current earnings are strong and durable enough to support the price investors are being asked to pay today.
If you want more ideas while you assess whether Amkor Technology's recent 5 year return of 126.9% is fairly earned by its profit base, a focused stock screen is a useful second step via 32 high quality undervalued stocks.
Does Amkor Technology Look Undervalued on Earnings?
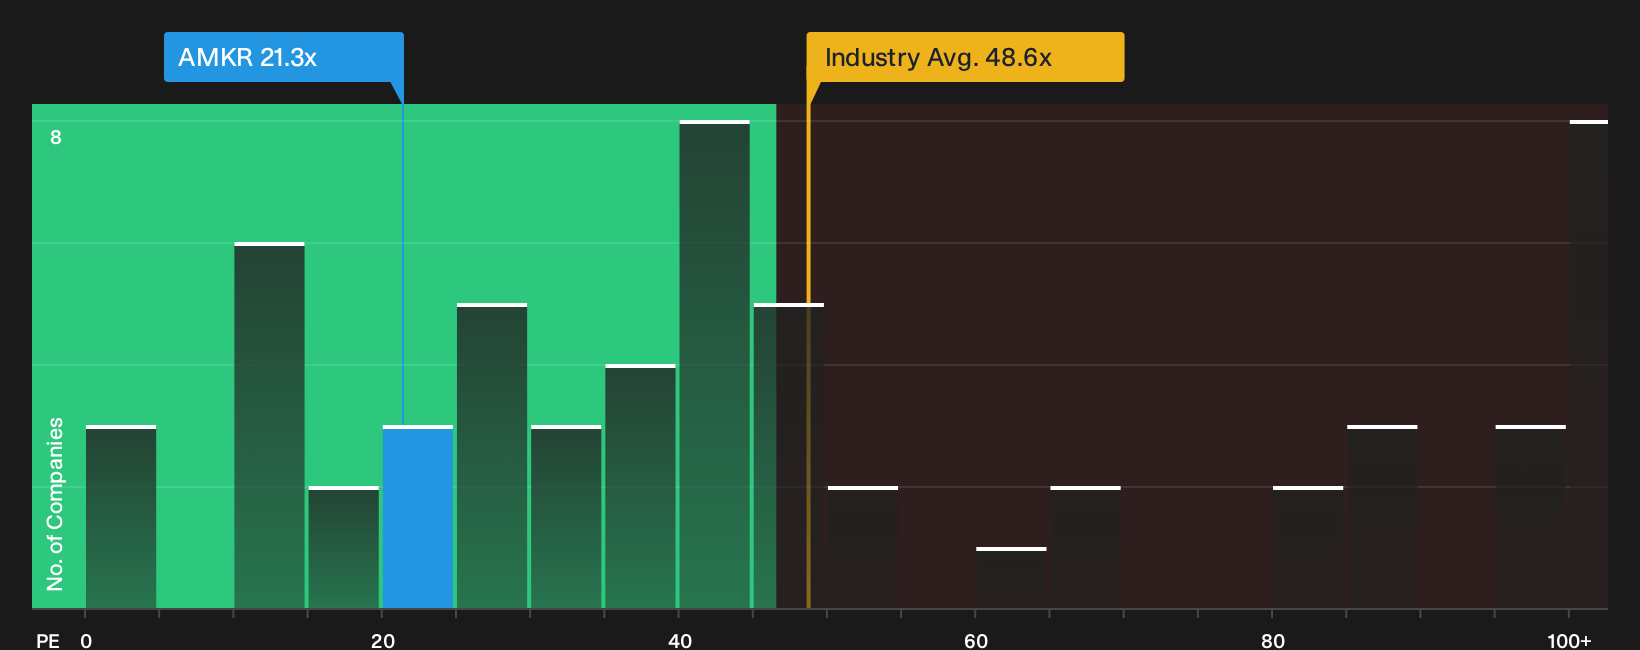
The P/E ratio is a useful yardstick for Amkor Technology because earnings sit at the center of how investors judge capital intensive semiconductor packaging and test businesses. On this measure, the stock trades on about 21.3x earnings, which is well below both the Semiconductor industry average of roughly 48.6x and the peer group at around 65.6x. That gap indicates that the market is attaching a lower earnings multiple to Amkor Technology than many other listed chip related companies.
The Fair Ratio, which reflects what might be expected given the firm’s sector, profitability profile and scale, points to a higher P/E than where the shares change hands today. That suggests the current pricing implies a discount rather than a premium on this framework. However, any investor still needs to weigh how cyclical demand, capital spending needs and execution risks could affect the earnings that sit under that multiple. Explore the numbers behind Amkor Technology's P/E valuation.
The Amkor Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Amkor Technology pick up where the P/E discussion leaves off. They outline which paths for growth, profitability and earnings would need to occur for the stock to be worth meaningfully more or less than it is today on the market. Each scenario links a single number to a clear view of how Amkor Technology's margins, expansion prospects and risks might evolve, so you can revisit those assumptions as fresh information comes through.
One of the top community narratives on Amkor Technology: 38% undervalued
"Acceleration in AI data center and high performance computing programs is increasing demand for advanced packaging and supporting a richer earnings mix..."
Discover why this Narrative puts Amkor Technology at 38% undervalued.
An unresolved piece of the Amkor Technology puzzle
Everything so far has focused on what Amkor Technology looks like today, yet there is a parallel view that comes from how professional analysts map out its earnings profile several years ahead. Explore where analysts expect Amkor Technology to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com