
Novo Nordisk (CPSE:NOVO B) Stock Looks Below Fair Value Right Now
Novo Nordisk has seen its share price fall sharply over the past few years, even as its obesity treatments remain central to the pharma story. That gap between a weaker stock chart and an earnings driven investment case raises the question of whether today's valuation still lines up with what the business is actually earning.
- The share price has declined 60.8% over the past 3 years, which puts a lot of weight on whether current earnings can still justify where the stock trades now.
- Fresh data for Wegovy and its oral semaglutide pill may support expectations for obesity related revenue and profit, which feeds directly into how investors think about Novo Nordisk's earnings power over time.
- There is a second opinion on Novo Nordisk worth weighing. See what analysts think Novo Nordisk's shares could be worth.
The stock's next move may depend on whether Novo Nordisk's current price can be squared with what its earnings suggest the business is worth today.
If you are weighing Novo Nordisk's earnings story against its share price slide, it can help to compare it with a wider set of 185 high quality undervalued stocks.
Is Novo Nordisk Still Cheap on Earnings?
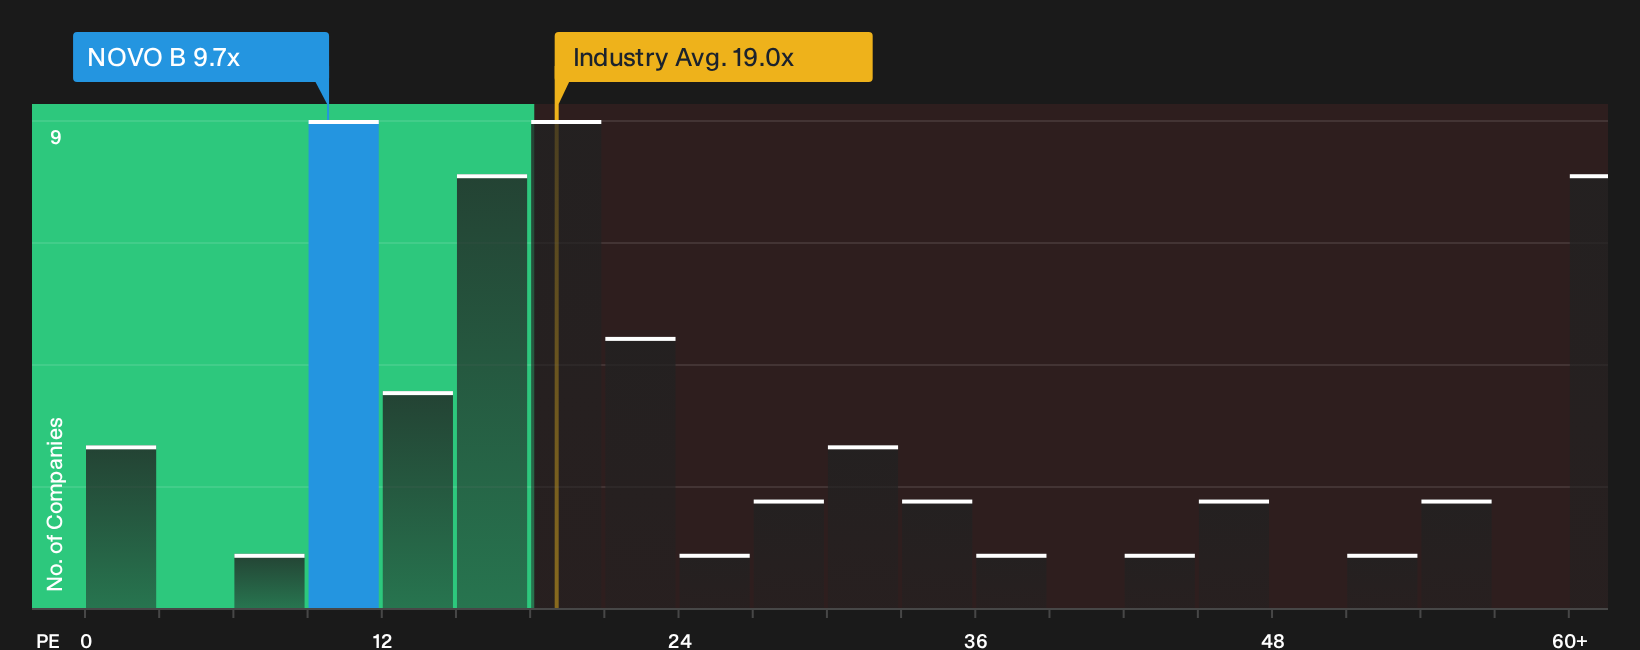
P/E works well for Novo Nordisk because earnings are a key focus for investors watching how its obesity portfolio translates into profit. On that metric, the stock trades on about 9.7x current earnings, well below the broader pharmaceuticals sector on roughly 21.5x and also under a peer group closer to 27.4x. Because the recent Wegovy and oral semaglutide trial readouts have kept attention on future obesity demand, this gap shows the market is not paying the same headline premium for Novo Nordisk as for many other large drug makers.
The in house fair multiple, which blends factors like profitability, growth expectations, size and risk, points to a higher P/E than where Novo Nordisk trades today. That places the current 9.7x below what that framework would suggest investors might usually pay for this earnings profile, even after accounting for sector norms. Because the Wegovy liver fat and pill switching data give more detail on how the obesity franchise could support profits, the low P/E relative to that tailored fair value will matter for anyone judging whether the recent share price slide has gone too far. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Novo Nordisk's recent valuation puzzle sets up the role of Simply Wall St Narratives. These are investor written scenarios that spell out which assumptions on growth, margins and earnings would need to hold for the stock to be worth significantly more or less than it is today. Each one treats fair value as a thesis about Novo Nordisk's business that can be tracked over time, rather than a one off snapshot. Narratives sit on Simply Wall St's Community page so you can see how different convictions line up with the current share price.
Community views on Novo Nordisk are split between a market veteran who sees a deep moat and a bear who worries execution now has less room for error.
Bull case: 70% undervalued
"Novo Nordisk has built a formidable economic moat through decades of expertise in diabetes care, world-class manufacturing, and a trusted global brand…"
Discover why this Narrative puts Novo Nordisk at 70% undervalued.
Bear case: 26% overvalued
"The numbers imply that Novo Nordisk’s current share price already reflects mid single digit revenue growth through 2030, with at least five multi-blockbuster launches…"
Explore why this Narrative puts Novo Nordisk at 26% overvalued.
Novo Nordisk has one more key check investors should look at next
Price and current earnings tell only part of the story for Novo Nordisk, since analyst models a few years out offer a separate yardstick you can weigh against today's market view. Explore where analysts expect Novo Nordisk to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com