
HubSpot (HUBS) Stock May Be Fully Priced After AI Reorganization
HubSpot has seen its share price retreat sharply over recent years, and the stock now trades against a very different backdrop for its earnings than five years ago. With that reset in market value and a major reorganisation under way, the key issue for you is whether today’s price makes sense in light of what the business currently earns.
- The share price has fallen 72.0% over the past 5 years, which puts the focus squarely on whether the earnings now underpin or still lag that reset valuation.
- The decision to cut about 660 jobs and refocus the organisation on AI driven customer outcomes can affect future profitability, cost structure and the timing of any improvement in earnings power.
- Your read on HubSpot is one view; the desks covering it have another. See what analysts think HubSpot's shares could be worth.
For investors, the debate is whether HubSpot’s current market value is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you want a broader starting point alongside HubSpot's reset, a focused stock screen built around AI themes can help you scan 38 AI small caps.
Does HubSpot Look Pricey on Earnings?
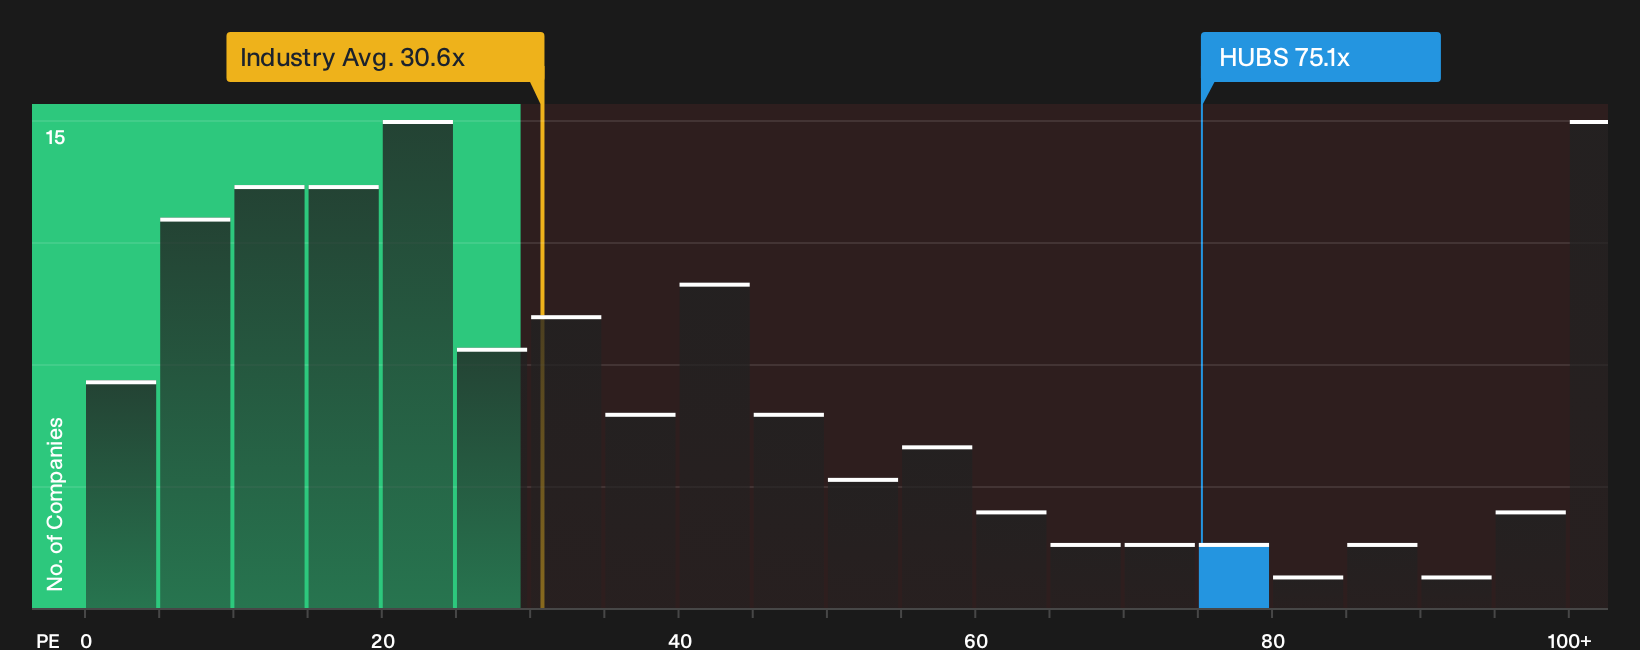
The P/E ratio fits HubSpot because you are weighing what investors pay today against the profits the platform is currently generating. On that score, HubSpot trades on about 75.1x earnings, compared with roughly 55.8x for close peers and about 30.6x for the broader Software sector. That kind of mark up tells you buyers are already paying a premium for each dollar of profit.
Because this P/E sits above the Fair Ratio benchmark that reflects HubSpot’s growth profile, margins, scale and risk, the stock screens as overvalued on this specific yardstick. The recent plan to cut about 660 roles and reorganise around AI driven customer outcomes has not stopped investors from assigning a richer multiple than both peers and the industry, so you need to judge whether that confidence in the reshaped business justifies the extra earnings premium. Explore the numbers behind HubSpot's P/E valuation.
The HubSpot Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around HubSpot and turn it into a set of clear “what needs to be true” paths that live on the Community page. Each narrative links a potential outcome for HubSpot's growth, margins and earnings to a specific scenario, with a fair value attached to that story so you can track over time which catalysts and risks seem to be playing out.
Community views on HubSpot now split between those who see a durable SMB CRM engine and those who think AI pricing and slower cycles leave too much optimism in the share price.
Bull case: 33% undervalued
"HubSpot is a leading, product-led CRM platform for SMBs and mid-market companies that bundles marketing, sales, service, operations and commerce capabilities..."
Discover why this Narrative puts HubSpot at 33% undervalued.
Bear case: 16% overvalued
"While the migration to new pricing, core seats and AI enriched seat types is designed to expand monetization, pushback on pricing changes from larger renewals or lower than expected seat upgrades could cap improvements in net revenue retention and operating margin..."
Explore why this Narrative puts HubSpot at 16% overvalued.
One more HubSpot check that sits outside the P/E debate
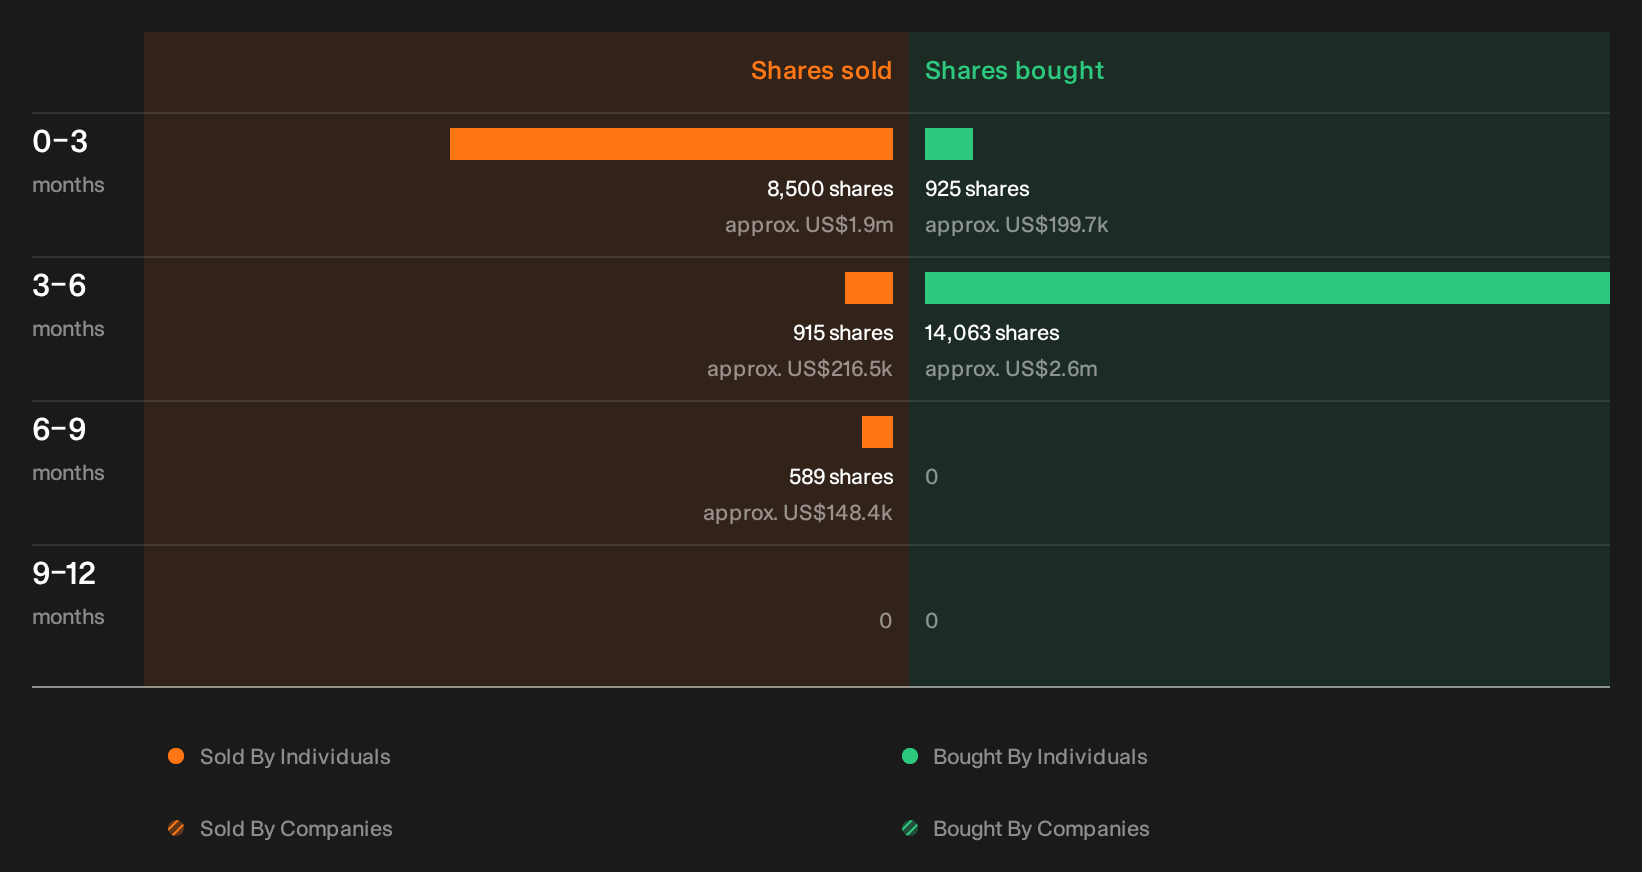
Price tags and narratives only tell part of the story, because recent insider share sales also sit on the record and the individuals, sizes and possible read throughs are for you to examine. See the recent insider selling flagged for HubSpot.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com