
KLA (KLAC) Stock May Look Pricey Despite Easing Supply Constraints
KLA has been on a powerful multi year run, and with the stock last closing at US$184.00 the key question for investors is whether that price still aligns with what its earnings support.
- The share price has climbed 481.6% over 5 years. This puts a lot of focus on how firmly current earnings can underpin that kind of long term return record.
- Recent commentary from Morgan Stanley suggests supply bottlenecks may ease and a stronger mix in leading logic tools could support margin expectations and the earnings power investors use in their valuation work.
- The analysts covering KLA have run their own numbers. See what analysts think KLA's shares could be worth.
The stock's next move may depend on whether KLA's current earnings are strong enough to justify today's market valuation.
If you are weighing whether KLA's earnings justify its recent multi year run, it can help to compare that story with other 92 AI infrastructure stocks.
Is KLA Getting Expensive on Earnings?
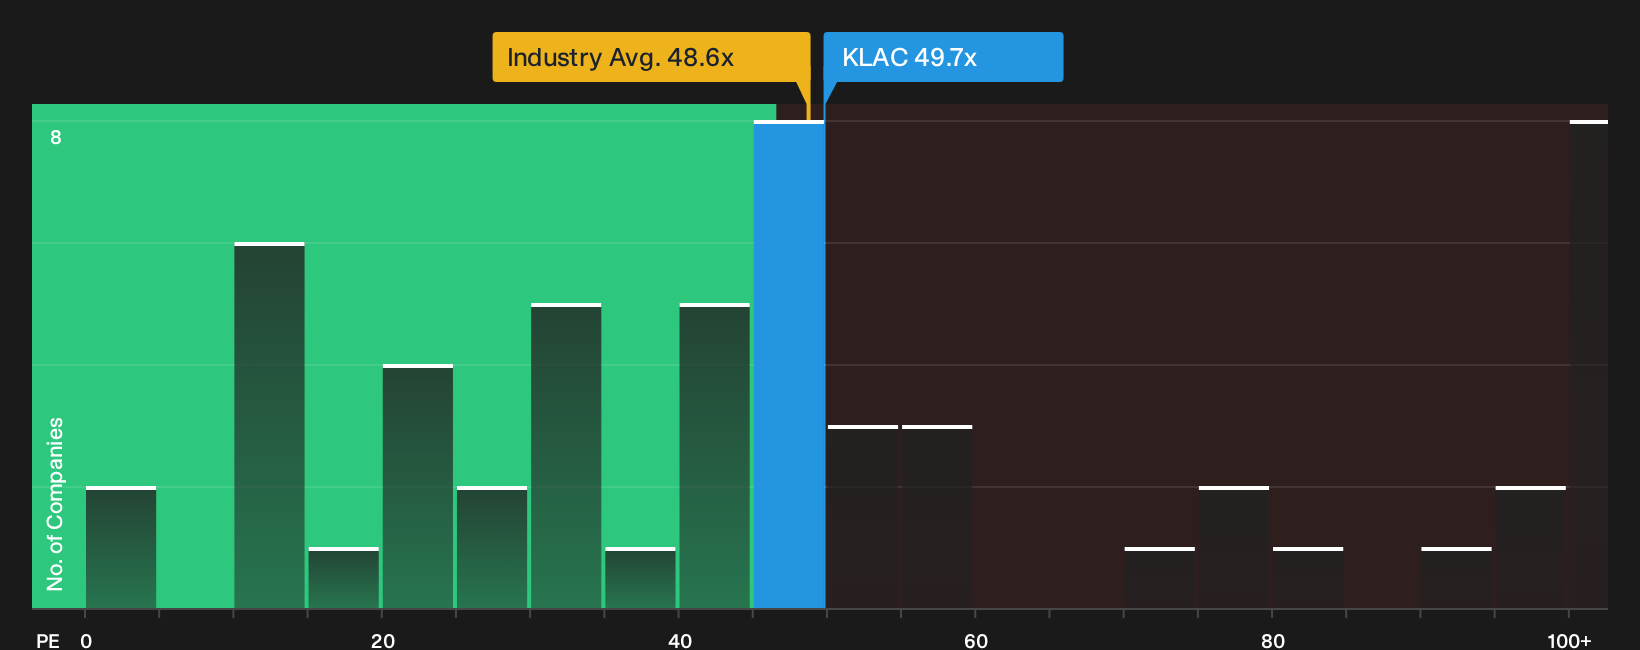
The P/E ratio is a useful lens for KLA because earnings power is central to how investors frame established semiconductor equipment businesses. KLA trades on a P/E of 49.7x, slightly above both the semiconductor industry average of 48.6x and the peer group at 46.8x. On this basic comparison, buyers today are paying a richer price per dollar of current earnings than they would for many similar stocks in the sector.
The fair value framework, which weights factors like profitability profile, size and sector risk, points to a lower P/E than where KLA is currently priced, so the stock screens as overvalued on this metric. Morgan Stanley’s view that easing supply constraints and a stronger leading logic mix could help margins explains some of that optimism, yet the valuation already builds in a strong earnings story. If you are comfortable with that implied earnings power, the present P/E can still make sense, but if you want a margin of safety on the multiple, it may look demanding. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for KLA pick up where the earlier valuation puzzle leaves off and spell out which paths for KLA's growth, margins and earnings would line up with a share price that is materially higher or lower than today. Instead of stopping at a single ratio or model outcome, they unpack the future that number leans on so you can watch how the real business lines up with that story over time on the Community page.
Community views on KLA split between a backlog and cash flow story and a margin pressure worry.
Bull case: 21% undervalued
"Rising AI infrastructure and high bandwidth memory investment is lifting wafer equipment demand, and KLA’s backlog of around US$12.5b with lead times that extend into 2027 and 2028 supports multi year visibility..."
Discover why this Narrative puts KLA at 21% undervalued.
Bear case: 5% overvalued
"Bearish analysts expect KLA's exposure to tariffs, elevated component costs, and fragmented supply chains to keep compressing gross margins even as wafer fab equipment spending remains high..."
Explore why this Narrative puts KLA at 5% overvalued.
One more KLA question worth asking
You have seen how the current share price lines up with today’s earnings. The next step is to see where professional forecasts think this business could be a few years from now. Explore where analysts expect KLA to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com