
How Acquisitions And Digital Growth Will Impact SiteOne Stock Investors
- SiteOne Landscape Supply is continuing its EBITDA expansion push through an active acquisition program, faster than 50% digital sales growth year to date, and ongoing productivity and distribution efficiency efforts.
- The company’s 108 completed deals since 2014, combined with further 2026 acquisitions and a scaled digital channel, highlight a business model built around consolidation and margin-focused execution rather than short term volume gains.
- We will now see how SiteOne Landscape Supply's rapid digital sales growth could reshape the existing investment narrative around consolidation and margins.
Scan other margin-focused consolidators with fast-growing digital channels by reviewing our hand-picked list of 20 high quality undiscovered gems alongside SiteOne Landscape Supply.
SiteOne Landscape Supply Investment Narrative Recap
To own SiteOne Landscape Supply, you need to believe the consolidation playbook and margin work can matter more than choppy volumes. The recent update on EBITDA expansion efforts supports that view. Digital sales growth faster than 50% and continued acquisition activity both support the idea that mix and efficiency, rather than sheer volume, drive the story.
The near term swing factor still looks like execution on margins while cyclical end markets stay soft. Weak volumes in key Sunbelt regions and flat organic trends keep the biggest risk squarely on slower progress than hoped. The latest news does not remove that risk, but it does not materially worsen it either.
The most relevant recent development is management’s clear emphasis on digital and M&A to extend EBITDA. Digital sales on siteone.com of about US$420m in 2025, with expectations to exceed US$600m in 2026, show how online ordering is becoming a core operating channel. When paired with 108 completed acquisitions since 2014, the model looks heavily skewed to scale and mix.
You should read those updates alongside the acquisition goal of adding more than US$2b of acquired revenue over the next decade and the push toward a 25% to 30% private brand mix. The catalyst is simple. If SiteOne converts that larger footprint and digital volume into higher private label penetration and better gross margin mix, the EBITDA expansion narrative gains more support.
SiteOne Landscape Supply is tied to analyst forecasts that point to roughly US$5.5b in sales and US$258.8m in earnings by 2029, built on an assumed 4.6% yearly revenue growth rate and an increase in profit from US$162.8m today. This implies an earnings uplift of about US$96m over that period.
Uncover why SiteOne Landscape Supply's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
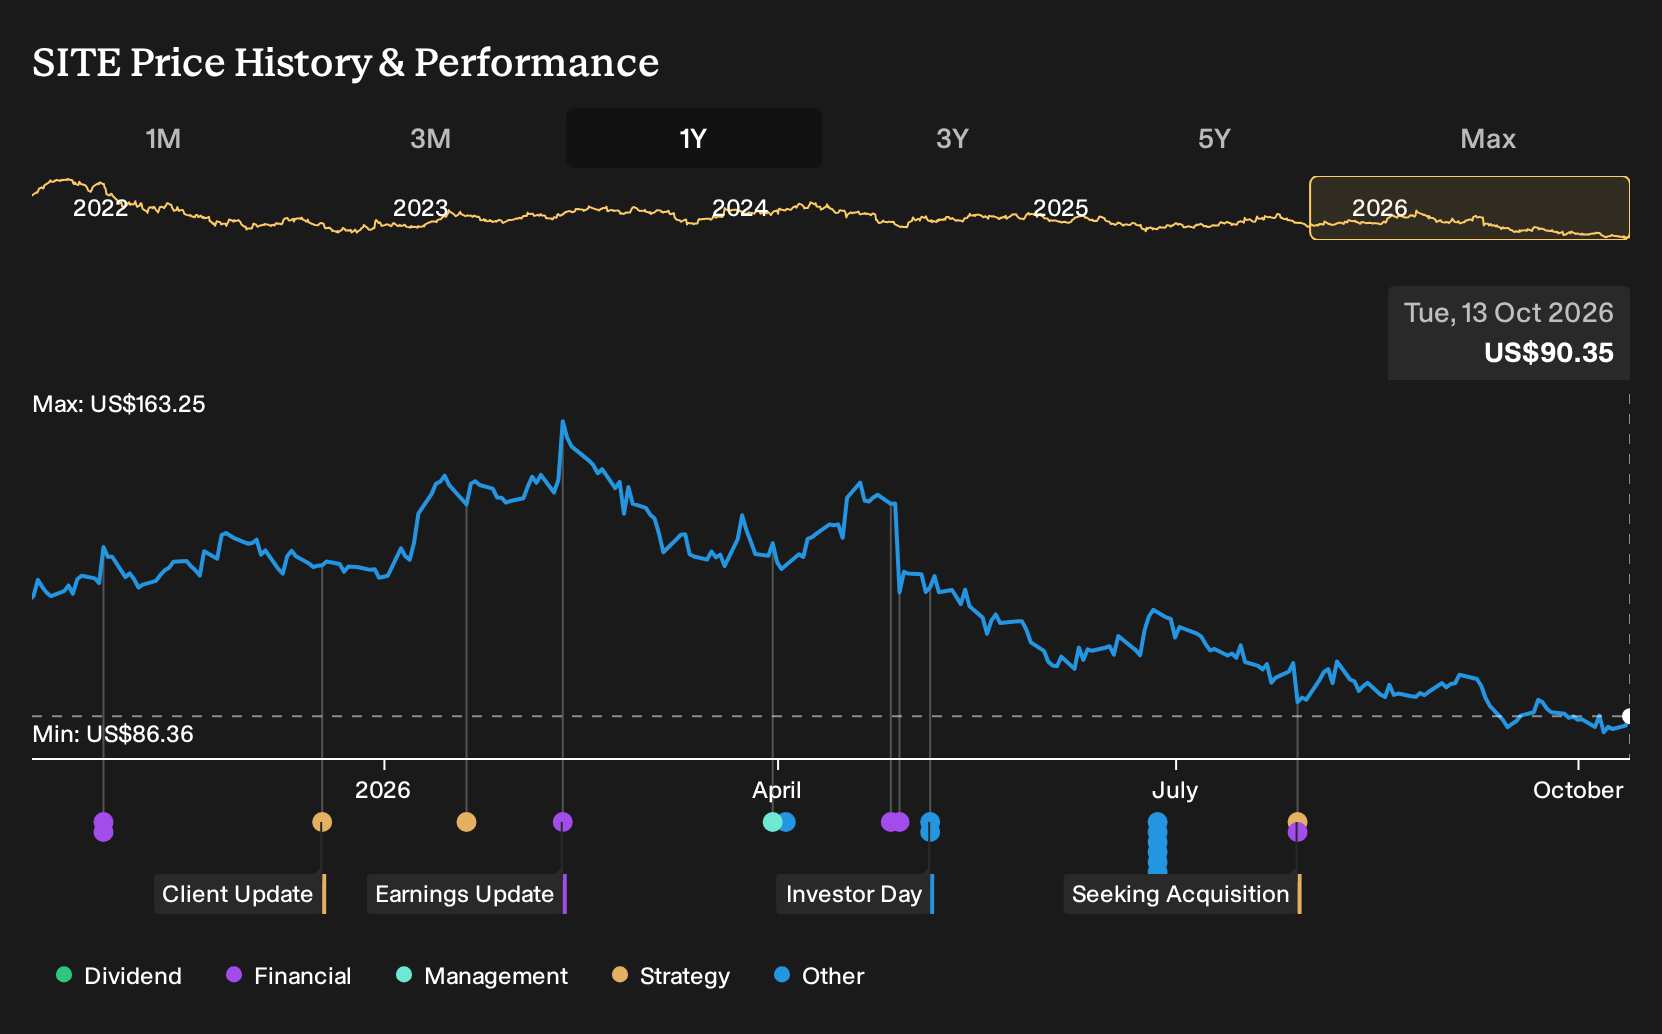
Exploring Other Perspectives
For SiteOne Landscape Supply, the bullish twist in the story is EBITDA margin optimism. The most upbeat analysts were already penciling in earnings of about US$319.3m by 2029 on roughly 6.8% yearly revenue growth, well above the consensus US$258.8m. The latest digital and M&A update could prompt those narratives to shift again, so consider this a cue to compare several viewpoints before deciding what feels reasonable.
Explore 3 other SiteOne Landscape Supply fair value estimates, including one that suggests as much as 77% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SiteOne Landscape Supply research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for SiteOne Landscape Supply. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SiteOne Landscape Supply's overall financial health at a glance.
Looking for more investment ideas beyond SiteOne Landscape Supply?
Once you have a view on SiteOne Landscape Supply, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income needs, or focus on fundamentals. The Simply Wall St Screener lets you quickly sort through stocks that share similar qualities, then filter down to the ones that actually fit your portfolio plan.
- If capital preservation and steadier profiles matter to you, start with companies that screen as more resilient by reviewing 32 resilient stocks with low risk scores that may better match a cautious approach.
- For investors who care most about business strength and financial footing, consider broadening your research to a list of solid balance sheet and fundamentals (25 results) so you can compare balance sheet quality alongside SiteOne.
- If you are hunting for opportunities the broader market may not be paying attention to yet, scan our 20 high quality undiscovered gems and see which stories deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com