
Amazon Just Spent $7 Billion to Break Nvidia’s Weak Spot Wide Open
If Amazon’s (AMZN) chips unit were a standalone company selling to outside buyers, CEO Andy Jassy estimates it would bring in about $50 billion a year. He believes that would rank it among the three largest data center chip businesses in the world. That context helps explain why Amazon is reportedly willing to spend around $7 billion on Decart, an Israeli AI startup, according to The Wall Street Journal. No deal has been finalized yet.
Trainium’s pitch is simple. It offers more AI performance for every dollar spent. Jassy says Trainium2 delivers about 30% more performance per dollar than comparable GPUs, and Trainium3 improves on that by another 30% to 40%. Customers have clearly noticed. Amazon has more than $225 billion in Trainium revenue commitments, and it’s even discussing selling the chips directly to companies outside AWS. The hurdle is that most AI software was built for Nvidia (NVDA). Moving it to a different chip takes time and engineering work, which keeps many customers loyal. That’s where I think Decart fits in. Its optimization software is designed to run AI models efficiently across different chips, which could lower that switching cost for Amazon’s customers.
The price does raise questions. Decart’s valuation was about $4 billion in May, and in September, Anthropic decided against buying it at roughly $6 billion after doing its own review. Amazon is offering more than both. In my view, though, if Decart helps even a small share of Nvidia users try Trainium, the payoff could easily outweigh the cost.
About Amazon Stock
Amazon is a multinational technology company best known for its online shopping platform. It also operates several other businesses. The North America segment offers retail sales of consumer products, including from sellers, advertising, and subscriptions through online and physical stores. The Amazon Web Services segment provides cloud computing services such as data storage, databases, and computing power to businesses, startups, governments, and universities around the world. Founded in 1994, the company is headquartered in Seattle, Washington.
Over the past year, AMZN has climbed almost 19%, slightly outperforming the S&P 500’s ($SPX) gain of 17% during the same period. The stock has benefited from strong growth in Amazon Web Services, rising demand for AI infrastructure, and improving profitability across its retail and advertising business. Investors are also betting that the company’s heavy AI investments will support future earnings growth. On a year-to-date basis, it gained almost 16%, outperforming the S&P 500’s gain of 13%.
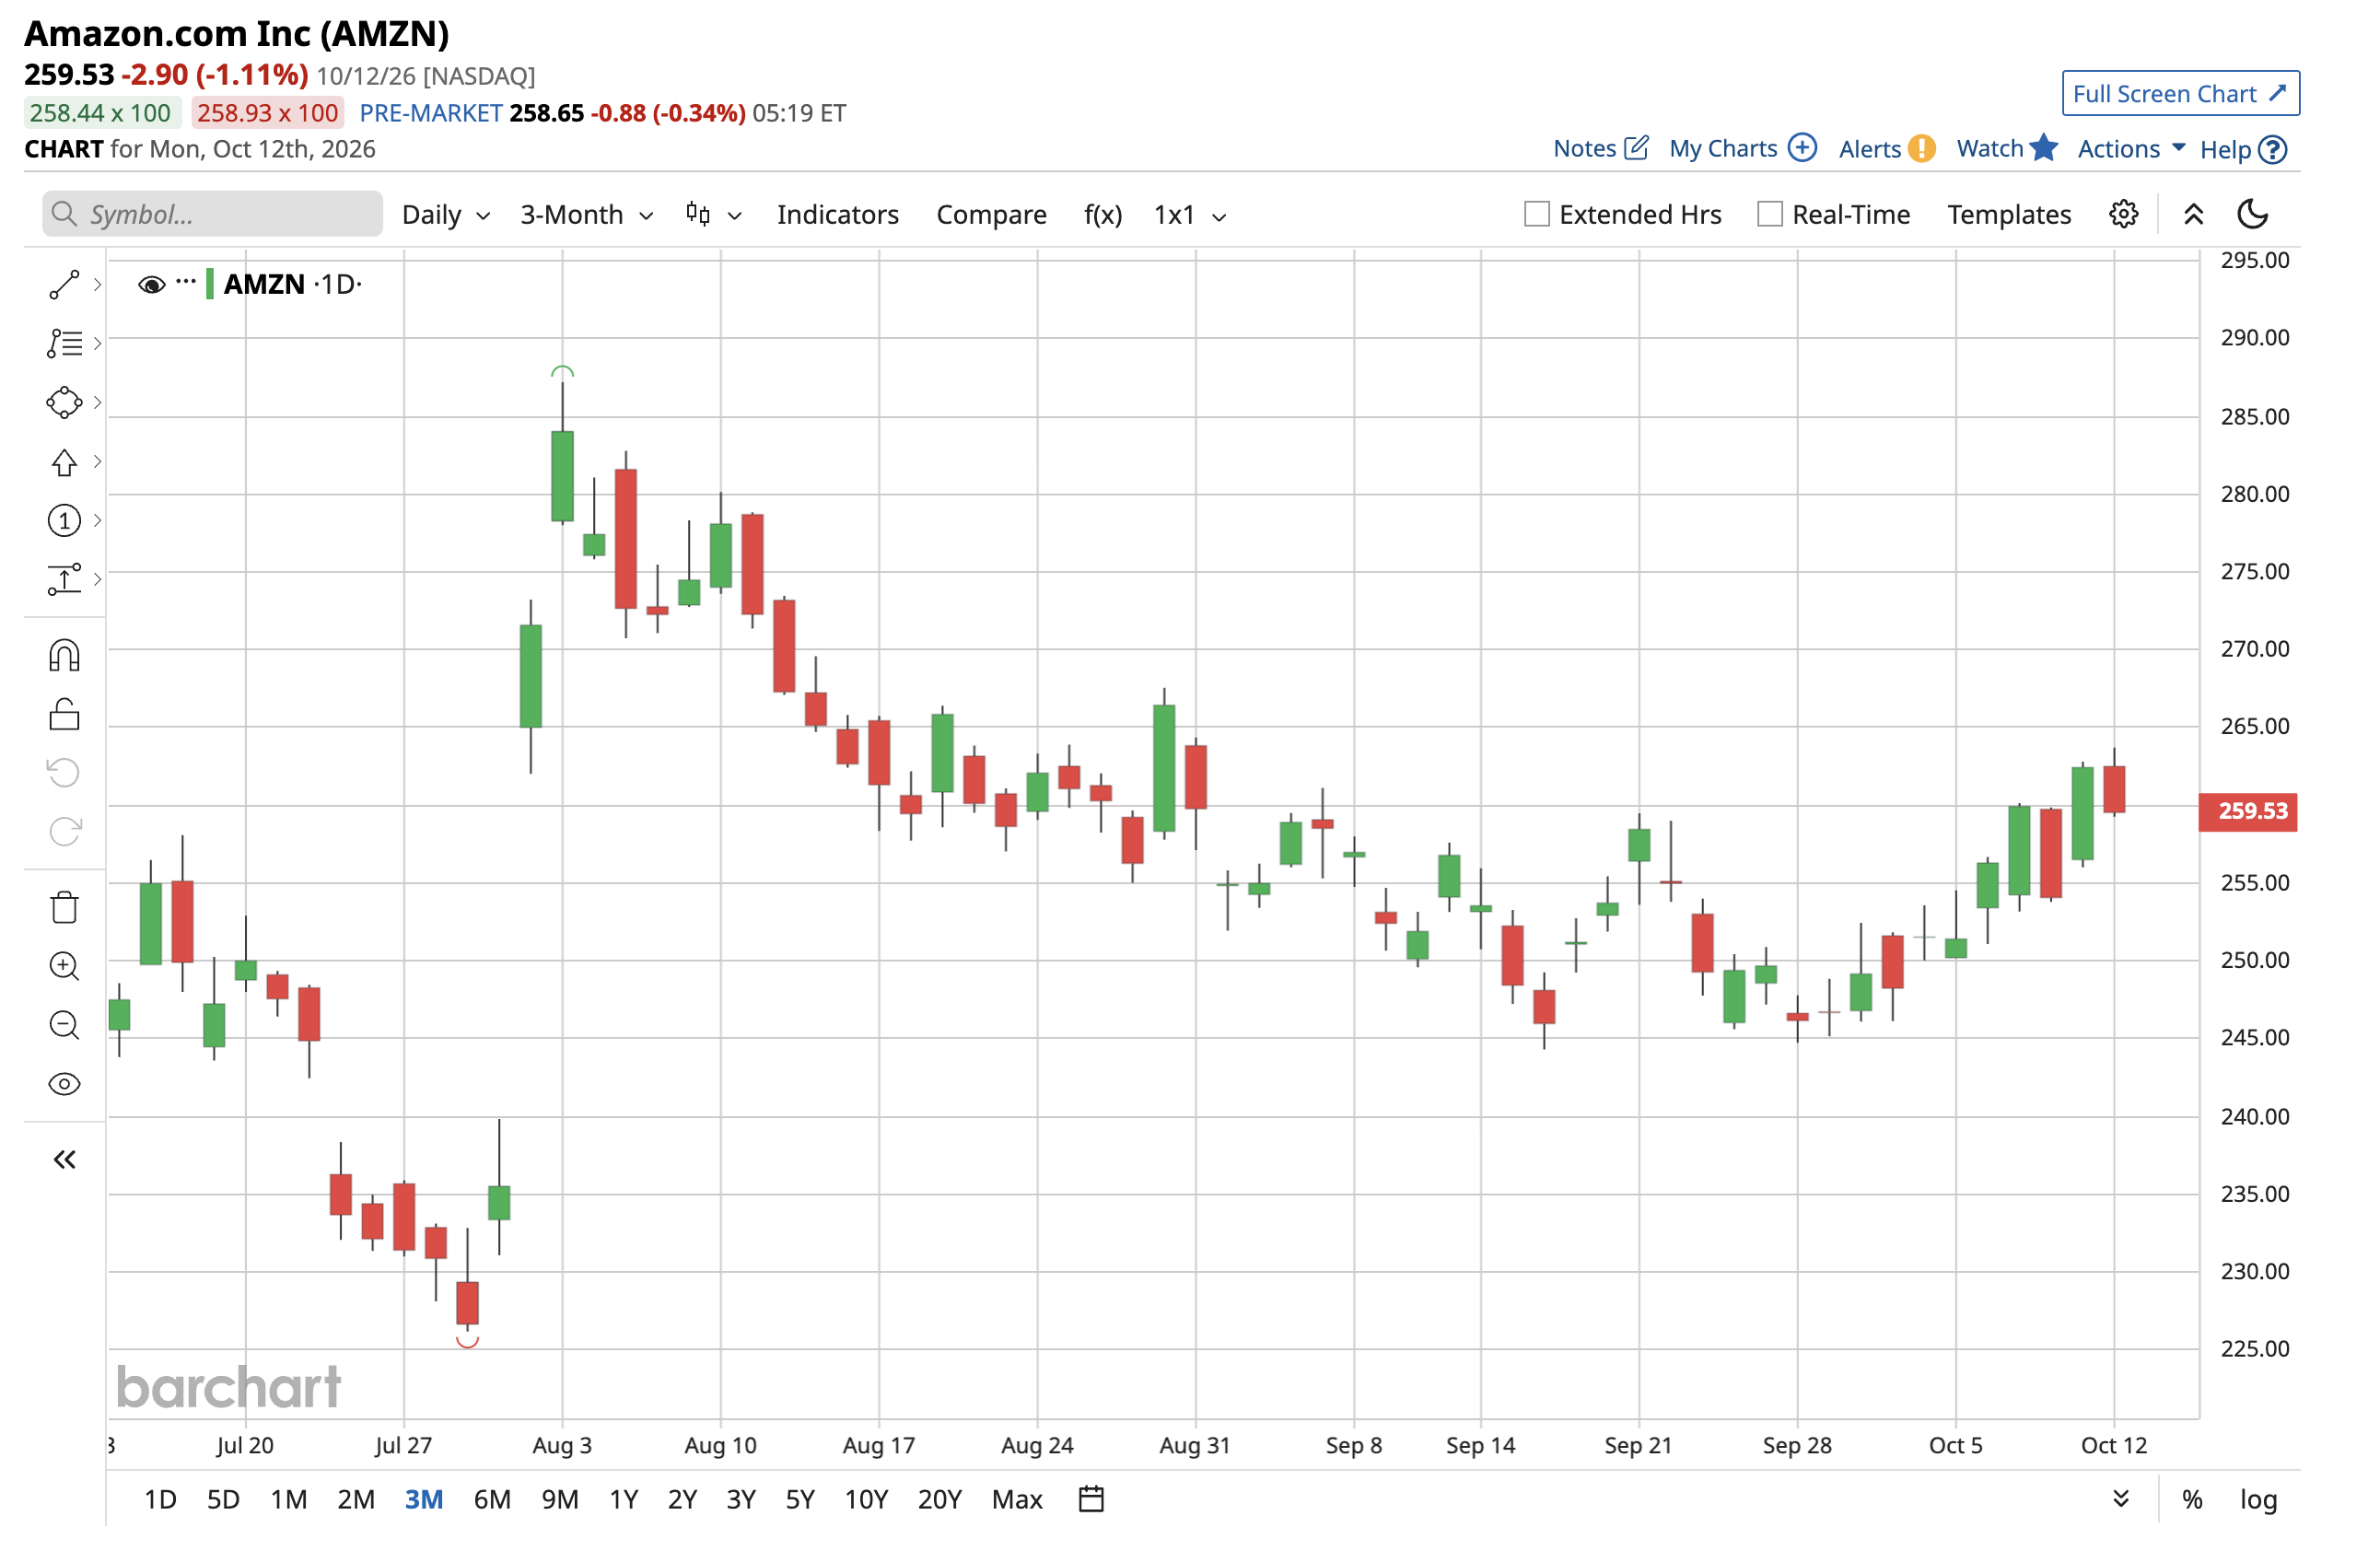
Amazon’s valuation looks unusual at first glance. The forward non-GAAP P/E of 31.59x sits about 80% below its five-year average of 158.90x. That average is misleading, though. Amazon generated a loss in 2022, which pushed its historical multiple to extreme levels. The forward Price-to-sales ratio is a better guide. At 3.42x, it sits about 19% above its five-year average of 2.88x, indicating a modest premium. Year-over-year earnings comparisons are also unreliable right now. Large non-cash gains on Amazon's Anthropic stake have lifted 2026 profits, so analysts' estimates show EPS falling 18% in 2027. Amazon carries $251.64 billion in debt and lease obligations against $122.99 billion in cash, leaving it roughly $129 billion in net debt. Over the past year, though, the company generated $161 billion in operating cash flow, so a $7 billion deal looks easy to absorb. For investors, the bigger question is whether deals like Decart help Trainium keep up its rapid growth.
Amazon’s Q3 Outlook Tests Whether Strong AI Demand Can Sustain Growth
Amazon reported its second-quarter fiscal 2026 earnings on July 30. It reported stronger-than-expected results, with revenue of $200.6 billion, ahead of Wall Street estimates of $196.16 billion. Earnings per share came in at $5.75, comfortably beating the Wall Street consensus of $1.81. The company’s revenue rose 20% from a year earlier, and operating income climbed 43% to $27.5 billion. North America segment revenue was $116.2 billion, up 16% year-over-year, while International revenue was $42.2 billion, up 15% year-over-year, excluding foreign exchange. AWS revenue was $42.2 billion, up 36.7% year-over-year. The company’s capital expenditures were $53.1 billion, mainly for AWS and generative AI.
Looking forward to the third quarter, Amazon expects net sales between $197 billion and $202 billion. Operating income is expected to be between $22.5 billion and $26.5 billion. AMZN also raised its full-year 2026 cash capital expenditures forecast to about $220 billion from $200 billion. The increase reflects higher memory costs and continued investment in AI and cloud infrastructure. Morgan Stanley analyst Brian Nowak asked whether data center spending could slow in 2027 and whether Amazon might sell its Trainium AI chips to outside data centers. CEO Andy Jassy said much of Amazon’s data center capacity for 2028 has already been reserved. He also said the company may sell Trainium chips to third-party data centers in the future.
What Do Analysts Expect for AMZN Stock?
Wall Street remains bullish on Amazon stock. Recently, Tigress Financial analyst Ivan Feinseth raised the firm’s price target from $315 to $385 and kept a Buy rating. The analyst believes the company’s AI investments are accelerating AWS and AI growth, increasing advertising revenue, and encouraging more frequent purchases. These investments are also helping the company expand its operating margins. Similarly, Needham analyst Laura Martin reiterated a Buy rating and assigned a price target of $300.
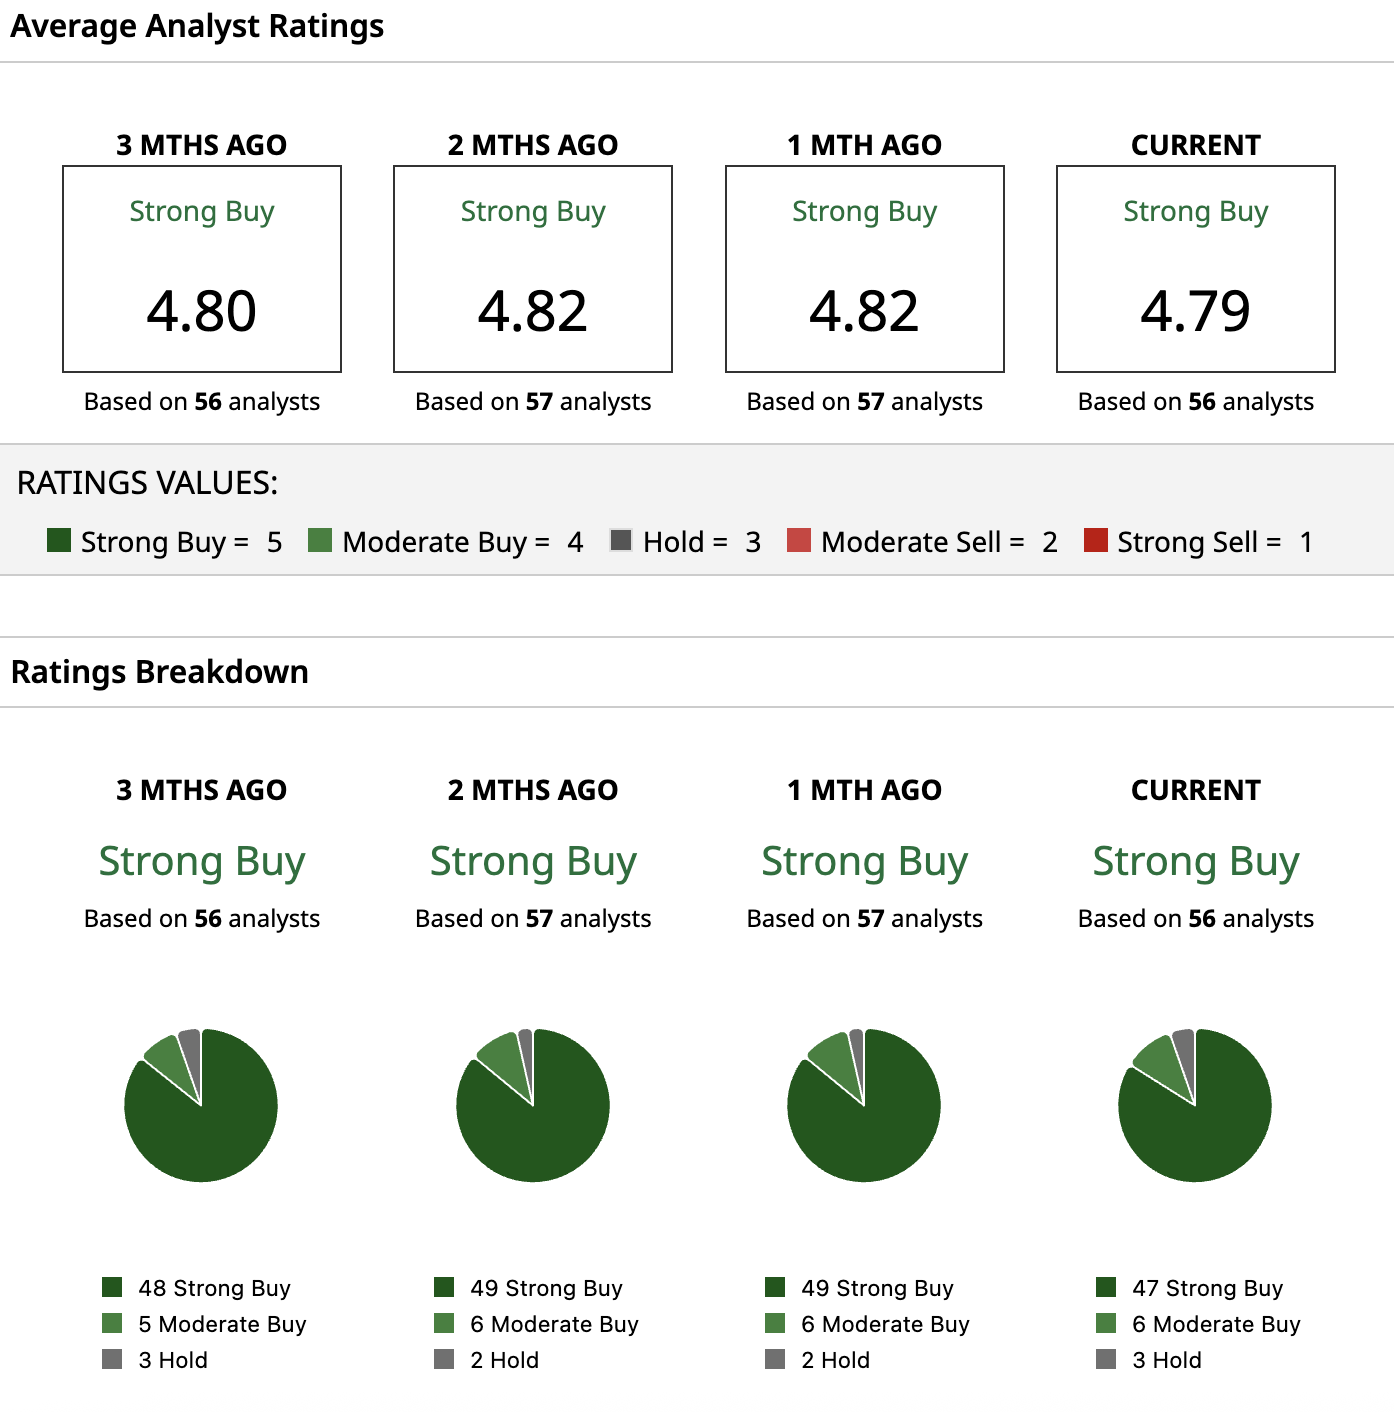
Based on 56 Wall Street analysts covering the stock, AMZN holds a consensus “Strong Buy” rating. Out of those, 47 have a “Strong Buy” rating, six have a “Moderate Buy” rating, and three have a “Hold” rating. The median price target of $328 reflects an additional 25% upside from the current level. The high price target of $405 implies 54% upside from the current share price.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.