
Constellation Energy (CEG) Just Gave Investors Something To Think About
Constellation Energy (CEG) is back in focus after Alphabet’s Google agreed to a 20 year clean power partnership tied to 890 megawatts of new nuclear capacity and US$4.3b in planned investments.
Against that backdrop, Constellation Energy’s recent run tells a mixed story. The stock has a 90 day share price return of 14.6% and a 30 day gain of 3.88%. Yet the year to date share price return is down 19.24% and the 1 year total shareholder return has fallen 23.65%, while the 3 year total shareholder return of about 2.6x hints that investors with a longer view have seen very different results from those focused on this year’s pullback.
Scan the nuclear and grid upgrade story beyond Constellation Energy by focusing on hand picked 16 nuclear energy infrastructure stocks that are positioned to support long term data center and AI demand.
Constellation Energy now combines long contracts, fresh nuclear investment and a sharp pullback in the share price. Does that mix still skew the risk reward toward buyers at today’s valuation?
Most Popular Narrative: 15.5% Undervalued
Against Constellation Energy’s last close at $295.79, the most followed narrative pins fair value at $350. That gap frames the Google deal, the recent share price pullback, and the long contract pipeline as the core of the debate.
The story from here is straightforward. Monetize the nuclear scarcity advantage through long-duration contracts with investment-grade customers (Microsoft for the Crane/Three Mile Island restart, Meta for Clinton, Walmart, and ~920 MW of additional nuclear PPAs signed in Q2 2026 alone, average duration ~18.5 years), restart Crane in 2027, pursue uprates and license extensions (Ginna and Nine Mile Point filings already submitted), and use the flexible gas/geothermal assets for reliability and co-located data-center opportunities.
See why 24 investors see Constellation Energy as 15% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, Constellation Energy’s story can break if nuclear operations stumble or regulators slow approvals, which would undercut the case for long contracts and scarcity.
Find out about the key risks to this Constellation Energy narrative.
Another View: What Constellation Energy’s P/E Is Saying
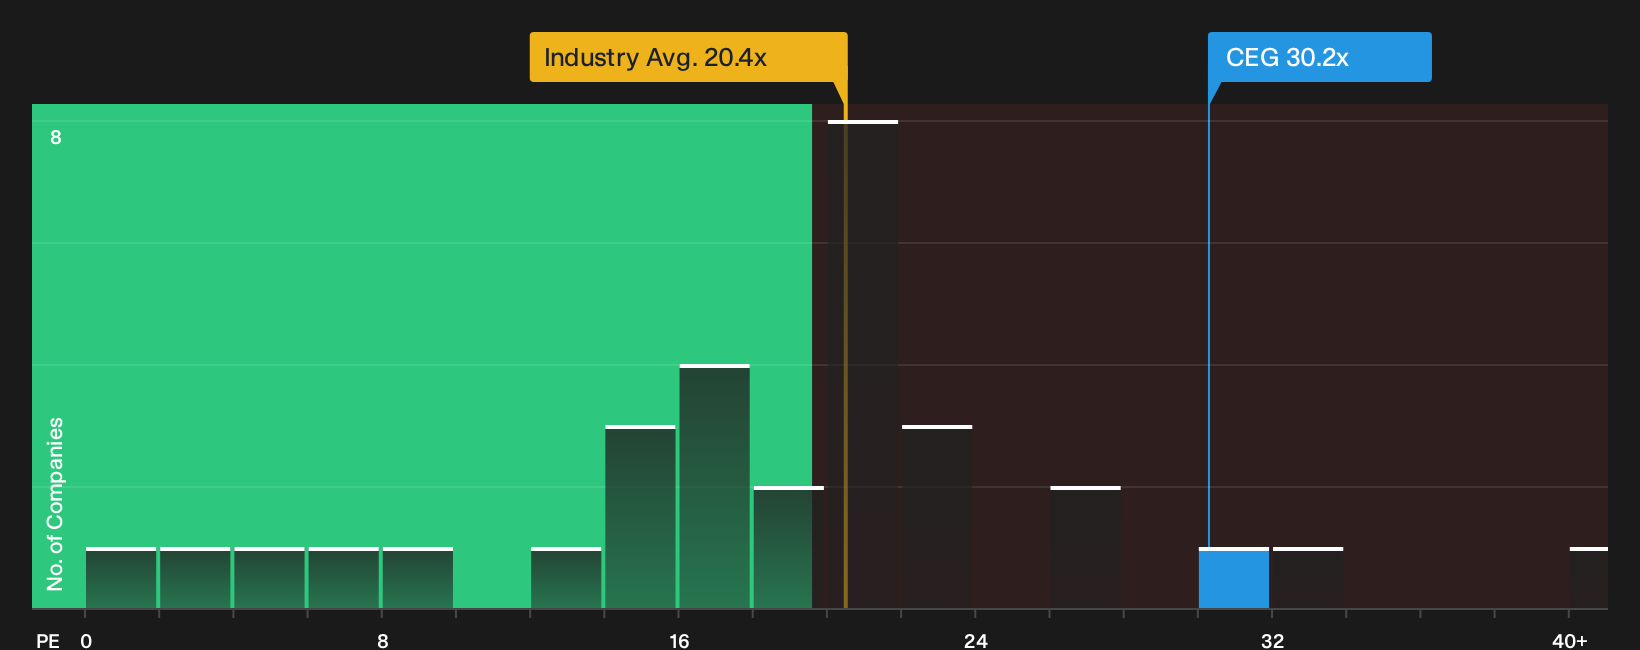
Our fair value estimate points to upside, yet Constellation Energy’s current P/E of 30.2x is higher than both the Electric Utilities industry at 20.4x and the peer group at 19.7x. The fair ratio sits at 30.4x. Is that slim gap enough cushion if earnings or sentiment cool?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed reactions to Constellation Energy’s recent moves are clear, so move quickly, review the data yourself, and weigh both sides of the argument. To see a concise snapshot of the key risks and optimistic signals investors are talking about, start with these 3 key rewards and 2 important warning signs
Looking for more Constellation Energy sized ideas?
If you stop with Constellation Energy, you miss the rest of the opportunity set. Use the Simply Wall Street Screener to pressure test your next moves across sectors.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that can help anchor a more defensive part of your portfolio.
- Hunt for mispriced quality by reviewing a focused 32 high quality undervalued stocks that filters for fundamentals first and keeps speculation firmly in the back seat.
- Build a smoother ride through market swings by weighing 32 resilient stocks with low risk scores that screens for lower volatility traits and financial strength in a single view.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com