
Here's Why We're Watching Aware's (NASDAQ:AWRE) Cash Burn Situation
Just because a business does not make any money, does not mean that the stock will go down. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So should Aware (NASDAQ:AWRE) shareholders be worried about its cash burn? In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
How Long Is Aware's Cash Runway?
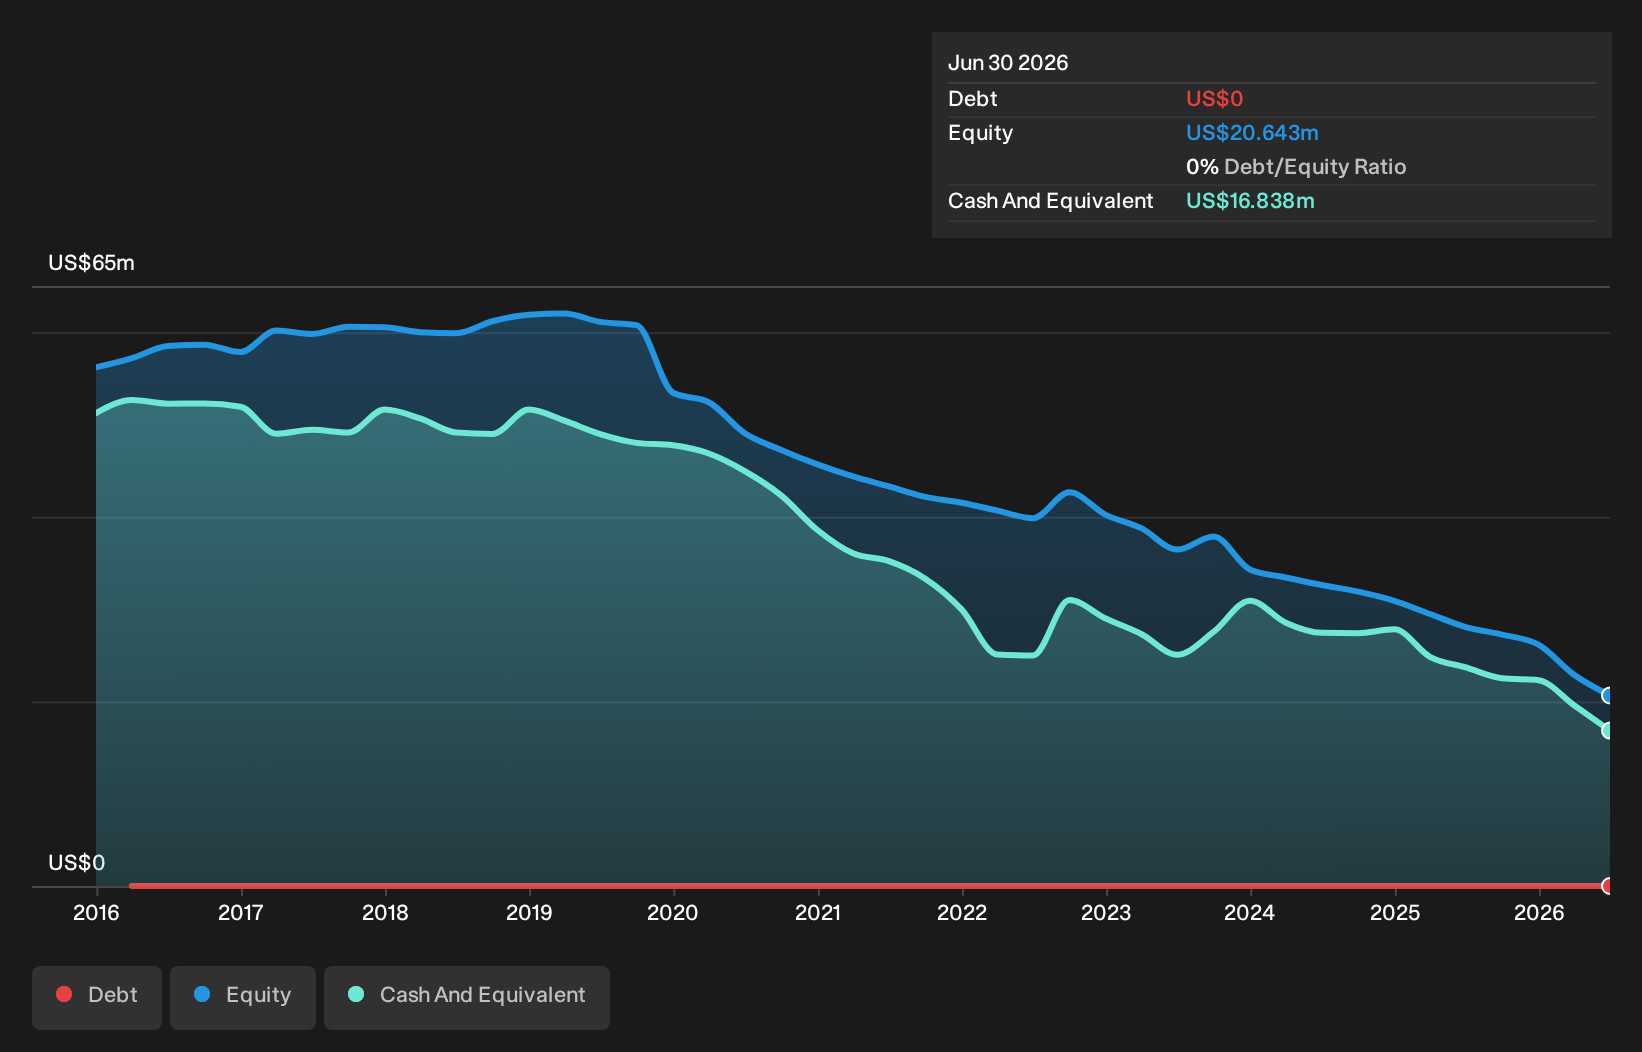
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Aware last reported its June 2026 balance sheet in July 2026, it had zero debt and cash worth US$17m. In the last year, its cash burn was US$6.9m. So it had a cash runway of about 2.5 years from June 2026. That's decent, giving the company a couple years to develop its business. The image below shows how its cash balance has been changing over the last few years.
View our latest analysis for Aware
How Well Is Aware Growing?
Aware boosted investment sharply in the last year, with cash burn ramping by 63%. On top of that, the fact that operating revenue was basically flat over the same period compounds the concern. Considering both these metrics, we're a little concerned about how the company is developing. Of course, we've only taken a quick look at the stock's growth metrics, here. This graph of historic earnings and revenue shows how Aware is building its business over time.
How Easily Can Aware Raise Cash?
While Aware seems to be in a fairly good position, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Aware's cash burn of US$6.9m is about 31% of its US$22m market capitalisation. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
Is Aware's Cash Burn A Worry?
On this analysis of Aware's cash burn, we think its cash runway was reassuring, while its increasing cash burn has us a bit worried. Even though we don't think it has a problem with its cash burn, the analysis we've done in this article does suggest that shareholders should give some careful thought to the potential cost of raising more money in the future. Separately, we looked at different risks affecting the company and spotted 2 warning signs for Aware (of which 1 makes us a bit uncomfortable!) you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.