
Johnson & Johnson (JNJ) Stock Dropped, What Is Behind The Latest Attention?
Johnson & Johnson (JNJ) just paired a stronger full year outlook with an earnings beat, yet the stock sold off as weak MedTech performance and a large talc litigation charge grabbed investor attention.
That sharp 5.7% drop in the latest trading session sits against a much stronger backdrop, with Johnson & Johnson posting a year to date share price return of 19.9% and a 1 year total shareholder return of 33.2%, supported by drug data like TREMFYA and ICOTYDE, the Firefly Bio acquisition and fresh Q3 guidance. However, MedTech setbacks, talc litigation costs and new geopolitical risks have cooled near term momentum.
Compare Johnson & Johnson's mixed reaction to its outlook upgrade with other healthcare stocks that combine strong pipelines and resilient balance sheets using the list of solid balance sheet and fundamentals (25 results)
After a 5.7% pullback leaves Johnson & Johnson trading at about $248 a share, the real fork in the road is simple: treat this as an early entry or wait for MedTech and litigation clouds to clear first.
Most Popular Narrative: 8% Undervalued
On the most followed narrative, Johnson & Johnson is assessed with a fair value of $270.59 versus a last close of $248.61. The current pullback therefore sits against a modest implied discount that analysts tie to specific growth and risk assumptions.
The analysts have a consensus price target of $270.59 for Johnson & Johnson based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $305.0, and the most bearish reporting a price target of just $190.0.
See why 509 investors see Johnson & Johnson as 8% undervalued.
Result: Fair Value of $270.59 (UNDERVALUED)
Still, the narrative can crack if talc litigation outcomes hit cash flows harder than expected, or if MedTech restructuring drags longer on profitability.
Find out about the key risks to this Johnson & Johnson narrative.
Another View: Johnson & Johnson Through Market Multiples
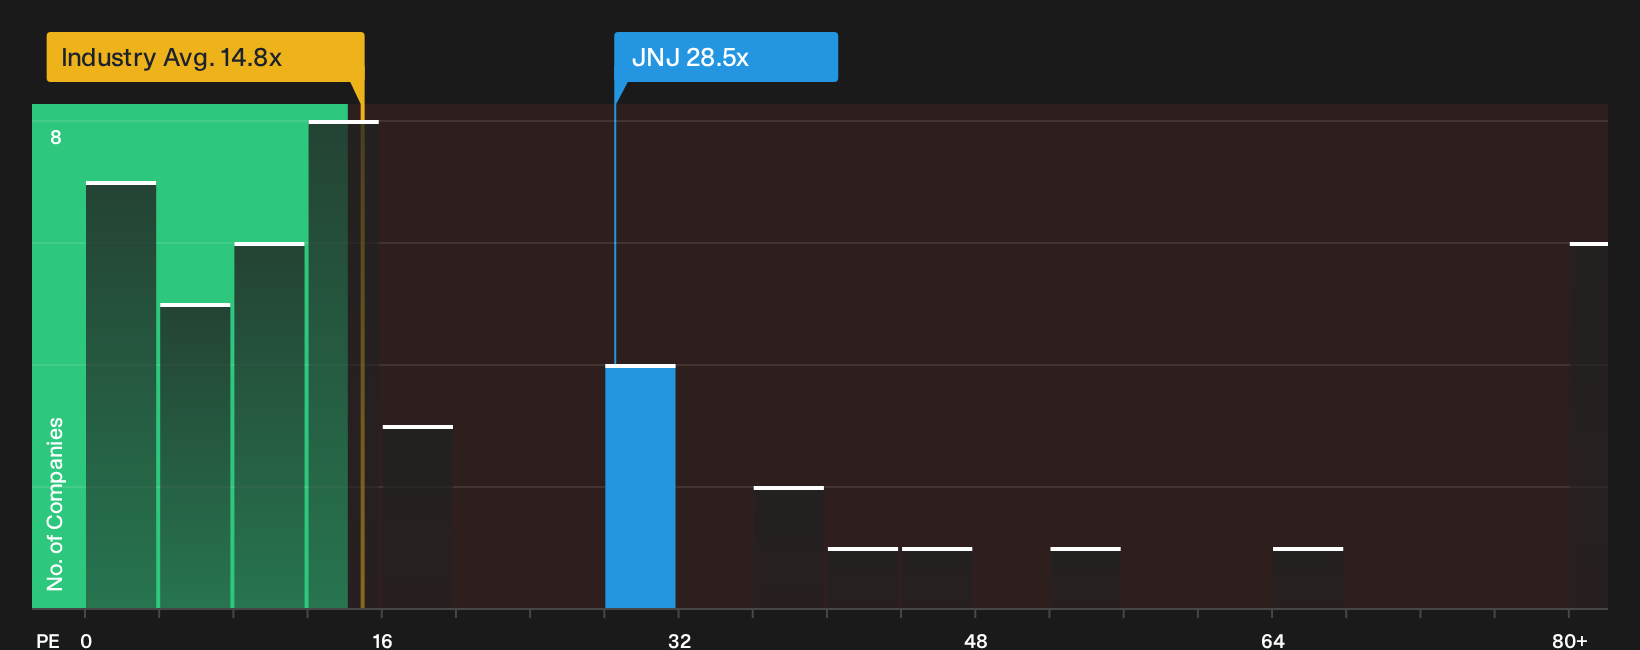
The story looks different once you leave fair value models and focus on what investors are actually paying today. Johnson & Johnson trades on a P/E of 28.5x, which is almost double the broader US Pharmaceuticals group at 14.8x and well below a 49.8x peer average.
The fair ratio for Johnson & Johnson sits at 38.8x. This implies the current P/E could either compress toward the sector or drift closer to that higher marker over time. For anyone watching this pullback, the question is simple: Is that gap a cushion or a risk if sentiment turns.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Johnson & Johnson can blur the picture, so move quickly, review the full risk and reward balance, and weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Johnson & Johnson?
If Johnson & Johnson has your attention, do not stop there. Put this move in context by lining it up against other high quality opportunities.
- Target potential mispricings by scanning for high quality companies trading below their estimated worth through the 32 high quality undervalued stocks.
- Strengthen your income stream by checking out dependable payers with robust yields using the 8 dividend fortresses.
- Reduce portfolio stress by focusing on sturdier businesses that show resilient finances via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com