
BetMGM Guidance Reaffirmed Could Matter For Autotrader Shares (LSE:AUTO)
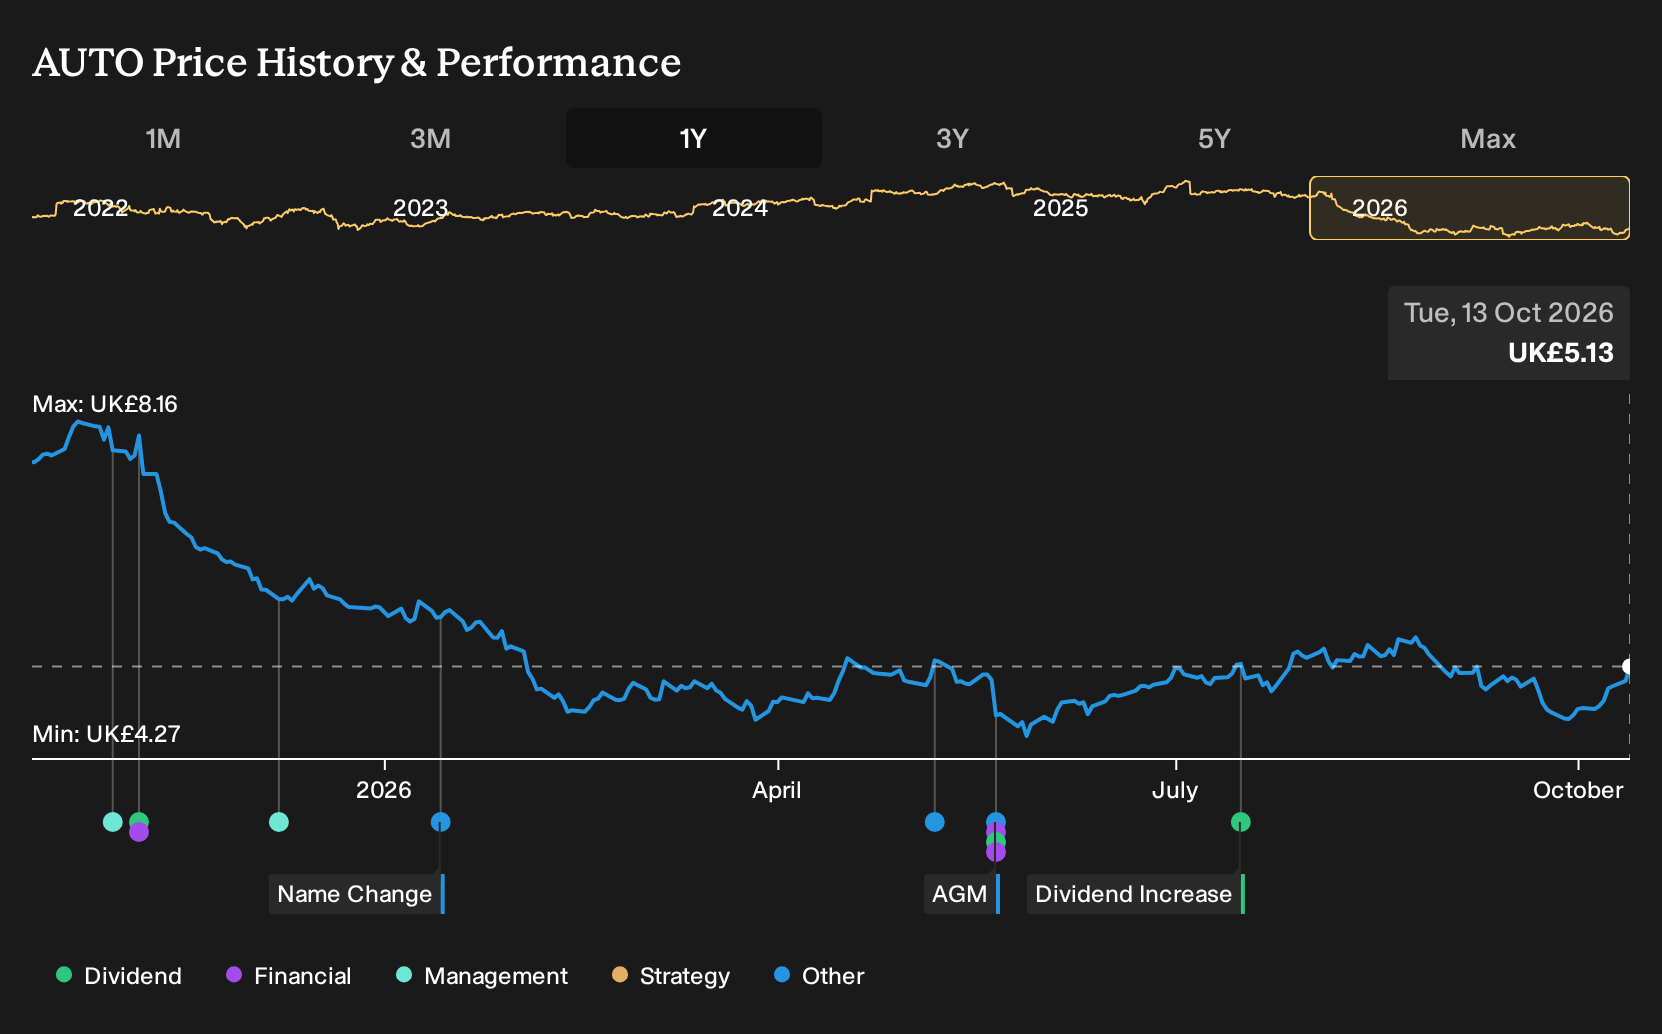
- Autotrader Group has recently benefited from positive sentiment after BetMGM, its joint venture with MGM Resorts, reaffirmed full year guidance, which has supported confidence in that partnership following the update earlier this week.
- The BetMGM update highlights how non core, partnership based earnings streams can influence how investors think about Autotrader Group’s broader business mix and resilience.
- This article examines how Autotrader Group’s investment narrative is influenced by BetMGM’s reaffirmed guidance and the current rise in investor confidence.
Scan how sentiment around Autotrader Group compares to other companies seeing renewed interest and potential catalysts by reviewing the hand picked 5 high quality undiscovered gems.
Autotrader Group Investment Narrative Recap
To own Autotrader Group, you need to be comfortable with a high margin digital platform that still depends heavily on UK car retailers and manufacturers. The near term bull case leans on continued adoption of tools like Deal Builder and Co Driver to keep average revenue per retailer resilient as forecourt numbers and stock levels face pressure. The biggest short term swing factor is whether retailers keep paying up for higher quality digital leads.
The main operational risk right now is that softer retailer stock, potential digital services tax costs and ongoing Autorama losses chip away at those rich margins faster than new products can offset. The BetMGM guidance and share price move help sentiment, but they do not change the core thesis, which still rests on execution in UK automotive and disciplined capital allocation.
The most relevant backdrop to the current optimism is Autotrader data on Chinese car manufacturers driving virtually all growth in Britain’s new car registrations this year. This points to a market where overall registrations surprise on the upside while non Chinese brands are broadly flat. That mix shift matters for how advertising and lead budgets get allocated across the platform.
For you as a shareholder, the operational question is whether Autotrader Group can keep monetising traffic and tools across both Chinese and non Chinese brands while retailers manage ZEV mandate targets and year end pushes from manufacturers. Strong products such as Deal Builder and Co Driver give the business levers to pull, but retailer stress, stock drag on ARPR and any mis steps at Autorama remain key risks.
Autotrader Group is currently framed around analyst expectations that revenues reach £716.5 million and earnings come in at £325.7 million by 2029, based on an assumed 4.7% yearly revenue growth rate and an earnings increase of about £31.8 million from £293.9 million today.
Uncover why Autotrader Group's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Autotrader Group’s AI rollout as the real catalyst, not BetMGM. Before this news, the bullish camp was pencilling in around £765.3 million of revenue and £363.3 million of earnings by 2029, far above consensus. That gap shows how widely views can differ, so it is worth exploring several angles before deciding how this latest update might reshape the story.
Explore 5 other Autotrader Group fair value estimates, including one that suggests as much as 50% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Autotrader Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Autotrader Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Autotrader Group's overall financial health at a glance.
Looking for more Autotrader Group style investment ideas?
If the Autotrader Group story has you thinking about what else might fit your portfolio, it can help to scan a wider field of opportunities that share traits you care about such as quality, resilience or income potential.
- For investors who want a margin of safety and solid fundamentals, review a curated set of companies trading below estimated value through the 8 high quality undervalued stocks.
- If capital preservation sits high on your priority list, focus on stability first by checking out a 4 resilient stocks with low risk scores that screens for resilient balance sheets and lower risk scores.
- For income focused portfolios, use a targeted filter to zero in on reliable payers with meaningful yields via the 2 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com