
TSX Penny Stocks To Consider In October 2026
As the Canadian market continues to navigate a resilient economy amidst a maturing bull market, investors are reflecting on the unique characteristics that define this period of growth. Despite rising correction risks and ongoing economic questions, opportunities remain for those willing to explore less traditional investment avenues. Penny stocks, often seen as relics from past trading eras, still offer potential by providing access to smaller or newer companies with strong financials and growth prospects. In this context, we will examine three penny stocks that stand out for their financial strength and potential in today's evolving market landscape.
We're going to check out a few of the best picks from our screener tool.
Getchell Gold (CNSX:GTCH)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Getchell Gold Corp. is a junior resource exploration company focused on identifying, acquiring, and exploring precious and base metals properties in Canada and the United States, with a market cap of CA$52.04 million.
Operations: Getchell Gold Corp. currently does not have any reported revenue segments.
Market Cap: CA$52.04M
Getchell Gold Corp., a pre-revenue junior resource exploration company, has recently closed a private placement raising CA$300,000. The company reported a net loss of CA$6.96 million for the fiscal year ending March 2026 and faces auditor concerns about its ability to continue as a going concern. Despite this, Getchell Gold's Preliminary Economic Assessment (PEA) for the Fondaway Canyon project in Nevada shows promising potential with an estimated after-tax NPV of US$905 million at a gold price of US$3,200/oz and plans for an open pit mining operation over 10 years. However, it currently only has cash runway for seven months without further capital raises.
- Click to explore a detailed breakdown of our findings in Getchell Gold's financial health report.
- Gain insights into Getchell Gold's past trends and performance with our report on the company's historical track record.

NTG Clarity Networks (TSXV:NCI)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: NTG Clarity Networks Inc., along with its subsidiaries, offers network, telecom, IT, and infrastructure solutions to medium and large network service providers across Canada, North America, Iraq, Saudi Arabia, Egypt, and Oman with a market cap of CA$15.12 million.
Operations: The company's revenue is primarily generated from its operations in Canada, contributing CA$38.47 million, and Egypt, contributing CA$1.36 million.
Market Cap: CA$15.12M
NTG Clarity Networks Inc., with a market cap of CA$15.12 million, has shown revenue growth but faces challenges in earnings consistency and volatility. Recent executive changes include the appointment of Ahmed Hashem to the Board, bringing extensive expertise in telecom and IT sectors. Despite moderate revenue increases—sales reached CA$20.08 million for Q2 2026—the company withdrew its fiscal 2026 guidance due to regional economic uncertainties impacting project work continuity. While NTG's short-term assets comfortably cover liabilities, negative operating cash flow raises concerns about debt coverage, though interest payments are well managed with EBIT covering them 17 times over.
- Take a closer look at NTG Clarity Networks' potential here in our financial health report.
- Gain insights into NTG Clarity Networks' outlook and expected performance with our report on the company's earnings estimates.

SPARQ Systems (TSXV:SPRQ)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: SPARQ Systems Inc. designs, manufactures, and sells single-phase microinverters for residential and commercial solar electric applications in Canada, with a market cap of CA$106.59 million.
Operations: The company's revenue is derived entirely from its Electric Equipment segment, totaling CA$3.42 million.
Market Cap: CA$106.59M
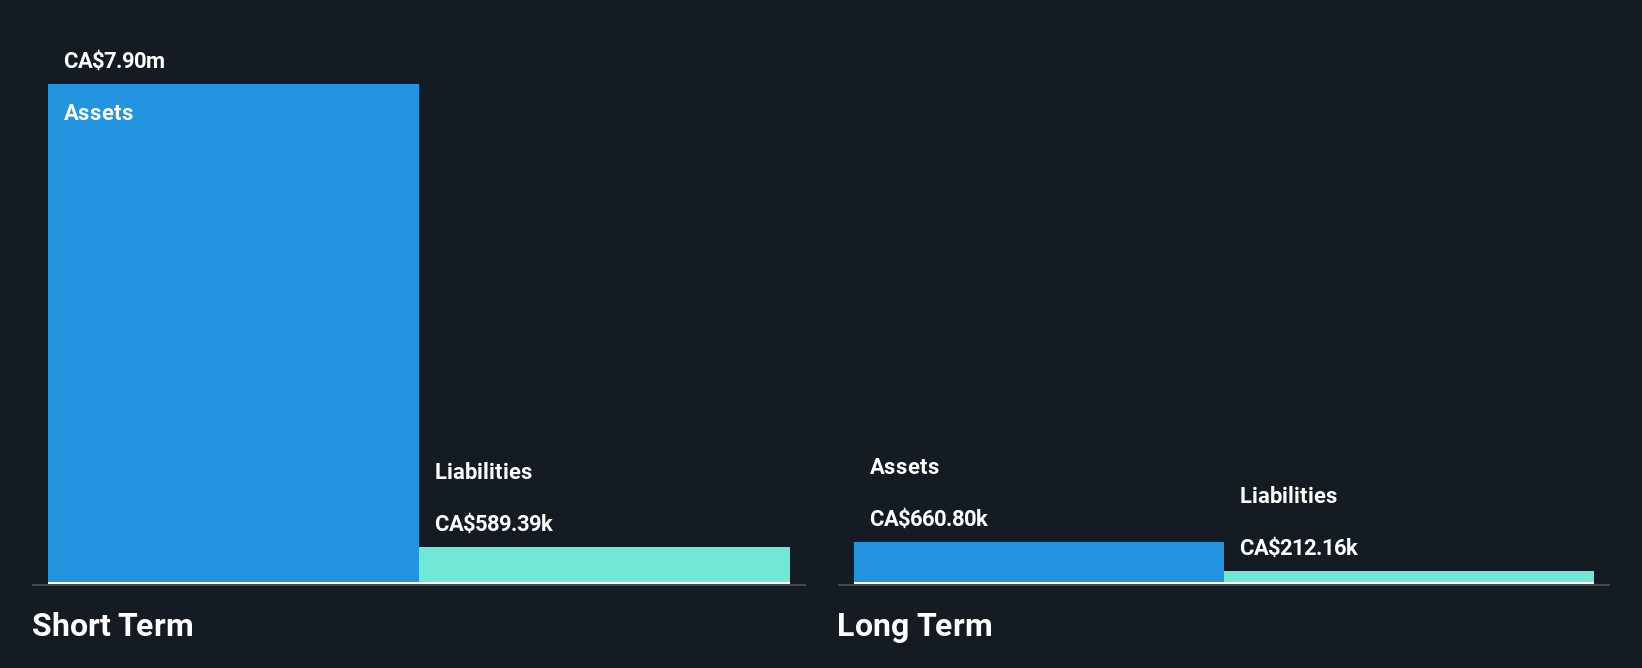
SPARQ Systems Inc., with a market cap of CA$106.59 million, is navigating the penny stock landscape with some financial strengths and challenges. The company reported second-quarter sales of CA$0.98 million, marking significant growth from the previous year, yet remains unprofitable with a net loss of CA$1.28 million. Despite this, SPARQ has no debt and a strong cash position that covers its short-term liabilities comfortably. Revenue is forecast to grow significantly at 167.82% per year, though current revenue levels are not considered meaningful at CA$3 million annually. Management tenure data is insufficient to assess experience accurately.
- Get an in-depth perspective on SPARQ Systems' performance by reading our balance sheet health report here.
- Examine SPARQ Systems' earnings growth report to understand how analysts expect it to perform.
Taking Advantage
- Unlock more gems! Our TSX Penny Stocks screener has unearthed 337 more companies for you to explore.Click here to unveil our expertly curated list of 340 TSX Penny Stocks.
- Seeking Other Investments? Uncover 25 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com