
How Investors May Respond To GigaCloud Stock After Earnings Estimate Upgrades
- GigaCloud Technology has recently drawn strong attention after analysts revised earnings estimates upward for the current quarter and the coming fiscal years, pointing to changing expectations for how its B2B ecommerce platform and logistics operations might convert demand into profits.
- The sharp upgrades to profit forecasts highlight how closely GigaCloud Technology's margin story and platform efficiency are being watched as its cross border logistics and marketplace scale evolve.
- We will now examine how GigaCloud Technology's sharply higher earnings estimates could affect the broader investment narrative around its platform.
Scan how analysts are re-rating platform-driven businesses like GigaCloud Technology by reviewing our hand-picked list of 20 high quality undiscovered gems that are starting to attract fresh earnings attention.
GigaCloud Technology Investment Narrative Recap
To own GigaCloud Technology, you need to be comfortable with a thesis built on B2B ecommerce scale, cross border logistics depth, and disciplined SKU management. The key near term swing factor is execution on international growth, especially Europe, while keeping sourcing and freight costs under control. The latest earnings estimate revisions mostly reinforce, rather than change, that core story.
The biggest operational risk still sits in external shocks. Tariffs, shipping disruption, or a slowdown in European demand could quickly pressure margins and volumes on the marketplace. Modest service revenue diversification and recent insider selling keep the focus squarely on consistency of execution over headlines.
The most relevant news for this setup is the sharp upward revision in GigaCloud Technology’s earnings estimates for the current quarter and coming years. That aligns with a business that already shows earnings growth, high return on equity at 29.2%, and high quality profits. The move in estimates simply brings analyst models closer to that operating profile.
For you as a shareholder, the interest sits in whether management can keep expanding gross merchandise volumes and cross border logistics while protecting a net margin that recently sat at 10.6%. If that plays out alongside continued growth in active buyers and sellers, the current P/E of 13x versus industry metrics becomes more about execution risk than story risk.
What GigaCloud Technology's Consensus Forecasts Are Really Saying
Analysts sketch a fairly specific roadmap for GigaCloud Technology. They are baking in revenue growth of 10.0% a year over the next three years, a lift in net margin from 10.6% today to 11.4% in three years, and earnings climbing from US$156.1 million today to US$221.8 million by 2029, with the most optimistic forecasts reaching US$252.2 million. That move from current earnings to the 2029 consensus implies roughly a 42% earnings increase, which is a meaningful jump for any B2B ecommerce and logistics platform.
On the top line, the same analyst framework assumes GigaCloud Technology can reach about US$2.0b in revenue by 2029, paired with that US$221.8 million profit figure. The shares are modeled as trading on a P/E of 10.9x compared with 11.8x today and an industry level quoted at 13.2x. The scenario also builds in a 3.63% yearly reduction in share count over the next three years, which would amplify earnings per share if the forecasts play out, and applies a discount rate around 7.4% to pull those future numbers back into today’s valuation conversation.
GigaCloud Technology's narrative projects US$2.0b revenue and US$221.8 million earnings by 2029. This requires 10.0% yearly revenue growth and about a US$65.7 million earnings increase from US$156.1 million today.
Uncover why GigaCloud Technology's fair value indicates an 8% potential upside to its current price, which could close faster than many investors expect.
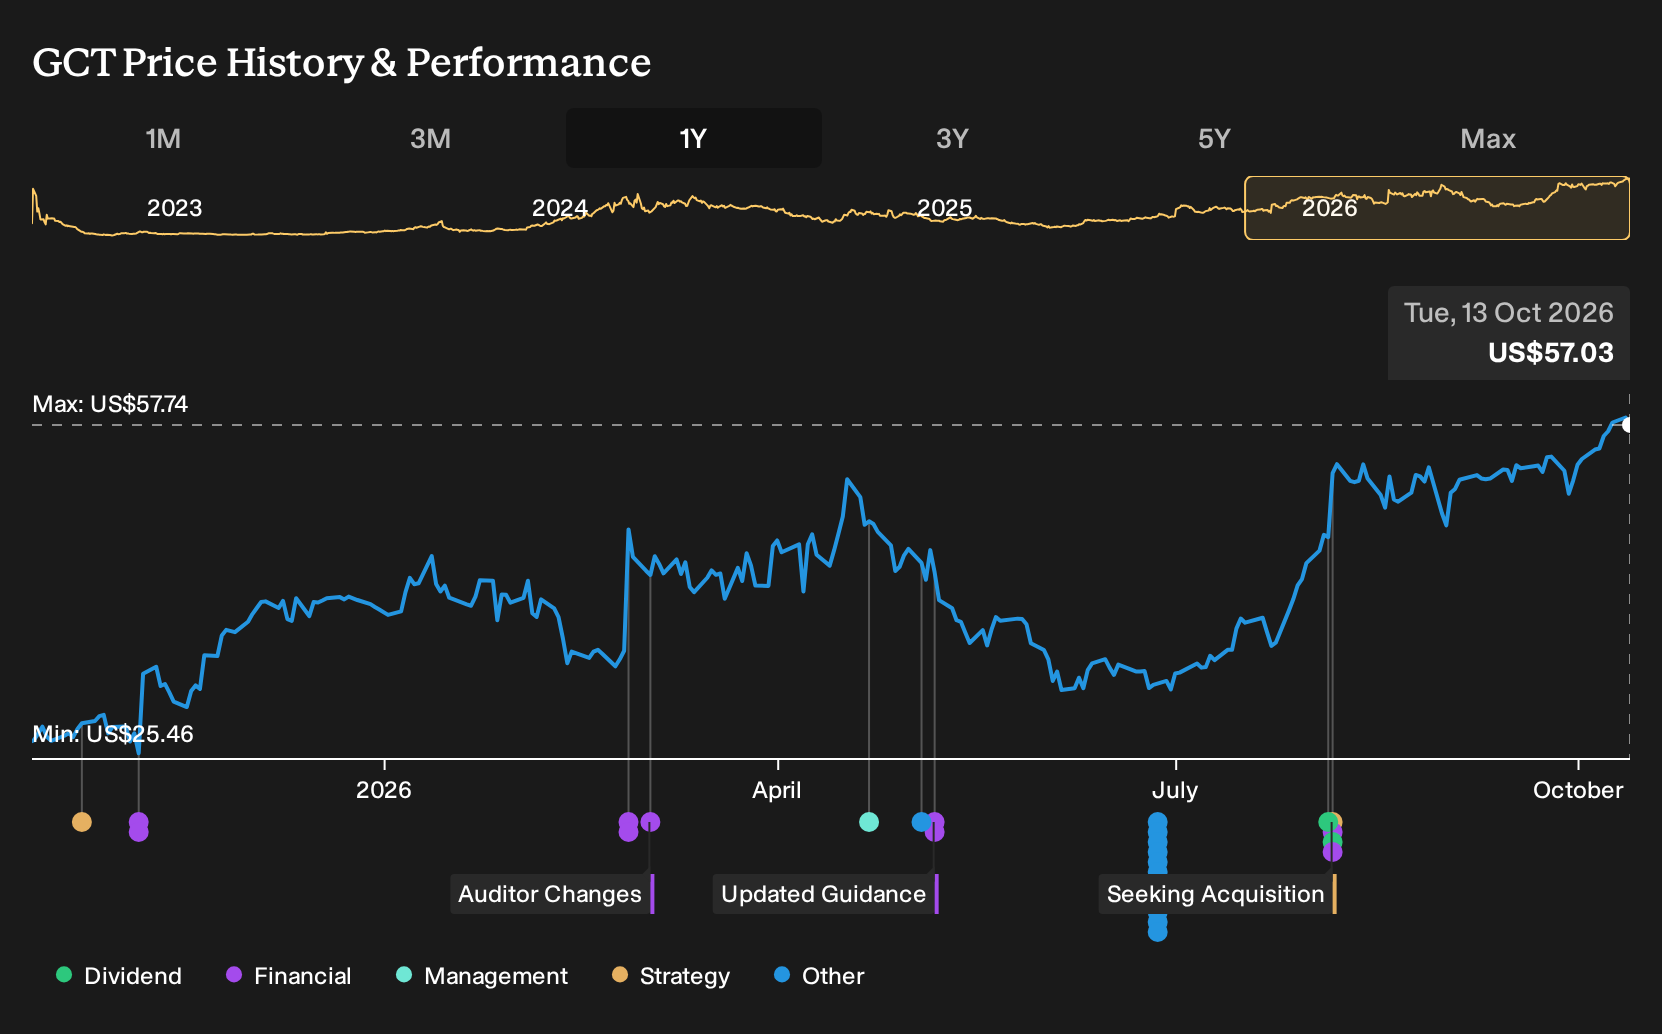
Exploring Other Perspectives
One alternate view on GigaCloud Technology leans heavily on regulatory risk. That more cautious camp had been working with a 9.7% yearly revenue pace and about US$208.0 million in 2029 earnings, rather than the US$221.8 million consensus. You can treat this news driven estimate reset as a prompt to compare several different angles before deciding what feels reasonable.
Explore 3 other GigaCloud Technology fair value estimates, including one that suggests it could be worth just $61.33.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your GigaCloud Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for GigaCloud Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GigaCloud Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond GigaCloud Technology?
If the reset in expectations around GigaCloud Technology has sharpened your focus, use that momentum to broaden your watchlist with other stocks that fit different risk and income profiles on the Simply Wall St Screener.
- For investors who care about quality first, start with a list of solid balance sheet and fundamentals (25 results) that pairs financial strength with durable fundamentals.
- If capital preservation matters more than chasing every headline, scan a 32 resilient stocks with low risk scores that screens well on resilience and lower risk scores.
- For those who want income on top of potential capital gains, consider a 8 dividend fortresses that aims for yields of 5% or more.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com