
Chubb (CB) Stock Could Be 47% Undervalued Following Hong Kong Private Markets Push
Chubb has delivered strong share price returns in recent years, and that leaves investors asking whether a valuation built on the returns it earns on its capital still holds up at today's levels.
- Over the past 5 years, Chubb has returned 104.3%, which puts real weight on the question of whether its capital returns justify this kind of share price performance.
- The recent partnership between Chubb Wealth and Hamilton Lane to expand access to private markets in Hong Kong may support expectations that the group can find new ways to deploy capital and fee-based capabilities, which matters for how efficiently it can earn returns on the funds it manages.
- Prefer to judge Chubb on earnings? See why Chubb's 11.9x P/E tells a different valuation story.
The issue now is whether the price investors pay for Chubb today is adequately explained by the returns the business earns on its capital base.
If you want to see how Chubb's capital returns compare with other opportunities, a focused stock screen is a useful second step in your research, especially with the solid balance sheet and fundamentals stocks screener (25 results).
Does Chubb Look Undervalued on Excess Returns?
The Excess Returns model looks at what Chubb earns on its equity compared with the return investors require, then builds an intrinsic value from those excess profits. For Chubb, the inputs point to a business that is expected to keep generating earnings meaningfully above its capital charge.
On the model’s numbers, book value sits at $195.45 per share, with a stable book value assumption of $224.20 per share based on analyst estimates. Stable EPS of $30.40 per share is set against a cost of equity of $15.83 per share, which implies an excess return of $14.57 per share and an average return on equity of 13.56%. Because the Chubb Wealth and Hamilton Lane partnership broadens access to fee based private market products in Hong Kong, the market may not yet be fully reflecting that additional use of capital in the current $346.16 share price when compared with what the Excess Returns framework supports. Find out what Chubb could be worth using our Excess Returns estimate.
The Chubb Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Chubb leaves off. They spell out which paths for future growth, margins and earnings would need to hold for the shares to be worth materially more or less than today’s price on the Community page. Each scenario links a fair value to a clear story about Chubb's potential catalysts and key risks, so you can track over time which version of events appears to be unfolding.
One of the top community narratives on Chubb: 5% undervalued
"Record adjusted net investment income of US$1.88b on a US$175b invested asset base indicates that future reinvestment of maturing assets could remain an important driver..."
Discover why this Narrative puts Chubb at 5% undervalued.
One More Question For Chubb That The Valuation Does Not Answer
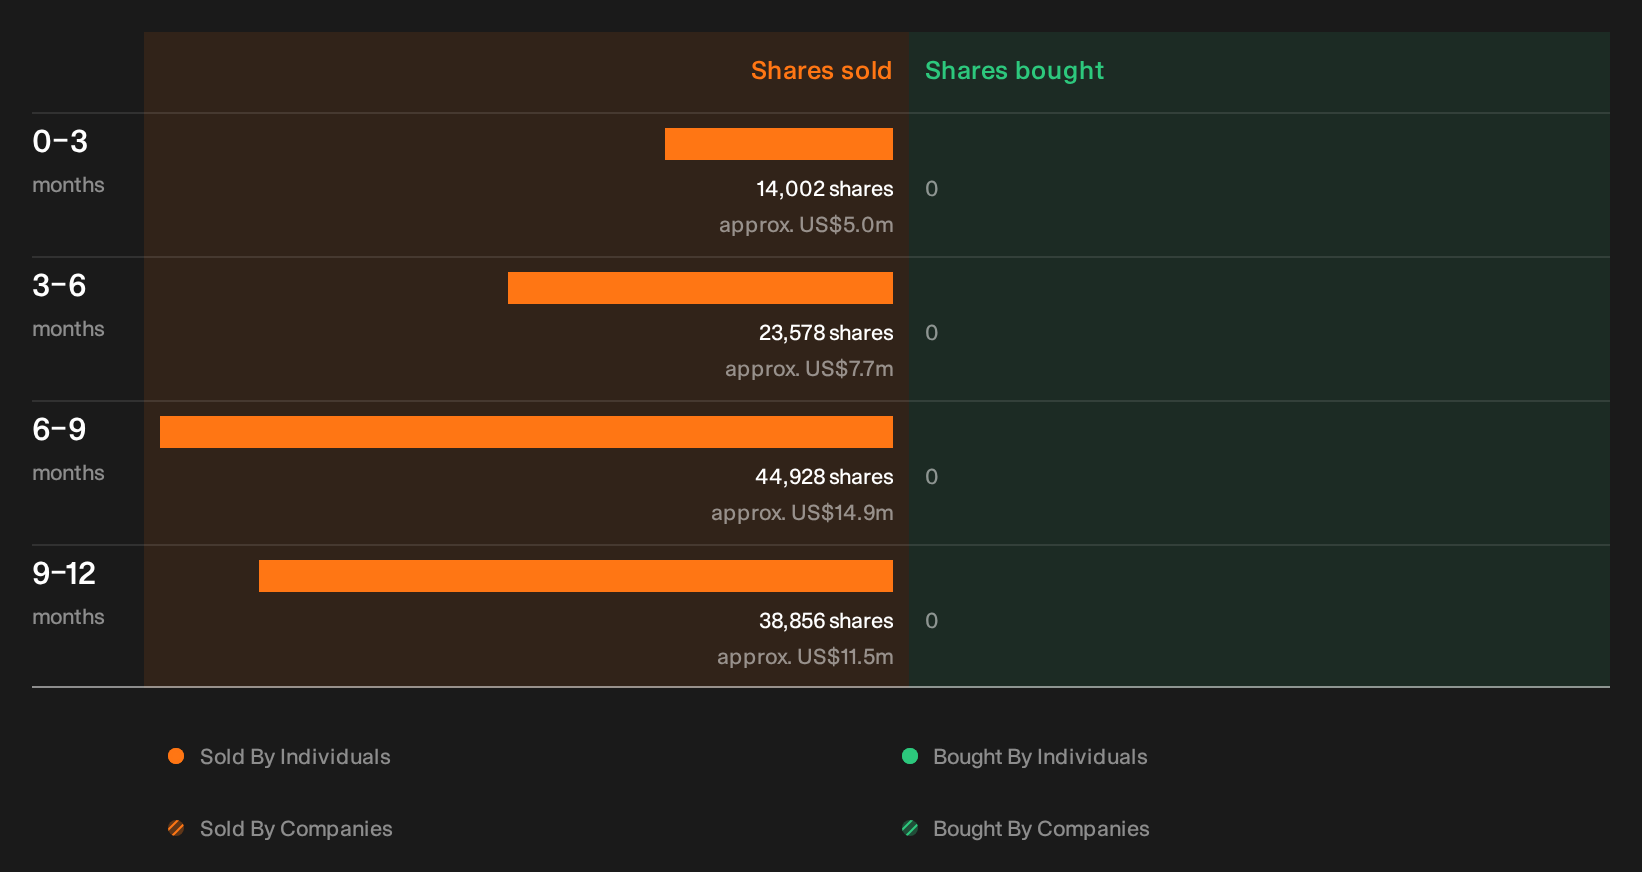
Price and profitability tell only part of the story for Chubb, because recent transactions by people inside the business raise a fresh question that hinges on who sold, how much, and why. See the recent insider selling flagged for Chubb.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com