
Learn Why The Bull Case For Ingram Micro Holding (INGM) Could Change Following Patent Approval
- Ingram Micro Holding recently received a U.S. patent for the Vendor and Customer Agnostic Framework that underpins its AI powered Xvantage platform, which connects vendors, customers and partners using their existing systems and data formats.
- The newly patented framework targets one of the biggest cost and execution challenges in distribution by automating complex, previously custom integrations across catalogs, quotes, orders and billing workflows.
- We will now explore how this patented integration framework inside Xvantage could influence Ingram Micro Holding's broader AI driven investment narrative.
Scan a curated set of AI infrastructure plays that echo what Ingram Micro Holding is building with Xvantage by reviewing 92 AI infrastructure stocks.
Ingram Micro Holding Investment Narrative Recap
To own Ingram Micro Holding, you effectively need to believe its AI centric digital platforms can turn a low margin distribution footprint into a more automated, software like operating model. The Xvantage patent fits that thesis by formalizing the data plumbing that could support lower cost to serve and more repeatable integrations across partners.
In the near term, the key swing factor is whether large, low margin GPU and hardware deals crowd out higher margin cloud and SMB activity. The biggest risk still sits in working capital and leverage, since complex AI infrastructure deals can tie up cash if sell through slows, and this patent alone does not change that exposure.
The VCAF patent directly links to one of the main operational catalysts that has been flagged, the push to use Xvantage to automate onboarding and standardize transactions across vendors and solution providers. By making it easier to plug in existing systems, the framework could support broader usage of Ingram Micro Holding's AI tools without requiring every partner to rearchitect workflows.
That same framework touches the current risk set too. If VCAF successfully reduces manual integrations and email based processes, it may help limit the cost burden of low margin AI infrastructure deals and support more scalable working capital management. If adoption is slow or vendors favor closed ecosystems instead, the expected uplift in mix, efficiency and data driven decision making could prove harder to achieve.
Ingram Micro Holding's current consensus narrative anchors on revenues reaching $61.4b and earnings of $678.6m by 2029, based on analysts' expectations of 3.1% yearly revenue growth and an earnings increase of about $248m from current earnings of $430.6m.
Uncover why Ingram Micro Holding's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
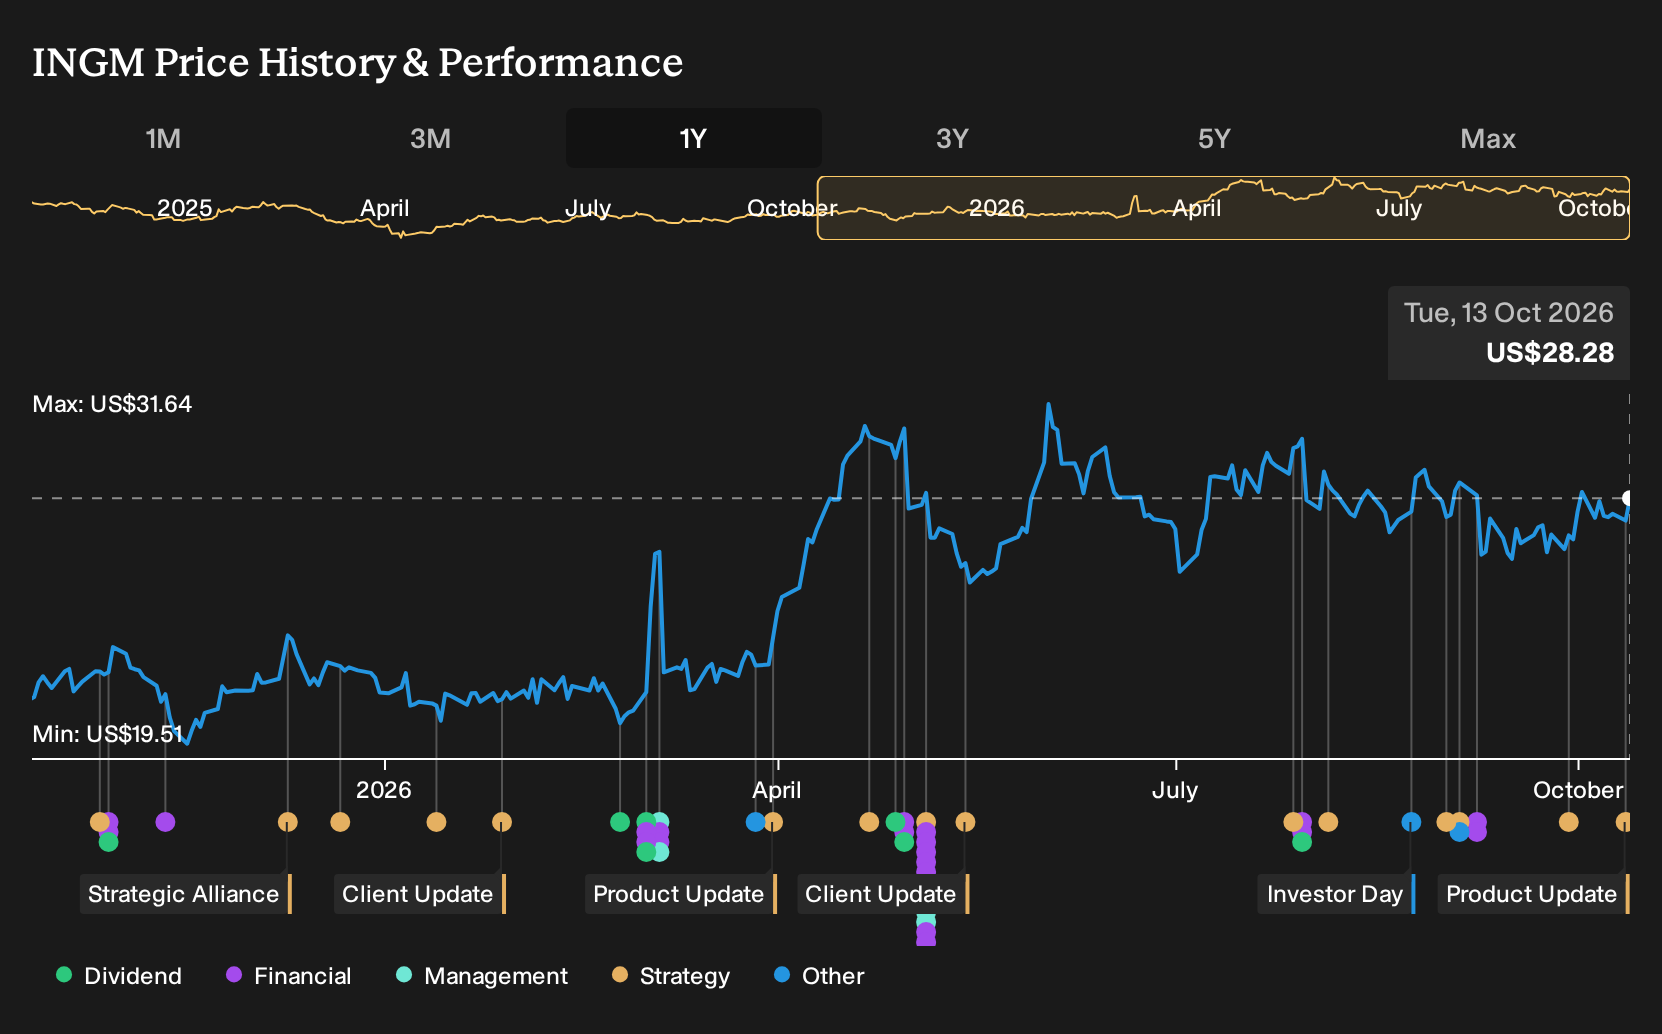
Exploring Other Perspectives
One alternate angle on Ingram Micro Holding focuses on cloud softness rather than the Xvantage patent. The most optimistic analysts were already penciling in faster top line growth at 6.6% a year and earnings of about US$849.9 million by 2029. You can compare that upbeat view with more cautious forecasts and decide how this new patent news might reshape both.
Explore another Ingram Micro Holding fair value estimate, including one that suggests up to 17% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ingram Micro Holding research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ingram Micro Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingram Micro Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ingram Micro Holding?
If the Ingram Micro Holding story has sharpened your thinking on AI infrastructure and platform economics, it can be useful to line it up against a wider watchlist built with a disciplined screener approach.
- For investors who care most about valuation support and quality fundamentals, start with a curated set of 32 high quality undervalued stocks that pair stronger balance sheets with more grounded pricing.
- If capital preservation and a smoother ride matter to you, consider using a filter that highlights 32 resilient stocks with low risk scores so you can focus on businesses with more resilient risk scores.
- When you want to get ahead of the crowd and research less followed opportunities, broaden your radar with a tailored list of 20 high quality undiscovered gems that already screen well on core fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com