
Tech Star Dan Ives Just Made a Shocking Prediction on Apple Stock
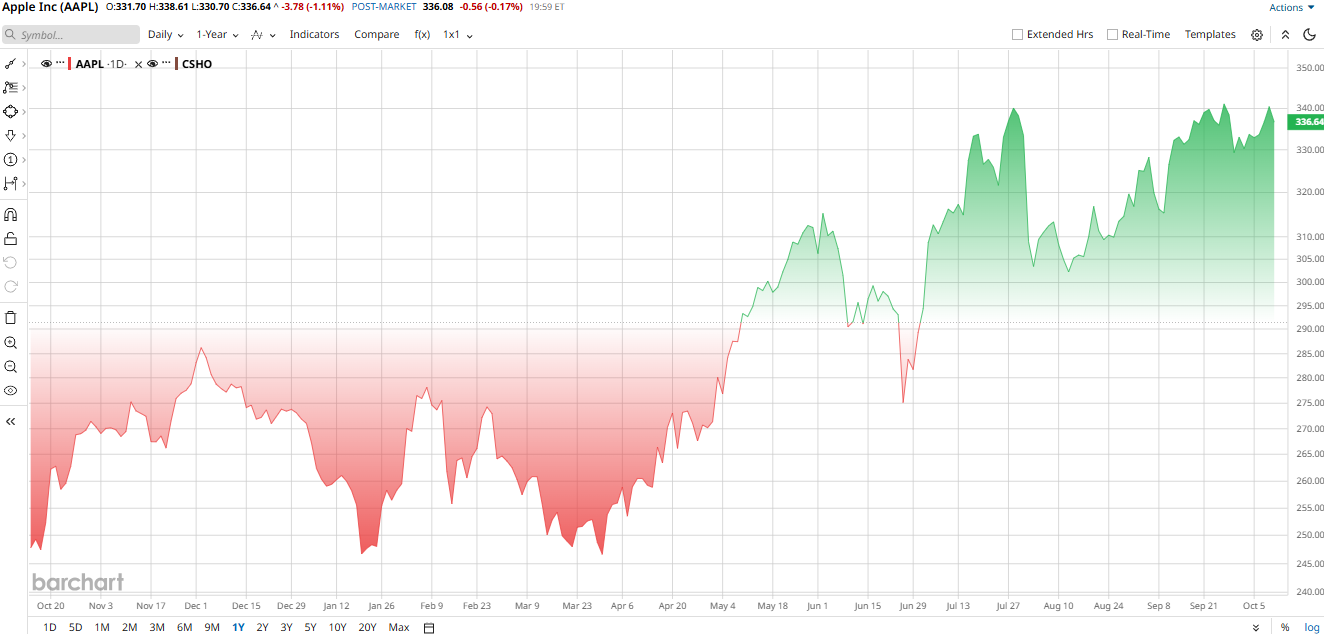
Apple (AAPL) shares have performed decently in 2026, gaining more than 25% year-to-date (YTD), but Dan Ives sees further upside ahead. The Yorkville Ives analyst recently estimated that artificial intelligence (AI) could add another $75 per share to Apple's valuation.
Ives reiterated an “Outperform” rating and a $400 price target, arguing that Apple does not need to build the industry’s most powerful AI model to profit from the boom. Its advantage is distribution, as the company's base of more than 2.5 billion active devices gives it an enormous audience for AI features and services.
Ives called Apple “the toll collector on the consumer AI highway.” Apple can monetize AI across its ecosystem, as it benefits from the App Store. If AI sparks device upgrades and new subscription spending, it could become a growth engine rather than just another iPhone feature.
AI Could Unlock Apple's Next Upgrade Cycle
The boldest claims of Apple's new Siri AI and wider Apple Intelligence are crucial to Ives' point. At the 2026 Worldwide Developers Conference (WWDC), the company unveiled its updated AI experiences, including the new Siri. With the advent of AI, customers are also gaining a legitimate incentive to upgrade their mobile devices to the latest iPhone models.
Ives believes about 375 million iPhones have not been upgraded by users for over four years. Just a small percentage of those users making the leap to new models could enable a major sales cycle. Ives also believes that such offerings and products built on AI will represent over 15% of Services revenue in the future, allowing for more growth to be added to the subscriptions and digital services category.
The foldable iPhone Duo opens up another potential avenue of increased spending, but it still has some murky sales prospects. Apple will need to monetize and commercialize the excitement of artificial intelligence, using it more often and selling hardware and services with AI in mind.
Record Sales Provide a Strong Starting Point
Apple has financial momentum behind the story. In the fiscal third quarter ended June 27, revenue reached $109.4 billion, up 16% year-over-year (YOY). iPhone revenue rose 22% to $54.25 billion, Mac revenue climbed 29% to $10.35 billion, and Services revenue advanced 12% to $30.74 billion. EPS also increased 29% YOY to $2.02, although tariff refunds contributed $0.11.
CEO Tim Cook called it Apple’s “strongest June quarter ever,” pointing to double-digit growth across iPhone, Mac, and Services. Services now represents about 28% of quarterly revenue and can help Apple rely less heavily on hardware replacement cycles. Even when customers do not buy a new device, digital services can keep generating revenue for the company.
Still, risks remain. Apple has warned about tight advanced chip supply, while higher memory costs could pressure production and margins. AAPL stock also trades at a premium valuation, leaving little room for AI features to disappoint. If customers see too little value to upgrade or pay for new services, Ives' predicted $75 boost could take longer to materialize, or fail to arrive.
Wall Street Sees Upside, But Its Average Target Is Much Lower
Ives believes Apple has an opportunity to bridge users with AI, calling the firm “the toll collector on the consumer AI highway.” The analyst has a $400 price target for AAPL stock and believes that the market hasn't fully priced in the opportunity.
Other analysts, meanwhile, seem positive but less enthusiastic. Goldman Sachs has a $360 price target for AAPL stock, while TD Cowen has a $400 price target.
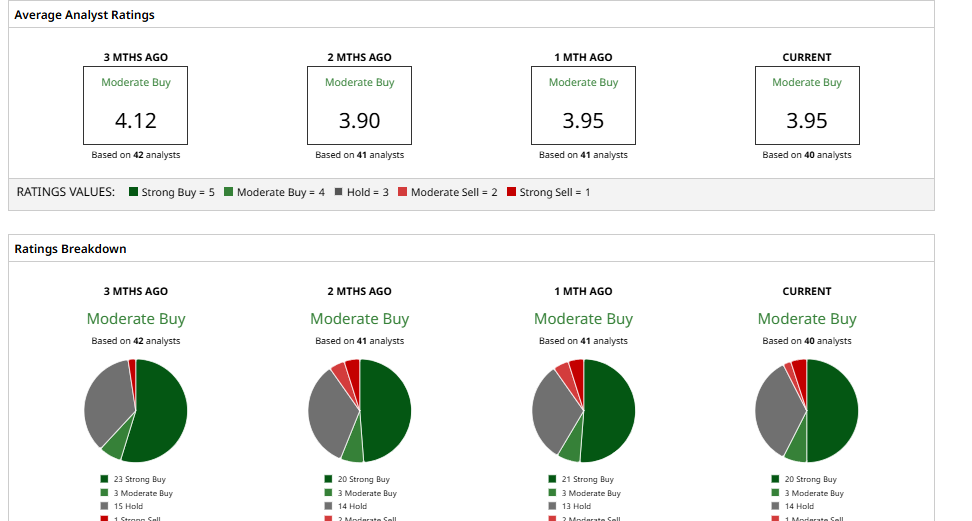
Overall, Wall Street has a consensus “Moderate Buy” rating for Apple based on 40 analysts with coverage. The average price target of $331.86 represents potential downside of 3% from current levels, which is a less aggressive forecast than the one put forth by Ives. His $400 price target points to potential upside of 17% from here.
Still, not everyone is as optimistic about Apple’s upside, especially given its high valuation and the fact that its AI investments have yet to deliver clear results. Apple's valuation isn't particularly cheap, with the stock trading at about 39.1 times trailing earnings and 35.3 times forward earnings. That means there is little room for step-backs or slowdowns. The AI opportunity may offer additional gains, but investors have yet to see the impact of Siri AI-related improvements and service revenue.
For the time being, Ives' forecast is a positive one, but it doesn't mean Apple is completely in the clear.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.