
ePlus (PLUS) Climbed, But What Is Drawing Fresh Attention?
Recent interest in ePlus (PLUS) has centered on its steady long-term revenue expansion, improving free cash flow margin, and 13.9% return on invested capital, paired with a forward P/E of 16.9x.
At a share price of $96.93, ePlus has enjoyed a 12.1% 3 month share price return and an 11.9% year to date gain. The 1 year total shareholder return of 35.0% suggests recent momentum building on the company’s longer record of compounding.
Scan beyond ePlus and compare its momentum and fundamentals with a curated group of resilient companies screened for 32 resilient stocks with low risk scores.
For ePlus, the recent climb in the share price sits next to solid revenue growth and a 13.9% ROIC. Is this move mostly about better fundamentals, or are investors simply paying a richer P/E multiple?
Most Popular Narrative: 13% Undervalued
Against the latest close at $96.93, the most followed narrative for ePlus pins a fair value at $111. This frames the recent rally as still leaving some upside on the table while hinging heavily on how its order book and service mix play out.
Persistent demand for AI powered infrastructure, security, and cloud solutions across industries is expected to accelerate. ePlus's focused investments in AI consultative capabilities and AI related plumbing in compute, networking, and security, together with open orders above US$1.5b that management expects to convert mainly in the back half of the year and beyond, give the company a pipeline that can support future revenue and earnings growth.
See why 1 investors see ePlus as 13% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, the ePlus story can crack if mid single digit guidance for fiscal 2027 proves optimistic or if recent gross margin pressure lingers longer than expected.
Find out about the key risks to this ePlus narrative.
Another View: DCF Pours Cold Water On The ePlus Bull Case
The story looks different through the SWS DCF model. On that lens, ePlus at $96.93 trades above an estimated future cash flow value of $59.70, which screens as overvalued. If cash generation matters more than earnings multiples, does this change how you weigh the upside narrative?
Look into how the SWS DCF model arrives at its fair value.
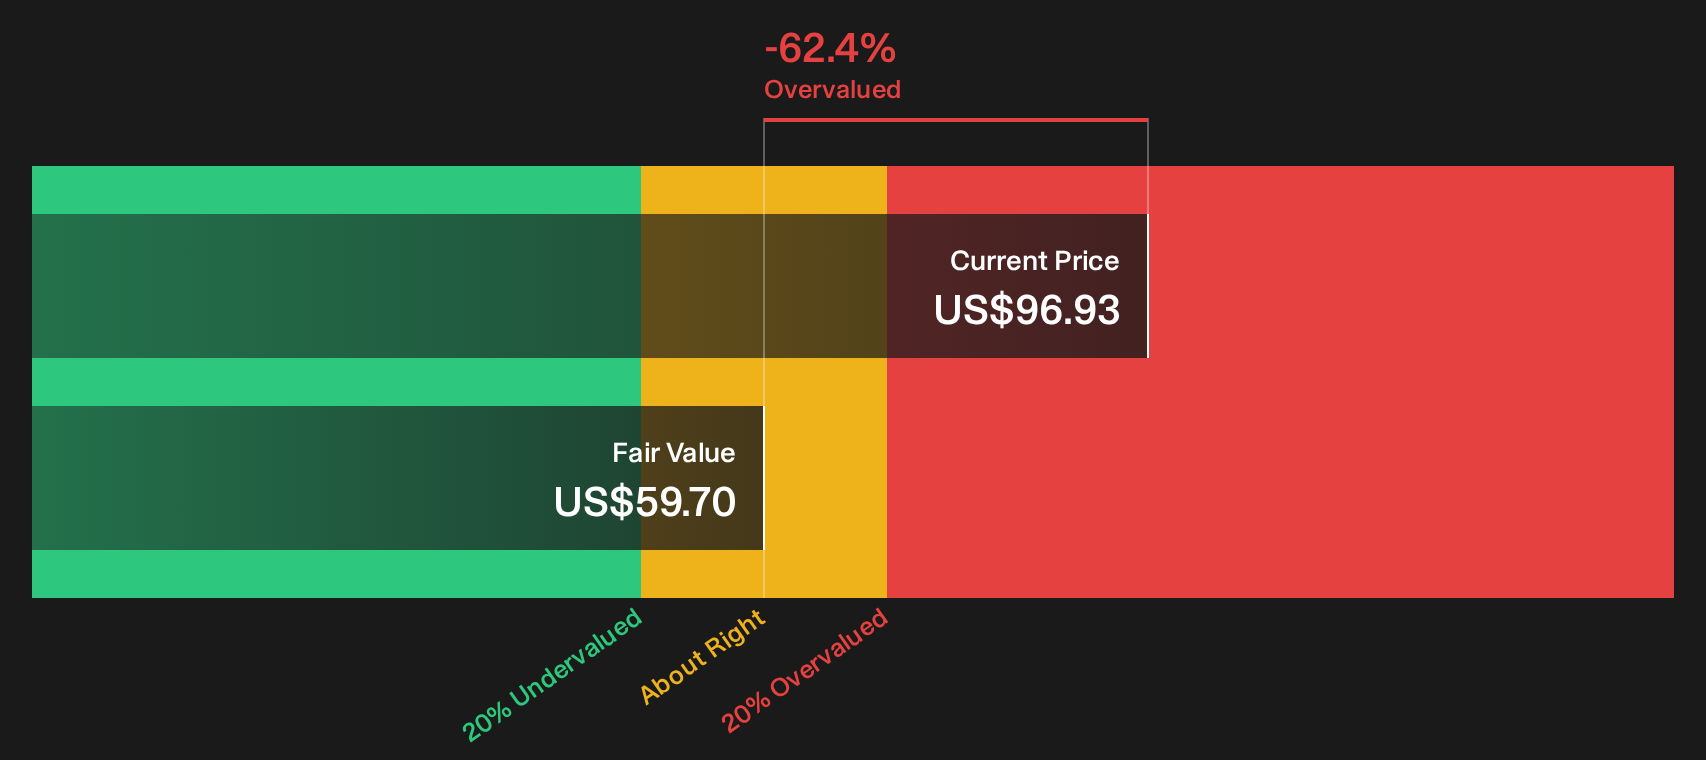
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ePlus for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the ePlus debate today. If you want to move fast and anchor your own view in the numbers, start with the 3 key rewards.
Ready For More ePlus-Like Ideas?
If the ePlus debate sharpened your instincts, you can put that edge to work by scanning other opportunities that combine clear numbers with focused business models.
- Target resilient upside by reviewing 32 high quality undervalued stocks that pair compressed valuations with solid fundamentals and cleaner balance sheets than many peers.
- Build a sturdier income stream by weighing stocks screened as 8 dividend fortresses that focus on meaningful yields backed by real cash flows.
- Cut portfolio stress by concentrating on a list of solid balance sheet and fundamentals (25 results) so short term noise does not dictate every move you make.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com