
Huntington Ingalls’ Quarterly Earnings Preview: What You Need to Know
Huntington Ingalls Industries, Inc. (HII), headquartered in Newport News, Virginia, designs, builds, overhauls, and repairs military ships. Valued at $10.2 billion by market cap, the company offers non-nuclear and nuclear-powered vessels for the U.S. Navy and Coast Guard, and also provides after-market services for military ships worldwide. The largest military shipbuilding company is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Oct. 29.
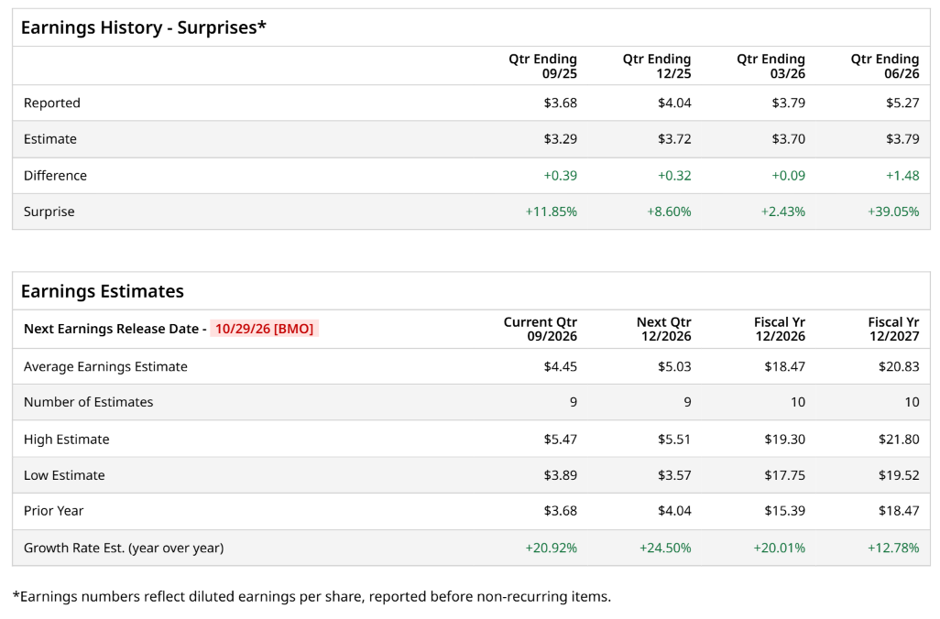
Ahead of the event, analysts expect Huntington Ingalls to report a profit of $4.45 per share on a diluted basis, up 20.9% from $3.68 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Huntington Ingalls to report EPS of $18.47, up 20% from $15.39 in fiscal 2025. Its EPS is expected to rise 12.8% year over year to $20.83 in fiscal 2027.
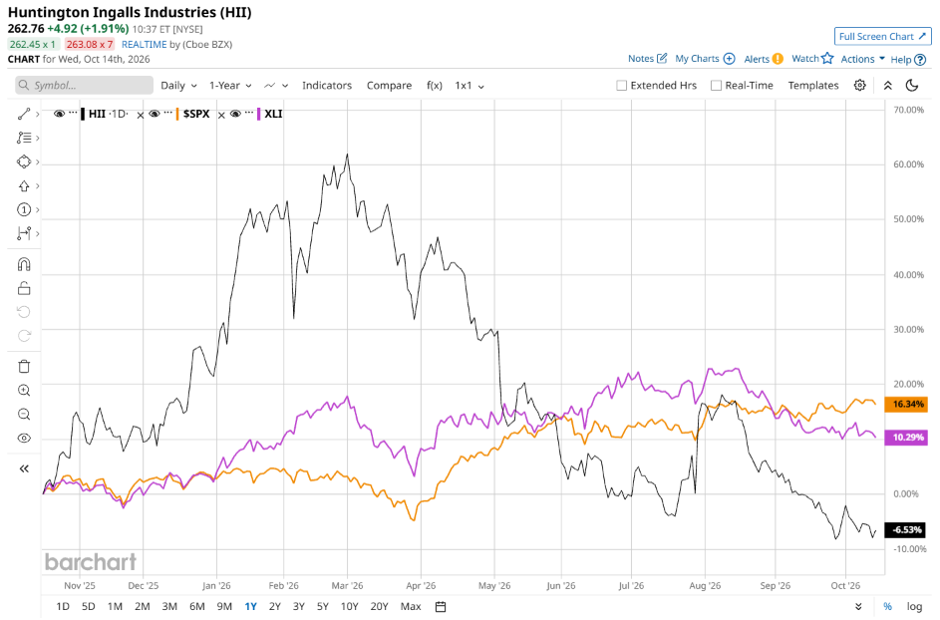
HII stock has underperformed the S&P 500 Index’s ($SPX) 17.3% gains over the past 52 weeks, with shares down 10.2% during this period. Similarly, it underperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 11.4% rise over the same time frame.
Despite holding a uniquely favorable strategic position in the current geopolitical landscape with its critical portfolio of naval defense, nuclear shipbuilding, and multi-domain military offerings, HII has struggled to capture primary preference among defense sector investors. This underperformance stems from persistent structural and operational hurdles within its fundamentals, most notably labor constraints, ongoing margin compression, and complex execution timelines across its massive capital-intensive ship programs, that have consistently overshadowed its otherwise robust long-term backlog.
Analysts’ consensus opinion on HII stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 13 analysts covering the stock, six advise a “Strong Buy” rating, and seven give a “Hold.” HII’s average analyst price target is $345.85, indicating a potential upside of 32.4% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.