
Client Win And Earnings Near Could Alter The Investment Case For Intapp (INTA)?
- Intapp announced that Mauldin & Jenkins has gone live with Intapp Employee Compliance, replacing manual, email-based independence controls with an automated platform that centralizes financial interest monitoring, certifications, outside business activities, and trade pre-clearance ahead of the QC 1000 December 2026 deadline.
- The Mauldin & Jenkins rollout highlights real-world uptake of Intapp Employee Compliance, with the firm planning to remove hundreds of hours of manual work each year as adoption ramps, while investors also await fiscal Q1 2027 results later in October 2026.
- This article examines how Intapp’s investment narrative relates to Mauldin & Jenkins’ compliance automation implementation and the scheduled earnings call.
Compare Intapp’s compliance push with other potential beneficiaries of tighter audit rules by scanning our hand picked 32 resilient stocks with low risk scores, which is built around resilient balance sheets and measured risk profiles.
Intapp Investment Narrative Recap
To own Intapp, investors need to be comfortable with a focused bet on AI driven, cloud first software for professional and financial services firms. That requires confidence that the product set keeps solving real workflow problems and that the move from on premise to SaaS continues without losing key accounts or weakening pricing.
The Mauldin & Jenkins go live supports the story that Intapp products can handle complex compliance needs, although the financial impact of a single client win is likely small. Near term attention stays on the fiscal Q1 2027 update on 27 October 2026, while key risks remain execution, partner delivery and ongoing losses.
The upcoming fiscal Q1 2027 earnings release on 27 October is the announcement that ties most directly to this client news. Investors get a concrete implementation proof point in Mauldin & Jenkins, followed by a near dated checkpoint where management will lay out how compliance and other cloud modules are contributing to recurring revenue and deal momentum.
For catalysts, investors will likely watch whether Intapp highlights more QC 1000 driven demand and additional Employee Compliance wins on that call. On the risk side, any signs that partner delivered projects are slow or costly, or that cloud transition work pressures margins, would work against the argument that these deployments can scale efficiently.
Intapp's current consensus narrative points to US$888.0 million in revenue and US$76.7 million in earnings by 2029. That path assumes revenue expansion of 15.4% a year and an earnings swing of about US$118.0 million, from a loss of US$41.3 million today to that 2029 profit level.
Uncover why Intapp's fair value indicates a 5% potential upside to its current price that may not last much longer.
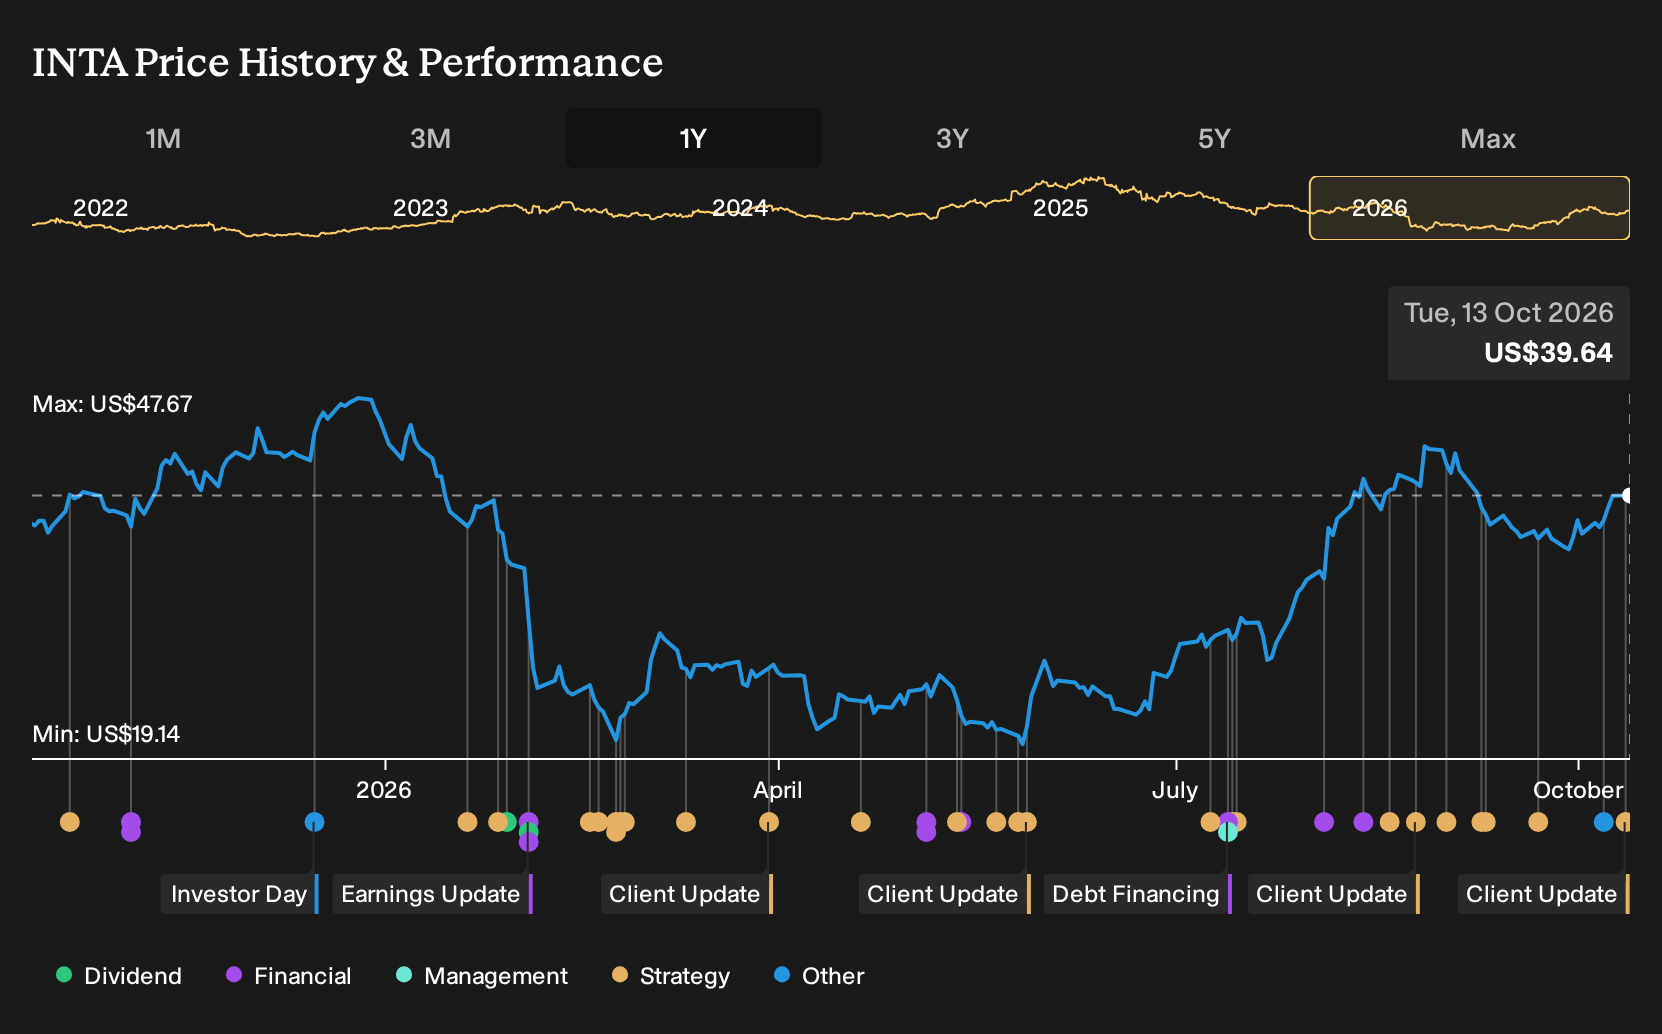
Exploring Other Perspectives
One alternate view focuses on competitive risk from big platforms rather than on partner execution. The most bearish analysts were already penciling in around US$867.0 million of revenue and US$76.2 million of earnings for 2029, with a US$34.0 target, before this Mauldin & Jenkins win. That gap in expectations shows how sharply opinions on Intapp can differ.
Explore 4 other Intapp fair value estimates, including one that suggests as much as 15% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Intapp research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Intapp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intapp's overall financial health at a glance.
Looking For More Ideas Beyond Intapp?
Once you have a view on Intapp, it can help to set it alongside other listed businesses with different risk and return profiles. The Simply Wall St Screener gives you a quick way to compare fundamentals, balance sheet strength, and income potential across a wider watchlist.
- For investors who want potential mispricings with quality behind them, start by checking 32 high quality undervalued stocks that already clear strict fundamental filters.
- If capital preservation sits high on your list, focus on companies with sturdier finances by reviewing the list of solid balance sheet and fundamentals (25 results).
- Income focused portfolios can benefit from reliable payers, so scan through the 8 dividend fortresses offering higher yields backed by data driven checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com