
How Higher Oil Prices Will Impact ConocoPhillips (COP) Stock
- ConocoPhillips has attracted attention as a large scale oil and gas producer with a decade of 10.1% annual revenue growth and a reputation for strong free cash flow generation, ahead of an earnings report scheduled for 5 November 2026. Analysts expect this report to show higher EPS and revenue than a year earlier.
- Rising oil prices linked to conflict in the Middle East have supported interest in ConocoPhillips. Its sizeable production base and LNG exposure give it more leverage to commodity pricing and supply concerns than smaller peers, according to recent institutional commentary and derivatives positioning focused on cash flow strength.
- We will now look at how this upbeat cash flow backdrop, reinforced by higher oil prices, could reshape ConocoPhillips's investment narrative.
ConocoPhillips Investment Narrative Recap
To own ConocoPhillips, you need to believe its mix of long life projects like Willow and LNG, plus high volume Lower 48 output, can keep turning a large production base into reliable cash generation. The near term swing factor is still execution on those big capital projects, because delays or cost creep can quickly blunt that free cash flow story.
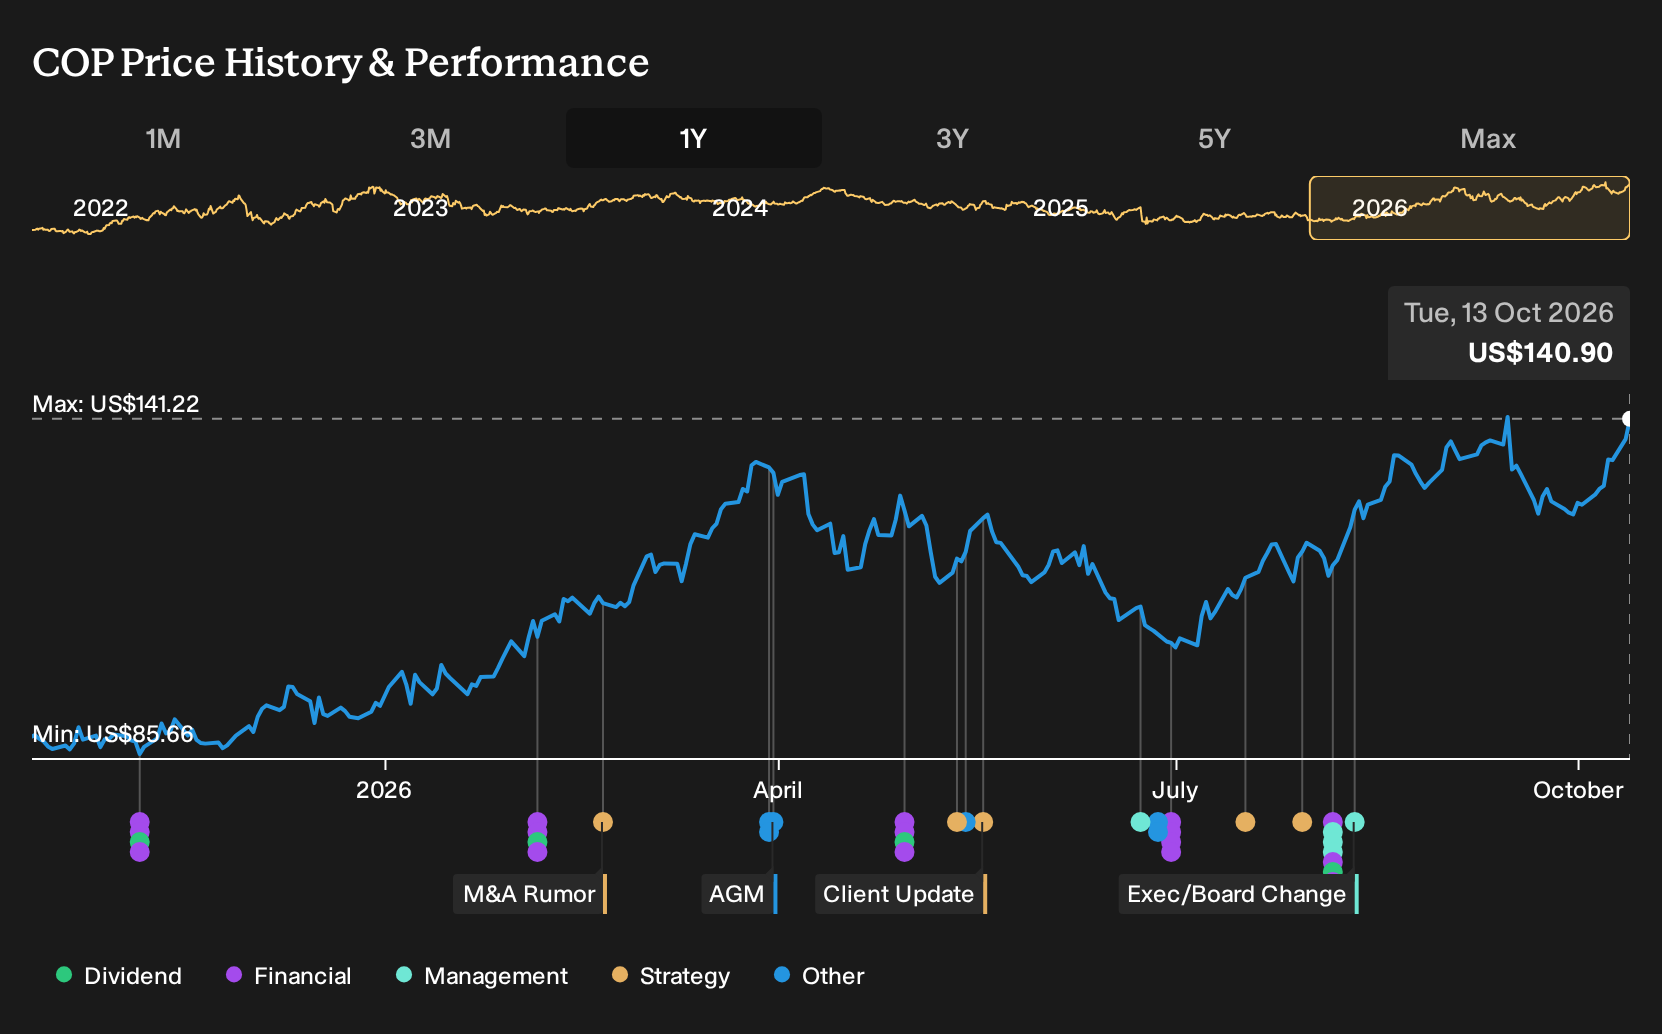
The recent share price strength and rising oil prices ahead of the 5 November 2026 earnings report do not change the core thesis. They simply raise the bar for near term delivery. The biggest risk remains that higher capital spending in the Permian and any disruption in regions like Iraq or Libya narrow future margin headroom.
The clearest near term announcement tying into this setup is the guidance lift for 2026 capital spending to US$12b to US$12.5b. That points to ConocoPhillips needing more reinvestment to sustain Lower 48 volumes, which matters if you are counting on reinvestment rates drifting lower over time to support expanding free cash flow.
Set against that, investors are watching whether higher oil prices and the firm’s LNG offtake portfolio start to show up more visibly in cash generation when earnings land in early November. Analyst optimism around EPS into 2029 only really matters if management keeps major projects on schedule while keeping that bigger capital budget from eroding returns.
ConocoPhillips' current narrative points to revenues of US$68.0b and earnings of US$11.4b by 2029, based on analysts' assumption of 1.8% yearly revenue growth and an earnings increase of about US$2.1b from US$9.3b today.
Uncover why ConocoPhillips' fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You are seeing one clear tension around ConocoPhillips. The consensus leans on LNG and Willow as growth engines, while the most pessimistic analysts worry that concentrated project risk could hold revenue closer to about US$62.0b and earnings near US$9.9b by 2029. Those pre-news views may shift, so treat them as moving pieces.
Explore 3 other ConocoPhillips fair value estimates, including one that suggests it could be worth just $146.08.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your ConocoPhillips research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ConocoPhillips. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ConocoPhillips' overall financial health at a glance.
Looking For More Investment Ideas Beyond ConocoPhillips?
If the ConocoPhillips story has sharpened your view on risk, cash flow and project quality, it can be useful to line that up against other opportunities using the Simply Wall St Screener.
- Prefer quality and value together? Scan for companies combining strong fundamentals with valuation support through our 20 high quality undiscovered gems.
- Want balance sheets that can absorb shocks? Filter for businesses with healthier financial positions using the list of solid balance sheet and fundamentals (25 results).
- Looking for steadier profiles? Focus on companies with more resilient risk scores by checking the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com