
Progressive (NYSE:PGR) Misses Q3 2026 Revenue Estimates, Stock Drops
Insurance company Progressive (NYSE:PGR) fell short of the market’s revenue expectations in Q3 2026 as sales rose 3% year on year to $23.19 billion. Its GAAP profit of $4.37 per share was 1.8% below analysts’ consensus estimates.
Is now the time to buy Progressive? Find out by accessing our full research report, it’s free.
Progressive (PGR) Q3 2026 Highlights:
- Net Premiums Earned: $21.87 billion vs analyst estimates of $21.97 billion (4.9% year-on-year growth, in line)
- Revenue: $23.19 billion vs analyst estimates of $23.4 billion (3% year-on-year growth, 0.9% miss)
- Combined Ratio: 90% vs analyst estimates of 89.7% (29 basis point miss)
- EPS (GAAP): $4.37 vs analyst expectations of $4.45 (1.8% miss)
- Book Value per Share: $59.51 vs analyst estimates of $62.85 (1.6% year-on-year decline, 5.3% miss)
- Market Capitalization: $129.6 billion
Company Overview
Starting as a small auto insurance company in 1937 with a pioneering focus on high-risk drivers, Progressive (NYSE:PGR) is a major auto, property, and commercial insurance provider that offers policies through independent agents, online platforms, and over the phone.
Revenue Growth
Insurance companies earn revenue from three primary sources: 1) The core insurance business itself, often called underwriting and represented in the income statement as premiums 2) Income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities 3) Fees from various sources such as policy administration, annuities, or other value-added services. Luckily, Progressive’s revenue grew at an exceptional 14.5% compounded annual growth rate over the last five years. Its growth surpassed the average insurance company and shows its offerings resonate with customers, a great starting point for our analysis.
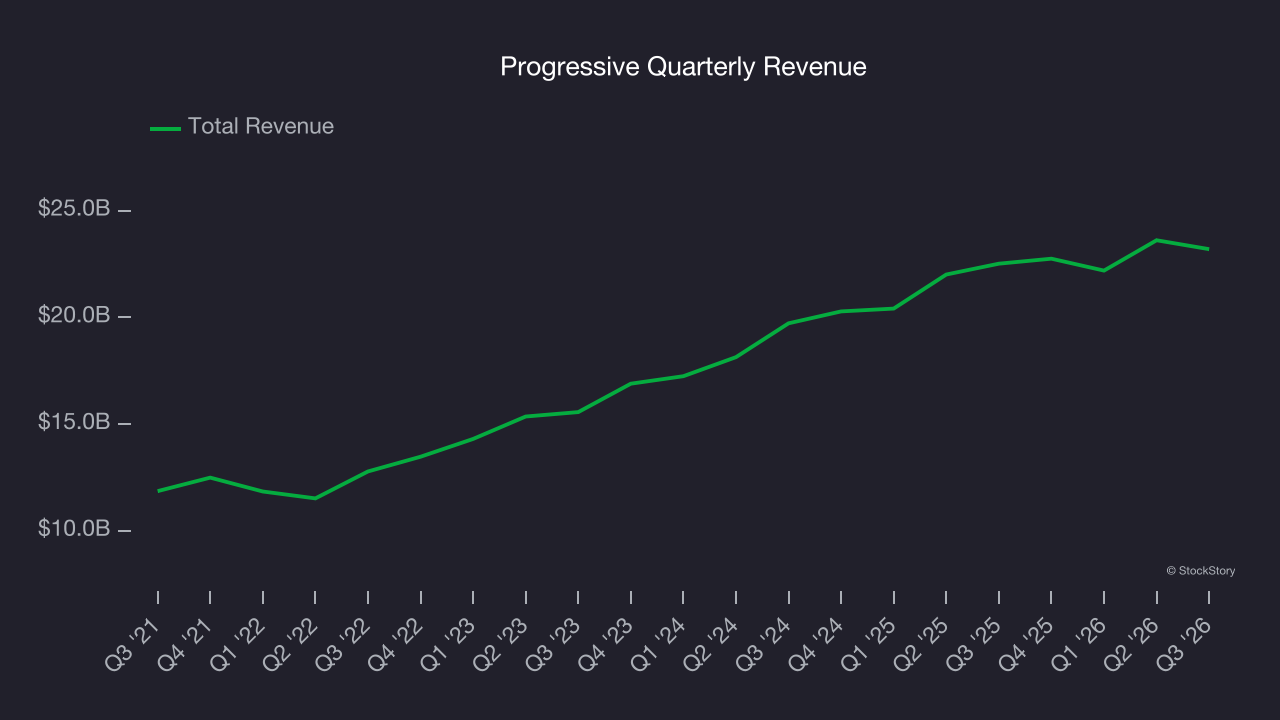
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Progressive’s annualized revenue growth of 12.9% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 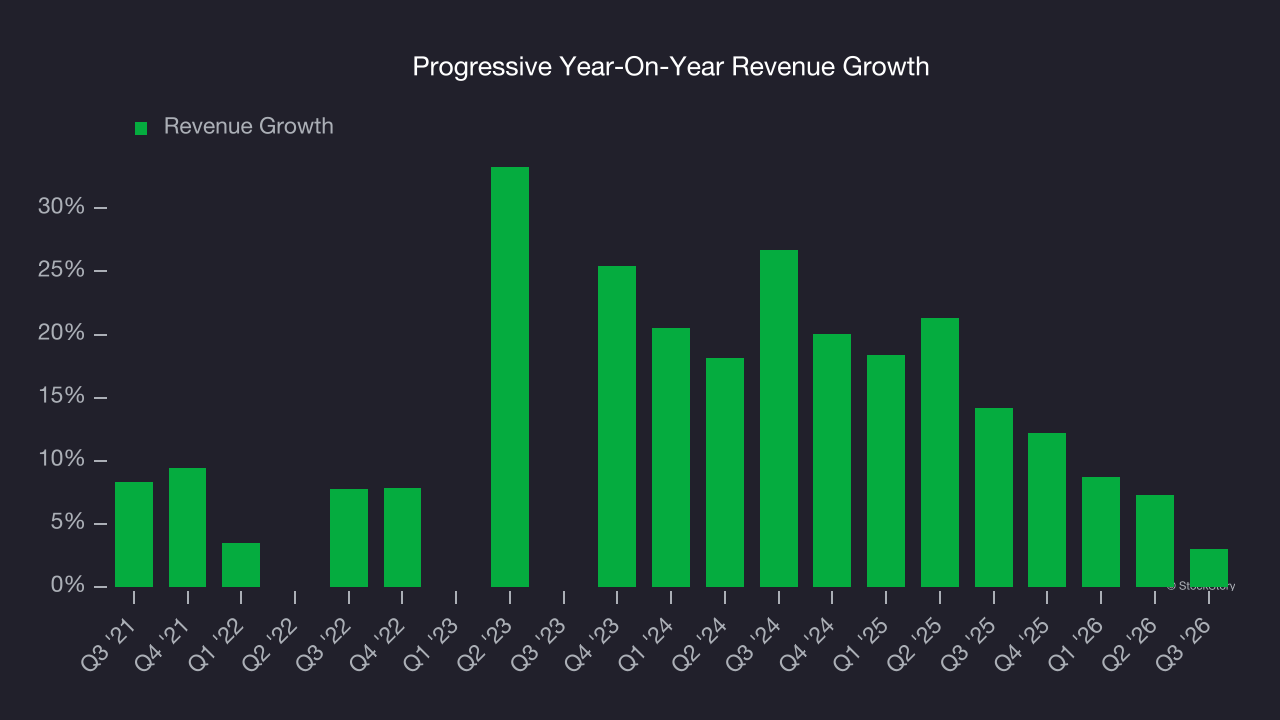 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Progressive’s revenue grew by 3% year on year to $23.19 billion, falling short of Wall Street’s estimates.
Net premiums earned made up 94.4% of the company’s total revenue during the last five years, meaning Progressive lives and dies by its underwriting activities because non-insurance operations barely move the needle.
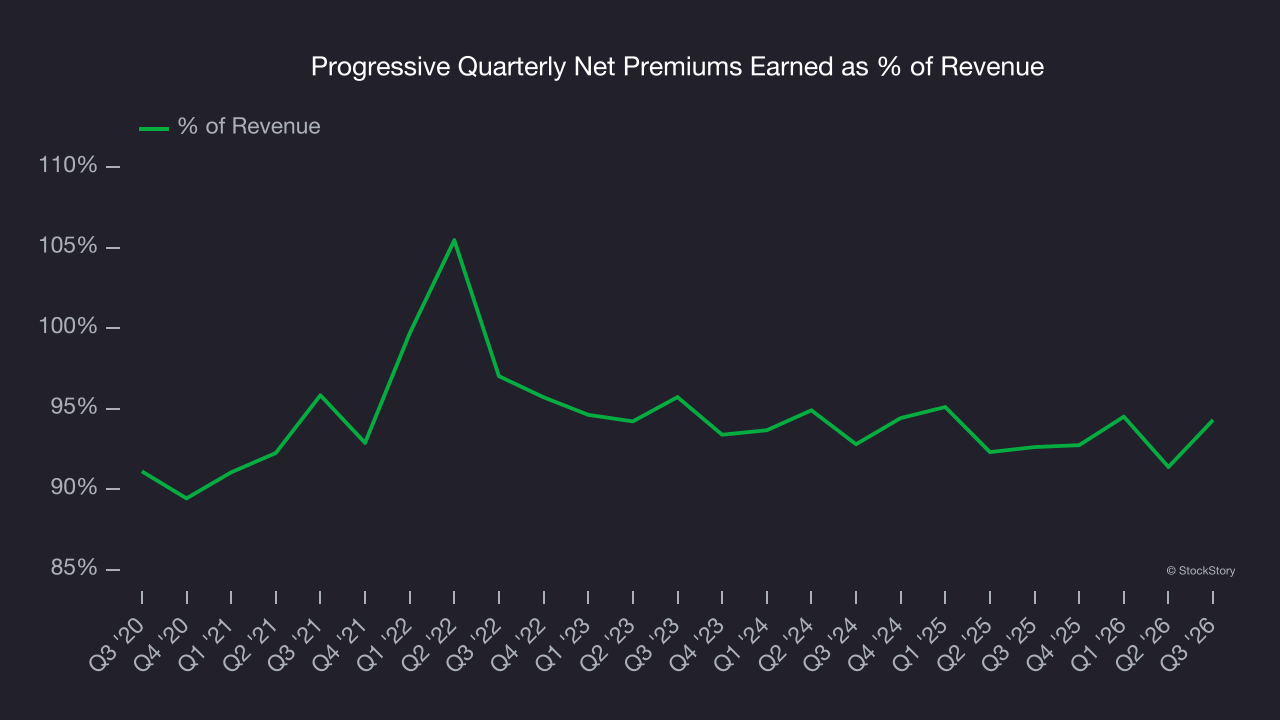
Markets consistently prioritize net premiums earned growth over investment and fee income, recognizing its superior quality as a core indicator of the company’s underwriting success and market penetration.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Book Value Per Share (BVPS)
Insurance companies are balance sheet businesses, collecting premiums upfront and paying out claims over time. The float — premiums collected but not yet paid out — is invested, creating an asset base supported by a liability structure. Book value captures this dynamic by measuring:
- Assets (investment portfolio, cash, reinsurance recoverables) - liabilities (claim reserves, debt, future policy benefits)
BVPS is essentially the residual value for shareholders.
We therefore consider BVPS very important to track for insurers and a metric that sheds light on business quality because it reflects long-term capital growth and is harder to manipulate than more commonly-used metrics like EPS.
Progressive’s BVPS grew at an exceptional 14% annual clip over the last five years. The last two years show a similar trajectory as BVPS grew by 13.3% annually from $46.36 to $59.51 per share.
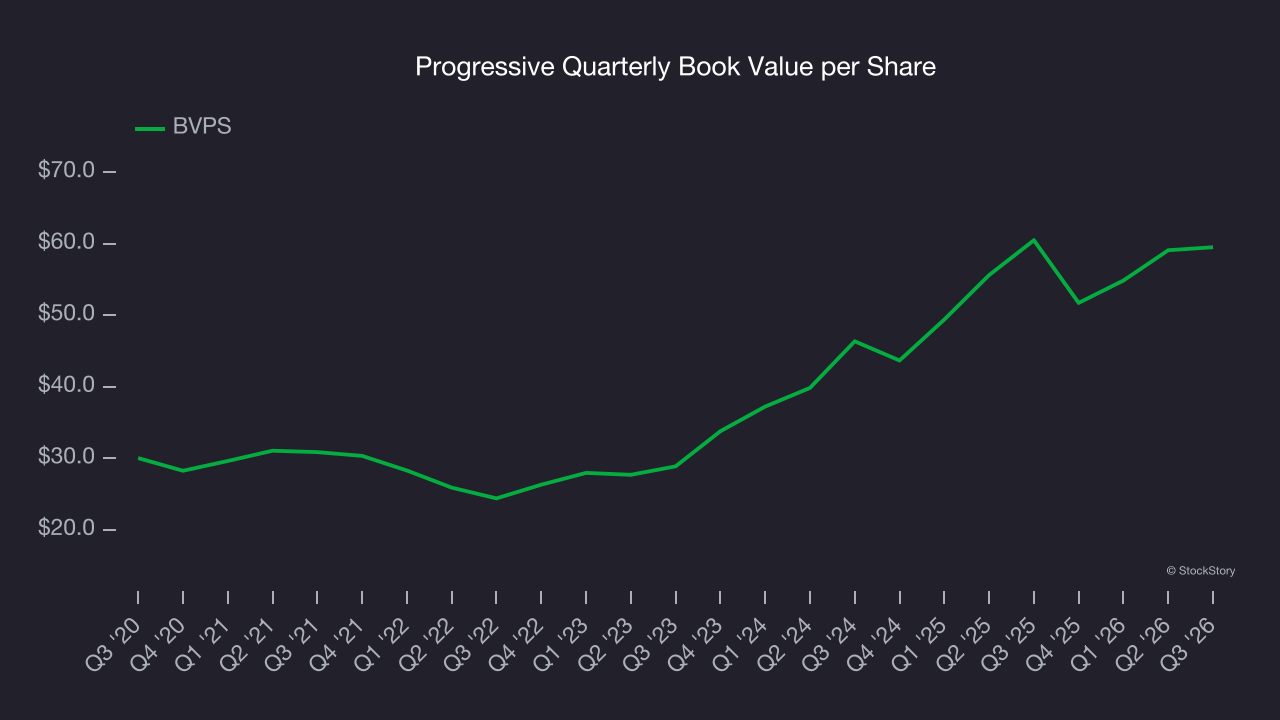
Over the next 12 months, Consensus estimates call for Progressive’s BVPS to grow by 30.5% to $62.85, elite growth rate.
Key Takeaways from Progressive’s Q3 Results
We struggled to find many positives in these results. Its book value per share missed and its EPS fell short of Wall Street’s estimates. Overall, this quarter could have been better. The stock traded down 9.4% to $202.00 immediately following the results.
Progressive’s latest earnings report disappointed. One quarter doesn’t define a company’s quality, so let’s explore whether the stock is a buy at the current price. When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).