
Infineon Technologies (XTRA:IFX) Could Be 11% Overvalued On New Bangkok Capacity
Infineon Technologies (XTRA:IFX) just cut the ribbon on a new backend manufacturing site in Bangkok, giving the semiconductor group more capacity, geographic diversification, and sustainability-focused production for key automotive and industrial customers.
That new Bangkok facility lands at a time when Infineon Technologies’ share price has come under pressure in the short term, with the stock declining 13.42% over the past week and 16.80% over the past 90 days. At the same time, the year-to-date share price return of 46.35% and 1-year total shareholder return of 75.66% point to strong longer term momentum, which recent semiconductor sector volatility has only temporarily cooled.
Scan other chipmakers that echo Infineon Technologies’ push into power, automotive and energy infrastructure by reviewing the hand picked 92 AI infrastructure stocks in one place.
Infineon Technologies now trades at a sizeable discount to analyst targets, despite the new Bangkok capacity coming online and recent growth in revenue and net income. Is the market’s caution mispricing the story or protecting you?
Most Popular Narrative: 11.3% Overvalued
The most followed narrative around Infineon Technologies pegs fair value at €50.32, which sits below the recent close at €56. That gap is not huge, yet it is enough to raise the question of whether recent excitement has run ahead of the underlying valuation work.
The balance sheet looks very healthy, basically the company is owned by the share holders (equity €17.2b), and only a reasonably low share is held by the “banks” (debt €5.4b). Having that in mind, a ROE of 17.5% is a good result. It would be relatively straightforward to raise ROE to a higher figure by using the leverage effect of debt. IFX could sell more products by increasing production capacity, which would lead to more profit and this would directly increase ROE.
See why 21 investors see Infineon Technologies as 11% overvalued.
Result: Fair Value of €50.32 (OVERVALUED)
Still, the narrative leans heavily on continued capital investment paying off. Any setback in fab projects or weaker demand in key end markets could quickly challenge it.
Find out about the key risks to this Infineon Technologies narrative.
Another View on Infineon Technologies Valuation
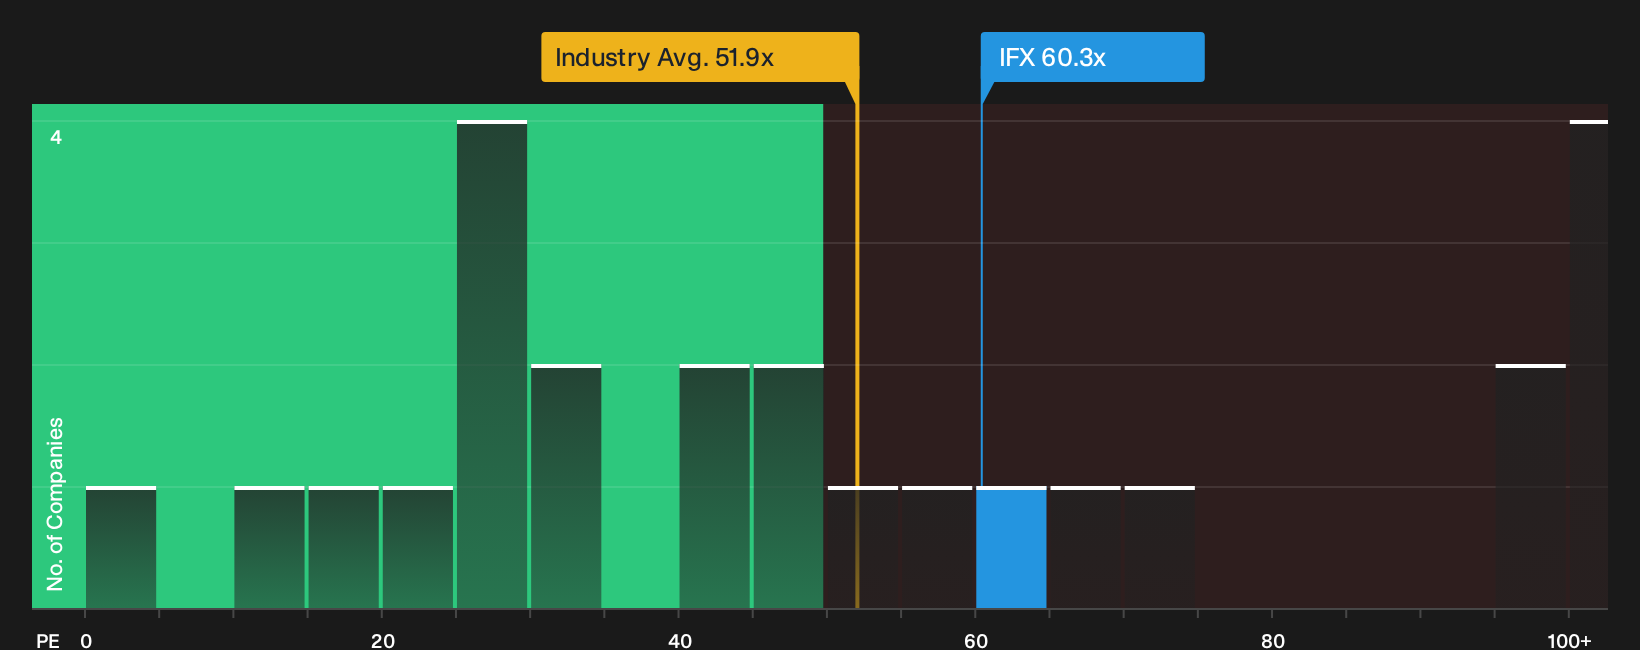
There is a second lens to look at Infineon Technologies. The current P/E of 60.3x sits just below its fair ratio of 60.8x and only slightly above the European semiconductor average of 51.9x. That points to a rich but not extreme valuation. Is this a premium you are comfortable paying for the story you believe in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Infineon Technologies can feel uncomfortable, so assess the evidence quickly, weigh both sides, and ground your own thesis in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Infineon Technologies?
If Infineon Technologies has sharpened your interest, do not stop at a single stock. Cast the net wider now so you are not late to the next opportunity.
- Target resilient compounders with steady fundamentals by scanning a 224 resilient stocks with low risk scores that filters for durability when markets feel fickle.
- Hunt for quality on sale by reviewing a 186 high quality undervalued stocks that blends solid balance sheets with discounted prices.
- Unearth potential future leaders before the crowd by checking a 617 high quality undiscovered gems focused on strong financials that have not yet grabbed headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com