
Commerce Bancshares (CBSH) Could Be 18% Below Fair Value On Earnings Focus
Wall Street expectations around Commerce Bancshares (CBSH) are in focus after research coverage highlighted a positive Earnings ESP and a Zacks Rank #3 in advance of the bank's September 2026 quarterly report.
Commerce Bancshares shares trade at US$54.29 and have eased in the short term, with the 30 day share price return down 6.8% and the 1 year total shareholder return slipping 1.2%. However, the 3 year total shareholder return of 34.9% points to stronger momentum over a longer stretch as investors weigh current earnings expectations against past compounding gains.
Spot similar regional bank stories by scanning our hand picked list of solid balance sheet and fundamentals (25 results). These selections mirror Commerce Bancshares' mix of earnings attention and balance sheet focus.Commerce Bancshares now trades meaningfully below both fair value estimates and analyst targets after that recent pullback. Is the market prudently fading earnings optimism, or overlooking a reasonably priced regional bank franchise?
Most Popular Narrative: 18% Undervalued
Against the last close at $54.29, the most followed narrative pegs Commerce Bancshares at a fair value of about $66.56. This points to a material valuation gap that banks on fee income, wealth management and digital investments holding up through different rate and credit conditions.
Further growth in Commerce Bancshares’ fee-based businesses, which already contribute about 37% of revenue and are led by national payments and a large wealth platform, could add relatively stable, less balance-sheet-sensitive revenue.
Completion of the FineMark systems conversion targeted for Q4 2026 creates room for Commerce Bancshares to capture more operating synergies across roughly $8.7 billion of acquired trust assets and related loans and deposits, which may support earnings and fee income efficiency.
See why 1 investors see Commerce Bancshares as 18% undervalued.
Result: Fair Value of $66.56 (UNDERVALUED)
Still, the Commerce Bancshares story could shift if net interest margin pressure lasts longer than analysts expect, or if acquisition related costs stay elevated and weigh on profitability.
Find out about the key risks to this Commerce Bancshares narrative.
Another View: Commerce Bancshares Through Earnings Multiples
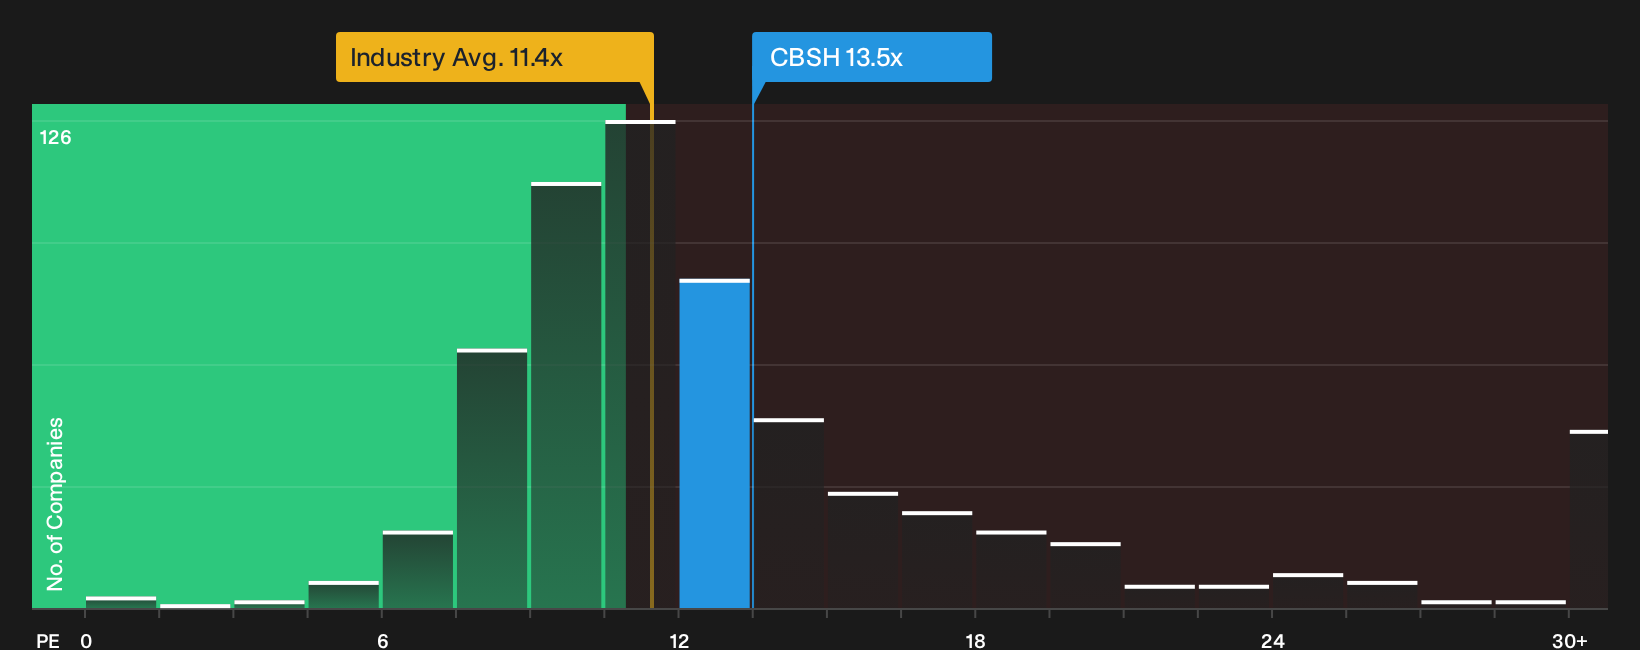
On the flip side, Commerce Bancshares looks expensive on earnings. The stock trades on a P/E of 13.5x, compared with 11.5x for the wider US Banks group and a fair ratio of 11.8x. That higher starting point can limit upside if sentiment cools or sector pricing narrows.
For investors who prefer simple earnings comparisons over cash flow models, this kind of gap is worth tracking. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Commerce Bancshares valuation and earnings can be confusing. Move quickly, review the data yourself, and weigh both sides of the story with 5 key rewards and 1 important warning sign
Looking for more ideas beyond Commerce Bancshares?
If Commerce Bancshares has sharpened your focus on valuation and risk, you can keep that momentum going by hunting for fresh opportunities before they move out of reach.
- Target quality at a discount by scanning companies that pass strict fundamentals checks using the 32 high quality undervalued stocks.
- Prioritize resilience and aim to sleep better at night by filtering for steadier businesses through the 32 resilient stocks with low risk scores.
- Look for early stage opportunities with stronger financial profiles inside the 11 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com