
Progressive (PGR) Stock Looks About Right Despite Strong Underwriting Results
Progressive has delivered a powerful long term share price gain, yet the past year has been much flatter, which puts fresh attention on what investors are really paying for its earnings today. With the stock recently closing at US$222.88, the key issue is how that price lines up with the strength and quality of the insurer's profit engine.
- Over the last 5 years, Progressive has returned 168.8%, which raises the question of how much of that long run advance can be traced back to durable earnings power.
- Recent results showed revenue growth alongside better underwriting, which can support expectations for more resilient profits and may influence how much investors are willing to pay per dollar of earnings.
- Your read on Progressive is one view; the desks covering it have another. See what analysts think Progressive's shares could be worth.
The stock's next move may depend on whether Progressive's current price can be squared with what its earnings justify today.
To compare Progressive with other insurers through the same earnings lens, a focused stock screen is a useful next step, starting with 32 resilient stocks with low risk scores.
Where Does Progressive Sit on Earnings?
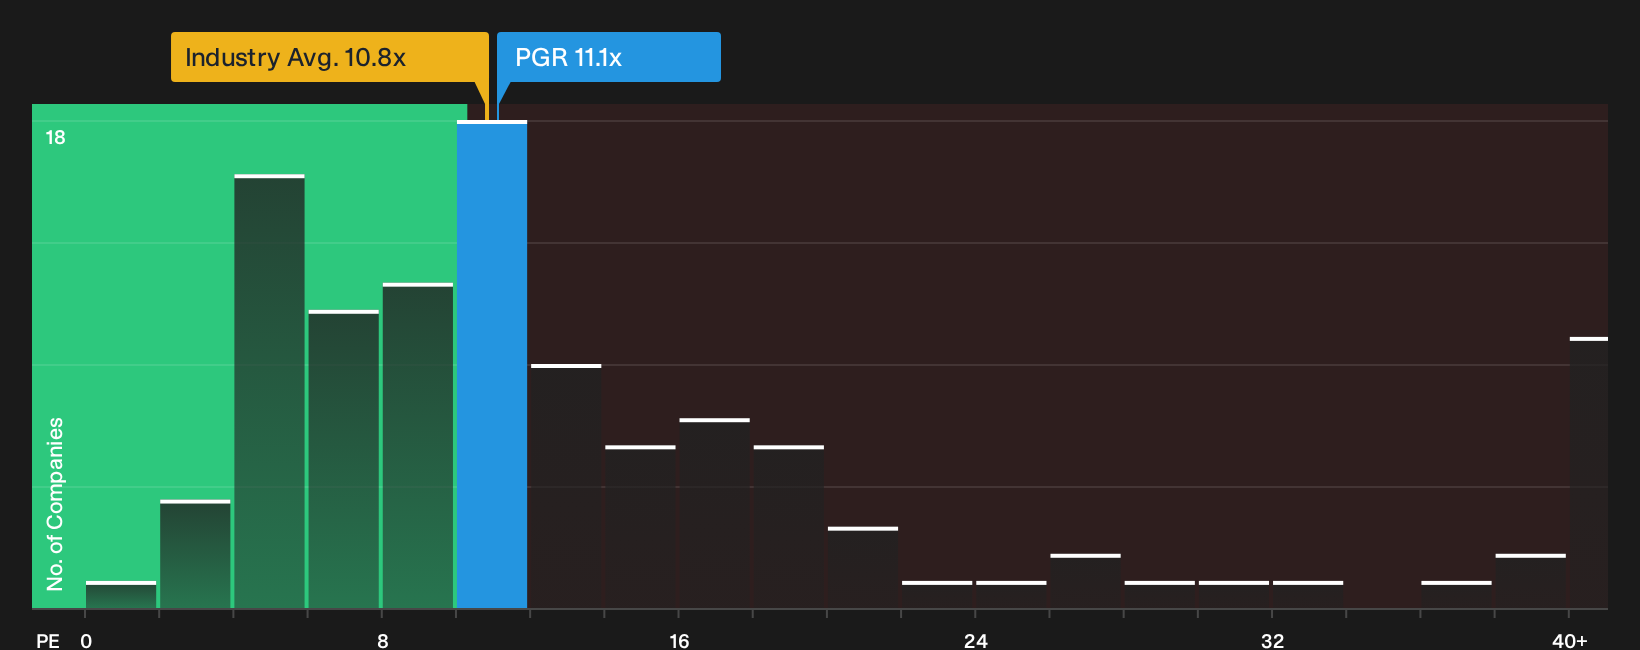
The P/E ratio suits Progressive because earnings drive most of the story for a mature insurer. On this measure, the stock trades on about 11.1x earnings, close to both the insurance industry average of roughly 10.8x and a peer group around 8.2x. That leaves Progressive priced at a premium to many direct competitors but not far from the broader sector yardstick.
Results for the quarter to September 2026 showed higher revenue and improved underwriting, and the market is effectively valuing Progressive at a level that lines up with what a tailored fair multiple model suggests for its risk and return profile. Because that current P/E sits near the multiple implied by those company specific inputs, the ratio points to a valuation that is broadly in line with what those earnings characteristics might support. Despite the recent news supporting confidence in the underwriting track record, the stock is not being marked up aggressively above that earnings based benchmark. Explore the numbers behind Progressive's P/E valuation.
The Progressive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off by spelling out which future paths for Progressive's growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price. Each scenario links a fair value to a specific mix of potential catalysts and risks so you can watch over time which storyline lines up with real world results on the Community page.
Progressive attracts two very different readings from the community, with one side seeing enough strengths to keep backing, while the other focuses on softer pricing and thinner cushions for missteps.
Bull case: roughly fairly valued
"The main thing that has to go right is that Progressive continues to translate its long-running investments in analytics, telematics, and AI into underwriting and expense efficiency..."
Discover why this Narrative puts Progressive at roughly fairly valued.
Bear case: 13% overvalued
"Bearish analysts expect Progressive to see slower personal auto policy growth and compressed margins as price decreases, higher advertising spend, and a soft market weigh on profitability..."
Explore why this Narrative puts Progressive at 13% overvalued.
One last Progressive check that sits beside the price tag
Before you stop at the P/E and storylines, it helps to look at who is actually steering Progressive and how their rewards line up with your priorities. See who runs Progressive and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com