
BeOne Medicines (ONC) Stock Trades Above Fair Value Following Its 103% Run
BeOne Medicines has logged a 3 year share price gain of 103.5%, leaving investors asking whether the current US$349.08 level is adequately grounded in the company’s earnings power. With that kind of move already on the table and the stock still in the headlines, the key issue is how much profit the business is realistically set up to deliver.
- A rise of 103.5% over three years puts a lot of expectations into BeOne Medicines, which raises the stakes on whether its earnings justify today’s valuation.
- The recent pan Canadian Pharmaceutical Alliance agreement for TEVIMBRA may support expectations for future profitability, since wider reimbursement can influence revenue visibility and the timing of cash inflows from its oncology portfolio.
- There is a second opinion on BeOne Medicines worth weighing. See what analysts think BeOne Medicines's shares could be worth.
For investors, the debate is whether BeOne Medicines' current share price fairly reflects what its earnings can support over the coming years.
If you are considering BeOne Medicines based on its earnings story and want more ideas with a similar filter, a focused screener of 33 healthcare AI stocks.
Does BeOne Medicines Look Pricey on Earnings?
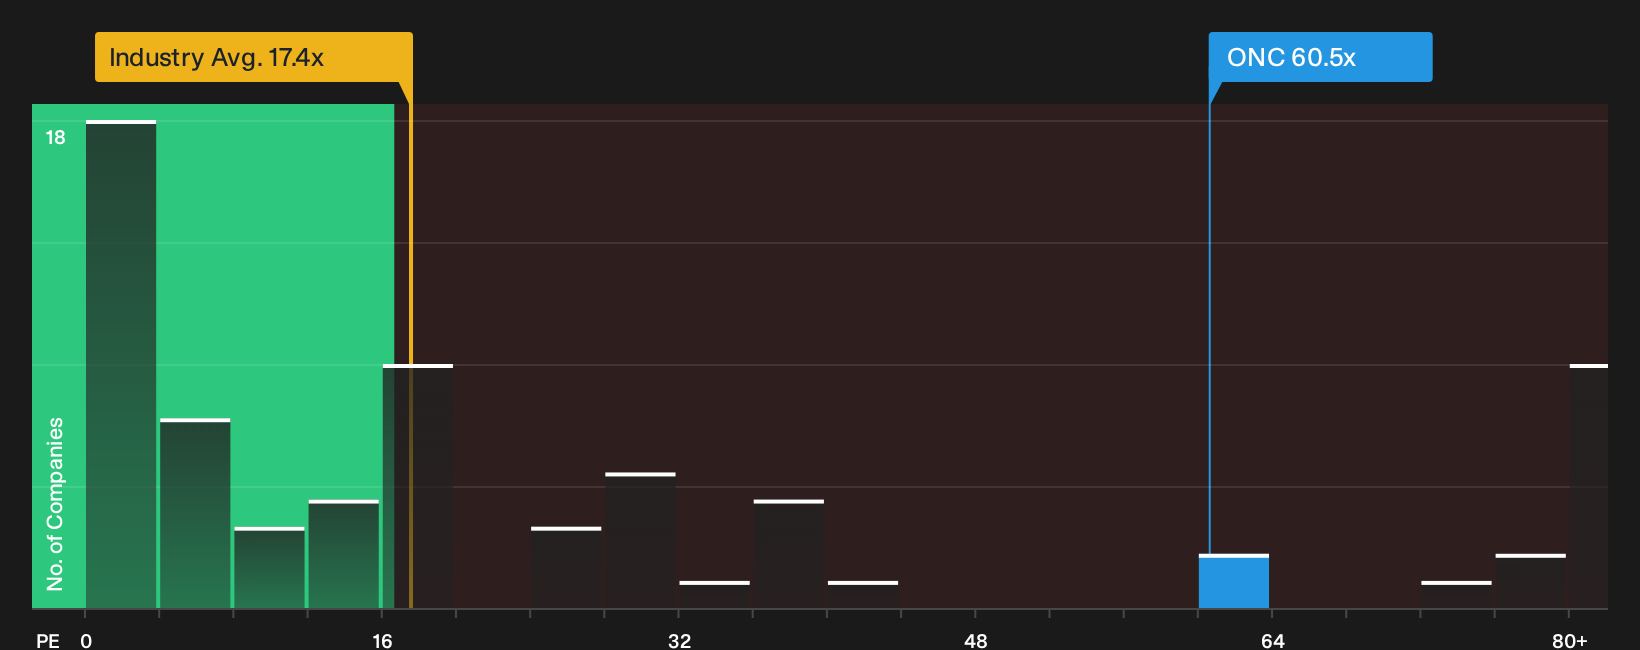
The P/E ratio is a useful yardstick here because BeOne Medicines already reports earnings and investors can compare what is being paid for each dollar of profit. At about 60.5x earnings, the stock trades well above the broader Biotechs sector, where the average P/E is roughly 17.4x, and above the peer group reference point of about 27.7x. That gap suggests buyers are accepting a much richer tag for BeOne Medicines than for many other listed drug developers.
The Fair Ratio model, which adjusts for factors such as growth expectations, margins, size and risk profile, points to a lower P/E than the market is currently assigning. Because the TEVIMBRA pCPA deal in Canada has sharpened interest in BeOne Medicines and raised attention on its oncology pipeline, the current premium implies investors are already baking in a strong earnings contribution from these assets. Anyone considering the shares needs to judge whether that confidence is justified at this P/E level. Explore the numbers behind BeOne Medicines's P/E valuation.
The BeOne Medicines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where BeOne Medicines' rich P/E debate leaves off. They spell out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today’s price, on the Community page. Each scenario ties a fair value to a particular mix of catalysts and risks so you can track which storyline comes closest to how BeOne Medicines' journey actually unfolds over time.
One of the top community narratives on BeOne Medicines: 31% undervalued
"Strong drug performance, global expansion, and pipeline productivity position BeOne Medicines for accelerating market leadership, diversified growth, and substantial margin improvements..."
Discover why this Narrative puts BeOne Medicines at 31% undervalued.
One more cross check for BeOne Medicines before you stop at the P/E debate
Price comparisons tell you what the market is paying today, but the next layer is how professional analysts currently frame this business a few years from now, and whether that picture lines up with your thesis. Explore where analysts expect BeOne Medicines to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com