
What Akamai Technologies Doubters Overlooked
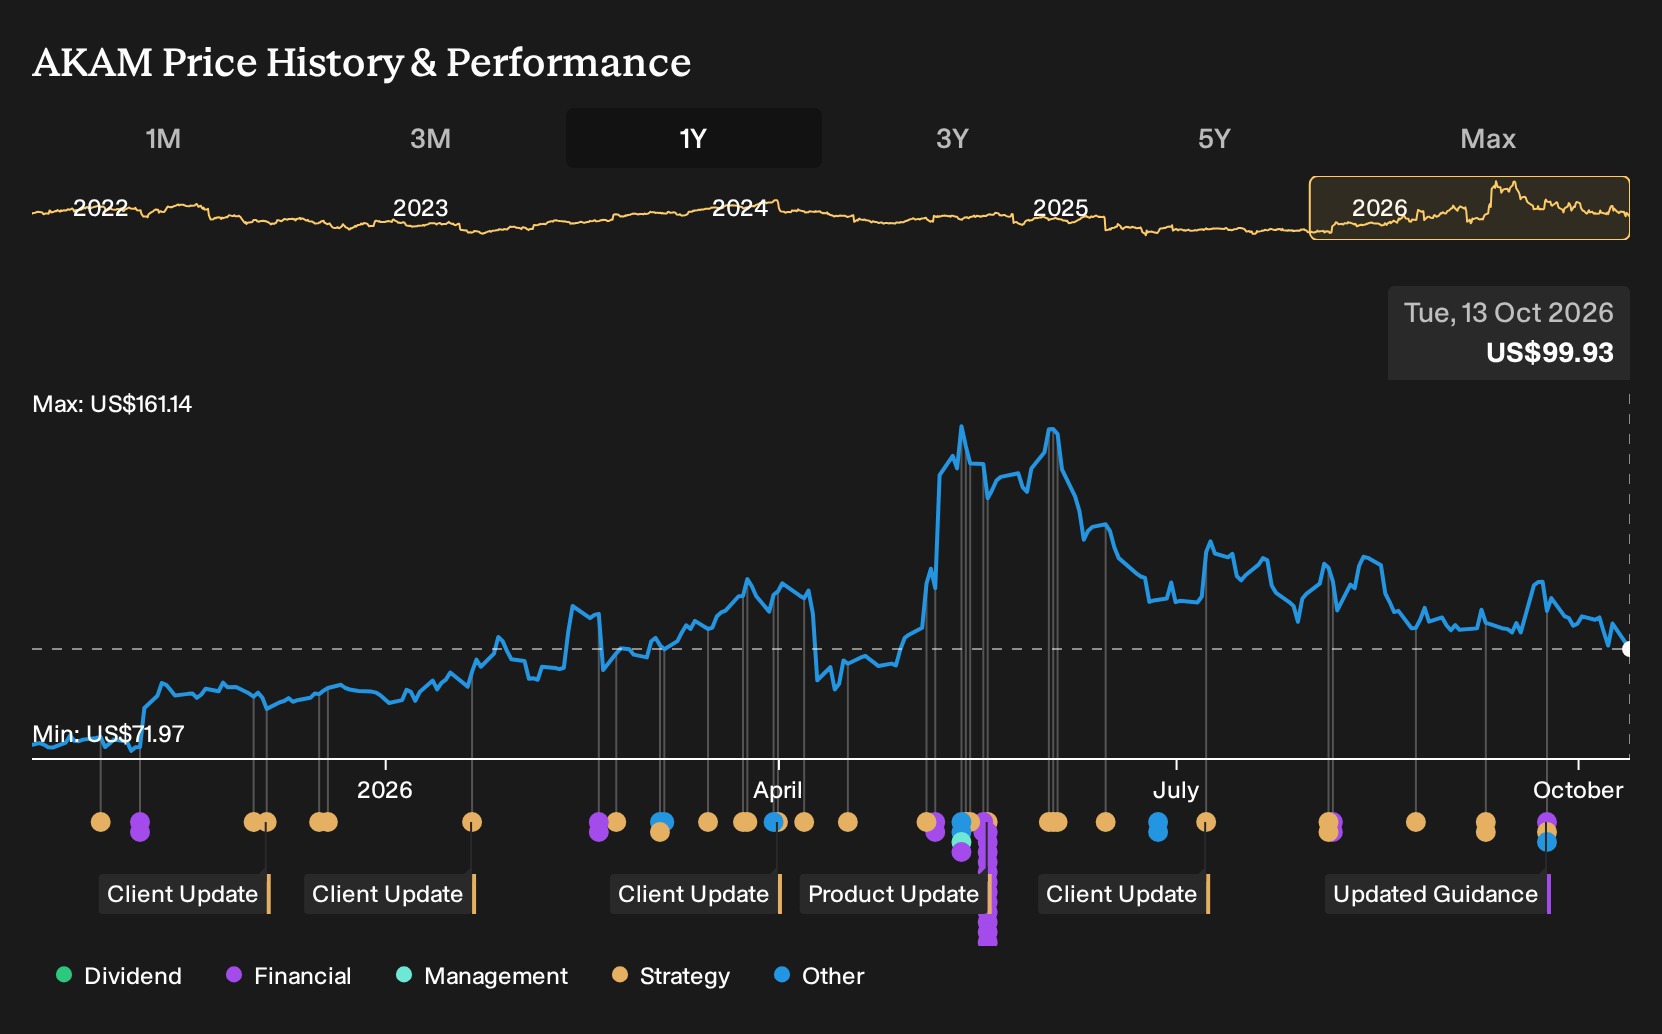
If Akamai Technologies was sitting on your watchlist instead of in your account, the outcome may feel like a missed shot. For Akamai Technologies shareholders, the return over the past year was 34.9%, including dividends. That result arrived during a period when bulls argued cloud, AI and cybersecurity could support higher revenue and margin assumptions, while bears warned that hyperscale vendors and commoditized delivery might cap the upside. If you were deciding back in October 2025, which of those business stories would have seemed more convincing?
Akamai Technologies has already moved. Pinpoint other ways to investigate the theme among 92 AI infrastructure stocks.
The Two Narratives Investors Had To Weigh On Akamai Technologies
The shares cost US$73.79 at the start of the period, and anyone looking at Akamai Technologies then had to choose which story felt more realistic.
The optimistic narrative pointed to a Fair Value of US$95.20. This was essentially a price implied by expectations that revenue might grow 6.1% a year, with profit margins reaching 15.7% over roughly three years.
The cautious narrative framed a Fair Value of US$63.92. This was based on assumptions that revenue growth would sit nearer 5.0% and profit margins would only edge up to 10.5% over that same stretch.
What The Results Changed For The Akamai Technologies Debate
Akamai Technologies signed a seven year AI cloud contract with Anthropic that was described as the largest agreement in its history, which supported the bullish focus on AI infrastructure and security. In the same period, revenue was US$1,099.7m compared with US$1,043.5m a year earlier, while net income and net margin declined, so the profitability part of the optimistic case remained unproven. The evidence pointed in both directions.
The key assumption here was that higher AI and cloud commitments would translate into stronger earnings, not just higher sales. For other companies, track whether revenue tied to large AI or cloud deals grows faster than net profit and reported margin over several reporting periods.
What Akamai’s Latest Jump Asks You To Believe
Akamai Technologies now trades at US$99.93, after a 34.9% gain over the past year. The selected Narrative’s Fair Value sits above the current price and leans on the idea that demand for its AI focused cloud and security stack can support this richer P/E.
The Narrative argues today’s quote still does not fully credit Akamai Technologies turning its sold out CIS and GPU pipeline into lasting, profitable cash flows.
"The main thing that has to go right is that Akamai secures and efficiently deploys the planned high colocation and GPU capex so that the current sold out CIS and GPU pipeline converts into durable, profitable revenue streams."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 31% below our estimate - uses an efficiency program and acquisition integration to emphasize higher margin aftermarket work.
- Company 2 - 42% below our estimate - expands a premium tea chain while analyzing its membership base to drive repeat spending.
- Company 3 - 28% below our estimate - relies on demand for high performance AI chips and software in data centres.
Those are three of them. See the full list of 32 companies trading below our estimate →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com