
AT&T (T) Stock Still Looks Below Fair Value As Its 82% Run Gets Tested
AT&T has delivered a strong multi year return, yet the recent share price drop has brought its earnings based valuation back into focus. With the stock now around US$22.85, the question is whether that level still lines up with what the business is earning today.
- Over the past 3 years the share price has gained 82.1%, which puts real pressure on the current earnings to justify how far the stock has come.
- The agreed sale of AT&T Mexico and the planned U.S. fiber joint venture may support a shift in where cash is generated and how capital is invested, which matters directly for any earnings based valuation.
- There is a second opinion on AT&T worth weighing. See what analysts think AT&T's shares could be worth.
The issue now is whether AT&T's recent share price, after that strong multi year run and the latest corporate moves, is adequately supported by its current earnings power.
If you want to stress test this same earnings question beyond AT&T, widen the lens to a basket of 32 high quality undervalued stocks.
Is AT&T Still Cheap on Earnings?
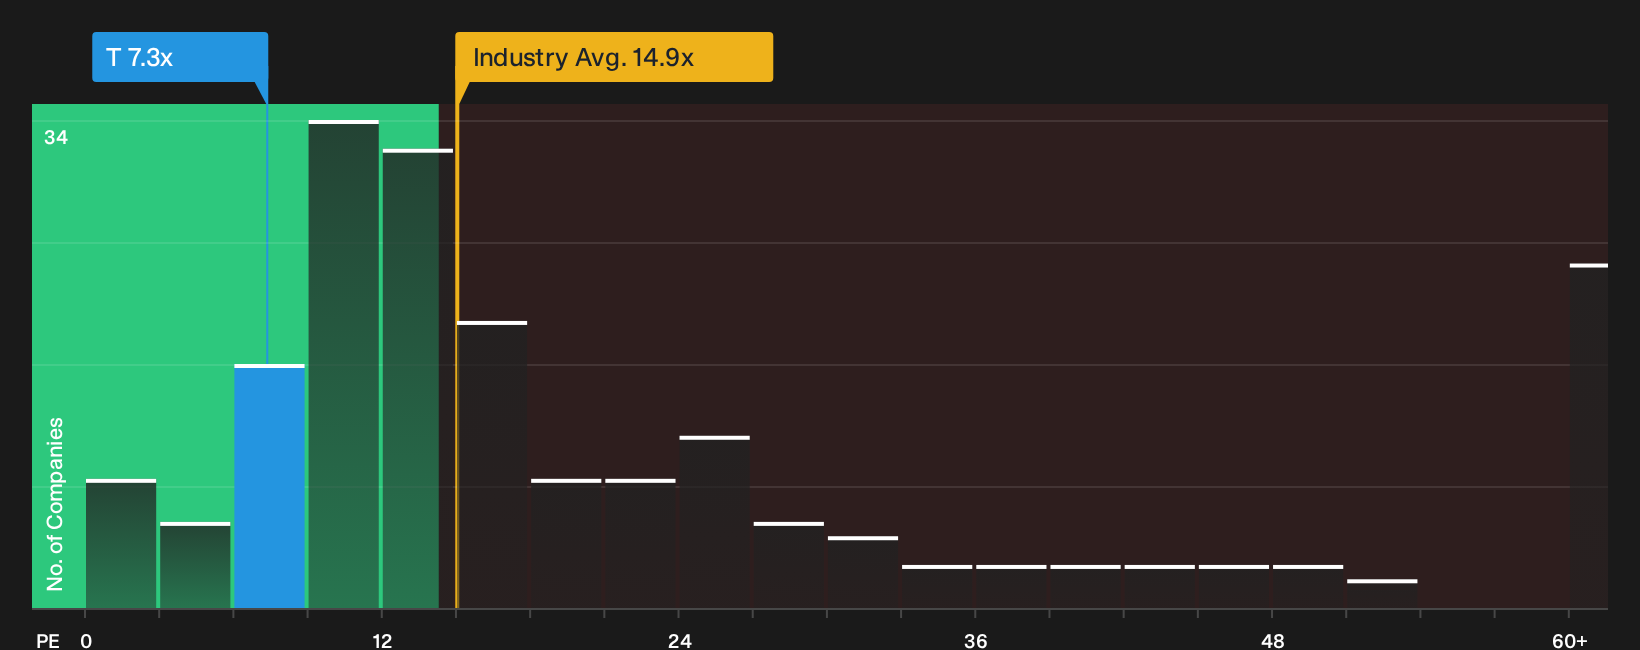
P/E suits AT&T because investors often frame mature telecoms around steady earnings rather than rapid revenue swings. On that yardstick, AT&T trades on a P/E of 7.3x, compared with a telecom industry average of about 14.9x and a peer group near 11.6x. The stock also screens below the multiple suggested by a more tailored fair P/E that factors in AT&T's own scale, profitability profile and risk mix, which points to a valuation discount rather than a premium.
Because the agreed sale of AT&T Mexico and the planned U.S. fiber joint venture concentrate more of AT&T's effort on its core domestic connectivity platform, the current earnings multiple reflects how the market prices that tighter focus today. For investors weighing AT&T against other telecom players, the gap between its 7.3x P/E and both sector and peer benchmarks highlights how much is being asked of the earnings story to close that spread over time. Explore the numbers behind AT&T's P/E valuation.
The AT&T Narrative: What Would Justify Today's Price?
AT&T's valuation puzzle only really comes into focus once the future behind those earnings multiples is laid out in plain terms. Simply Wall St Narratives on AT&T map out what kind of growth, margins and earnings profile would need to show up for the share price to sit meaningfully higher or lower than today, and where a single ratio or model gives one number, they unpack the future that number relies on so you can watch whether it actually plays out over time on the Community page.
One of the top community narratives on AT&T: 21% undervalued
"The key requirement is that AT&T executes on large scale fiber build out, copper retirement, and cost take out while managing device subsidies..."
Discover why this Narrative puts AT&T at 21% undervalued.
One more AT&T checkpoint that sits beyond today's share price
There is a separate lens that compares where AT&T trades today with where professional analysts think its earnings profile could be a few years from now. Explore where analysts expect AT&T to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com