
Is Intuitive Machines (LUNR) Undervalued Or Is Its Premium Already Priced In?
Intuitive Machines (LUNR) drew fresh attention after recent trading left the share price at US$12.18, with declines over the past week, month, and past 3 months sharpening investor focus on both risk and potential reward.
Short-term momentum for Intuitive Machines looks weak, with the share price return down 19.1% over the past week and 31.9% year to date. However, the 3-year total shareholder return of about 244% signals that longer term holders have still seen very strong gains despite the recent pullback. This pattern may indicate that investors are reassessing both growth prospects and risk after a volatile run.
Compare Intuitive Machines' recent pullback with other high potential opportunities by scanning a hand picked list of 20 high quality undiscovered gems, which also pair strong fundamentals with under the radar pricing.
For Intuitive Machines, the recent slide raises a straightforward decision point for investors. Does the current US$12.18 level already reflect the risks, or does it make more sense to wait for an even cheaper entry once valuation is discussed next?
Most Popular Narrative: 47% Undervalued
On one side, Intuitive Machines trades at $12.18. On the other, the most followed narrative, according to sorkdhkddlek, points to a fair value near $23, which frames the recent pullback as a deep discount rather than just noise.
Balancing High-Growth Potential with Capital Dilution Intuitive Machines (LUNR) has been described as shifting from a high-risk startup to a Lunar Infrastructure Prime, backed by a $943M backlog and a pivot toward high-margin data services via the Lanteris acquisition. Some observers note that, in their view, a trajectory toward positive Adjusted EBITDA in 2026 is clear, while also arguing that the current stock price reflects a "perfection premium" that may overlook recent share dilution.
See why 25 investors see Intuitive Machines as 47% undervalued.
Result: Fair Value of $23 (UNDERVALUED)
Still, Intuitive Machines hinges on successful mission execution and funding access, so any failed landing or tighter capital markets could quickly challenge that 47% undervalued story.
Find out about the key risks to this Intuitive Machines narrative.
Another View: Intuitive Machines Through Market Ratios
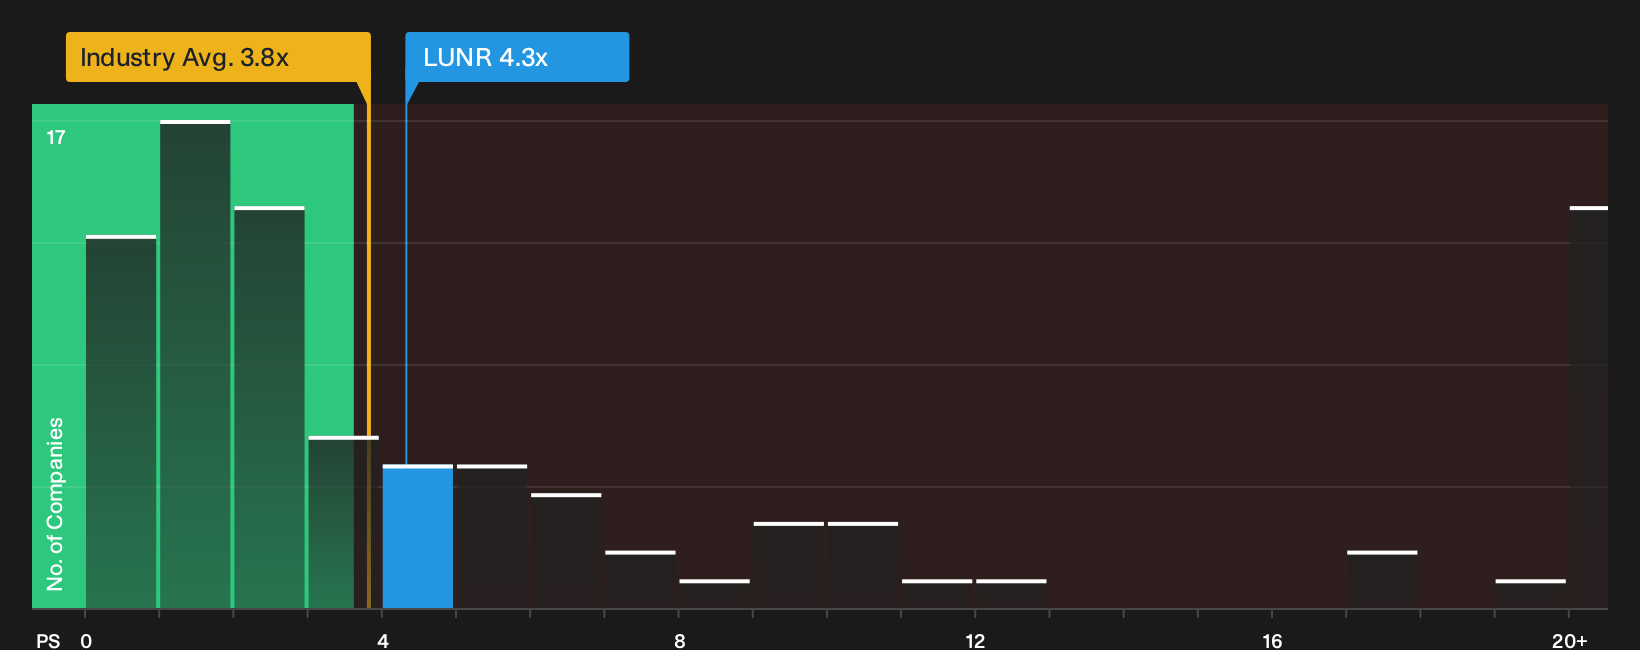
The narrative places Intuitive Machines near a $23 fair value using revenue multiples, yet the preferred P/S check presents a tougher picture. At $12.18, LUNR trades on a 4.3x P/S, above both the peer average at 3.1x and the US Aerospace & Defense group at 3.8x.
The fair ratio sits lower again at 2.3x, which suggests the market price reflects richer expectations than either peers or that fair ratio imply. For anyone weighing the 47% undervalued story, the question becomes straightforward: is that premium a source of comfort, or a valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Intuitive Machines is split, which is exactly why it pays to review the full set of risks and potential upsides yourself. To weigh those trade offs side by side and reach your own view, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Intuitive Machines?
Do not stop your research with Intuitive Machines. Use the Simply Wall Street Screener to quickly surface fresh ideas that fit the kind of portfolio you actually want.
- Target resilient compounding potential by searching for companies with strong cash positions and low leverage through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by scanning the 32 high quality undervalued stocks that combine robust fundamentals with prices that still look conservative.
- Add a defensive layer to your watchlist by checking out 32 resilient stocks with low risk scores that score well on financial strength and volatility metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com