
Green Plains (GPRE) Faces EPA Proposal To Reallocate 100% Of Waived Ethanol Volumes
- Green Plains (NasdaqGS:GPRE) faces a key policy shift as the EPA proposes revisions to Renewable Fuel Standard volumes in October 2026.
- The proposal would reallocate 100% of the gap between projected and actual small refinery exemptions back into renewable fuel obligations.
- EPA's approach directly preserves baseline domestic ethanol demand tied to previously waived small refinery exemption volumes.
- This full reallocation of waived small refinery exemptions into Renewable Fuel Standard volumes deserves weighing against our other findings on Green Plains. Take a look at 1 warning sign we have identified for Green Plains.
For a broader read on how energy transition policies are reshaping adjacent infrastructure plays, see the trend identified by 43 power grid technology and infrastructure stocks.
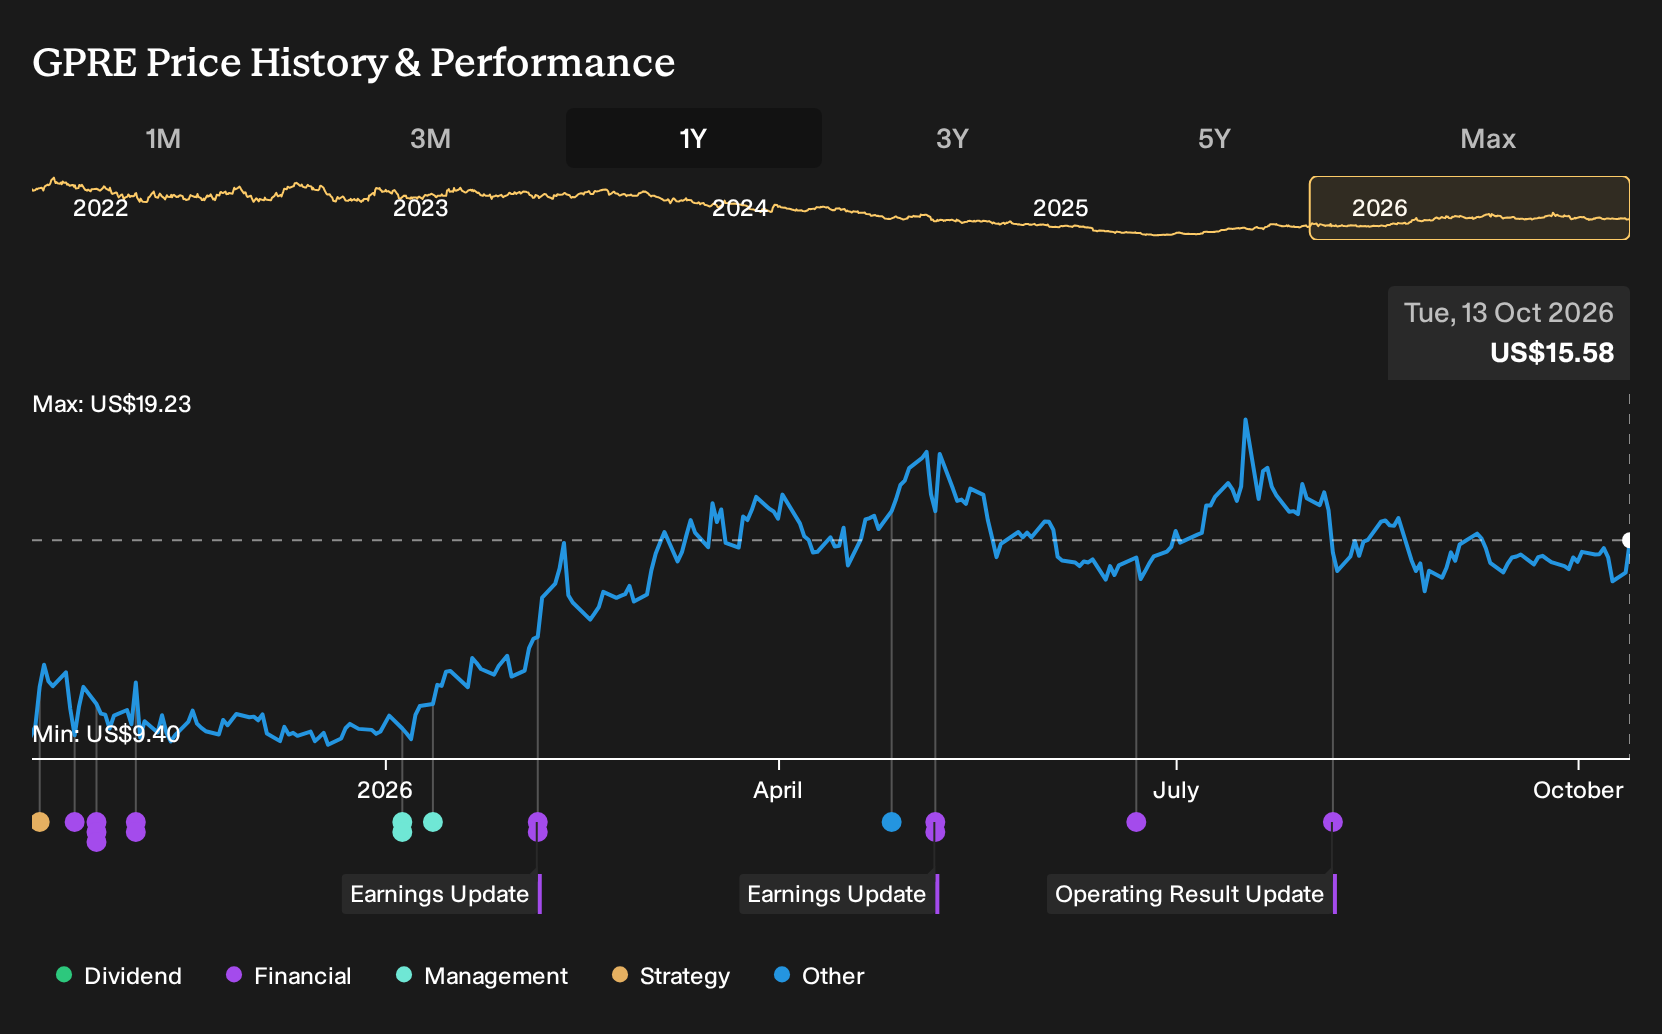
Green Plains produces low carbon fuels in the US and internationally, so its fortunes are closely tied to how regulators define and enforce renewable blending rules. As a roughly $1.0b oil and gas player focused on ethanol, policy tweaks to Renewable Fuel Standard volumes can directly influence how its core product competes against traditional fuels.
See how Green Plains's balance sheet measures up.
How this EPA move feeds into the Green Plains policy-heavy Narrative
Green Plains’ Narrative is built on the idea that policy support for low carbon fuels turns its ethanol plants into higher margin, tax-credit-backed refineries, and that operational upgrades convert those incentives into durable earnings. The EPA proposal on Renewable Fuel Standard volumes plugs directly into that policy-dependent storyline.
"Extension and enhancement of government incentives, specifically the confirmation and expansion of the 45Z clean fuel production tax credit through 2029 (and policies rewarding US/North American feedstock), position Green Plains to significantly increase recurring revenues and EBITDA from low-carbon ethanol production, projecting $150M+ annualized EBITDA from just three plants with all nine expected to qualify in 2026..."
See how the full story points towards a $17.71 fair value for Green Plains.
This proposed reallocation of small refinery exemptions supports the Narrative’s core bet that policy keeps ethanol demand intact while Green Plains leans into low carbon credits like 45Z. It reinforces the idea that plant-level efficiency and coproduct mix, not just commodity prices, underpin refinery-like earnings power against peers such as Alto Ingredients and Valero’s ethanol units.
Regulatory relief from waivers does not erase the Narrative’s main risk, which is heavy reliance on long-dated incentives and carbon credit monetisation. The unresolved question is duration, because if future rulemakings or political shifts shorten or dilute those supports, the planned ramp in high margin low carbon volumes and coproduct earnings becomes harder to realise.
Reading this kind of policy news usefully means framing it against where Green Plains is trying to go, which is exactly what its Narrative is designed to map out.
Add Green Plains to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com